
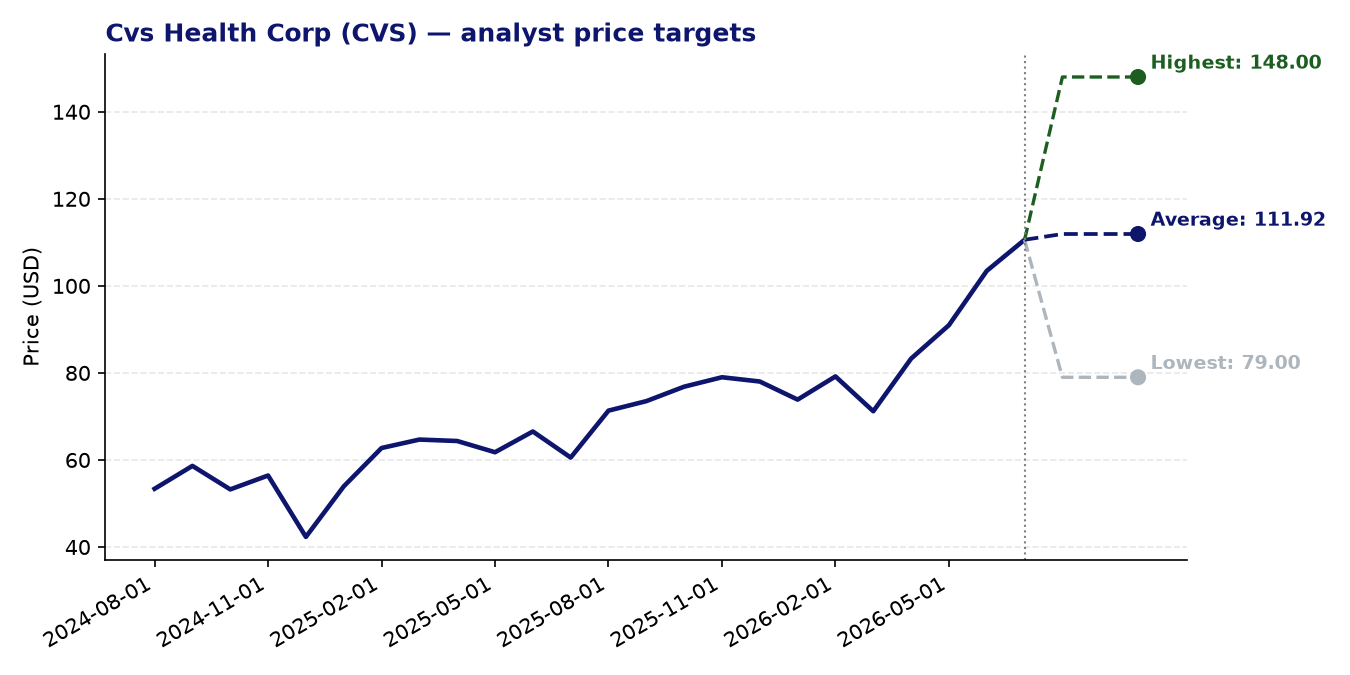
Cvs Health Corp (CVS) — current price: 110.60 USD | average price target: 111.92 USD | potential: +1.2%
About Cvs Health Corp
- CVS Health is a diversified US healthcare company founded in 1963 and headquartered in Woonsocket, Rhode Island, operating across three main business segments.
- Its Health Care Benefits segment provides a broad range of insurance products including medical, pharmacy, dental, and behavioral health plans, serving employer groups, individuals, and government-sponsored programmes including Medicare and Medicaid.
- The Health Services segment delivers pharmacy benefit management solutions, covering formulary management, specialty and mail-order pharmacy, clinical services, and disease management for a wide range of plan sponsors.
- The Pharmacy & Consumer Wellness segment operates retail pharmacy stores, online pharmacy platforms, specialty and compounding pharmacies, and infusion services, selling prescription drugs, over-the-counter products, and general consumer health merchandise.
Recent news
- Analysts noted earlier this year that CVS has a track record of exceeding quarterly earnings expectations, with some commentary suggesting the company was well-positioned to continue that pattern.
- A February assessment described CVS shares as appearing fully valued at that point, acknowledging strong returns but flagging that earnings multiples left limited further upside.
- CVS attracted attention in mid-2025 as a potential holding within a high-profile dividend-focused investment strategy associated with billionaire fund manager Larry Robbins, highlighting its income credentials.
Strengths
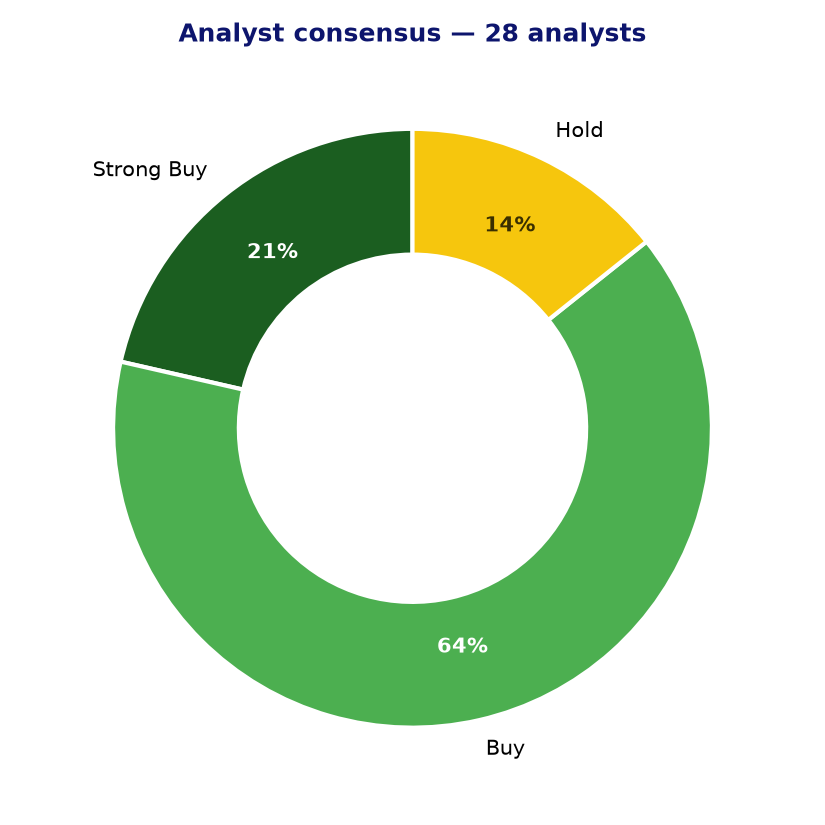
- Analyst sentiment is notably constructive: of 28 covering analysts, 24 rate the stock either buy or strong buy, with zero sell ratings recorded.
- The PEG ratio of 0.30 is well below the conventional threshold of 1.0, suggesting the market may not yet be fully pricing in the company’s earnings growth trajectory relative to its current valuation.
- The forward P/E of 13.15 is substantially lower than the trailing P/E of 48.51, implying that consensus forecasts anticipate a meaningful recovery in near-term profitability.
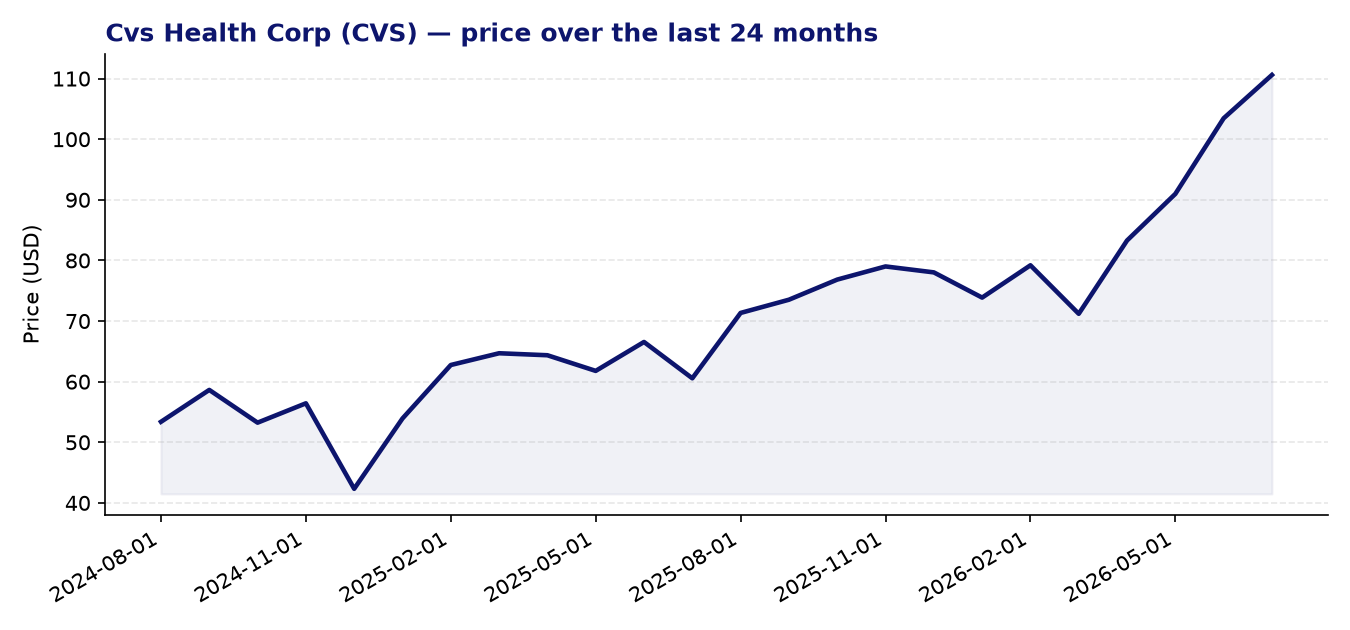
- A 24-month Z-score momentum reading of 2.39 indicates that the stock has shown above-average price momentum relative to its historical range, a broadly positive technical signal.
- CVS operates across complementary healthcare verticals — insurance, pharmacy benefit management, and retail pharmacy — providing meaningful revenue diversification and cross-selling opportunities.
Points of attention and risks
- The average analyst price target of 111.92 USD implies only around 1.2% upside from the current price, suggesting the near-term consensus view offers limited margin for appreciation even among broadly bullish analysts.
- The wide dispersion between the lowest price target (79.00 USD) and the highest (148.00 USD) reflects considerable uncertainty about the company’s fundamental outlook and earnings normalisation path.
- The trailing P/E of 48.51 is elevated, and while the forward multiple is more modest, the large gap between the two underscores meaningful execution risk: the forward valuation depends heavily on a sharp earnings rebound materialising as expected.
- CVS operates in the healthcare plans and pharmacy benefit management sector, which faces ongoing regulatory scrutiny, Medicaid reimbursement pressures, and potential changes to drug pricing legislation that could weigh on margins.
- EPS growth of 0.65 on a trailing basis reflects the earnings pressure the company has experienced, and investors should note that the more attractive forward metrics are contingent on a turnaround in profitability rather than confirmed results.
Analyst consensus and price targets
Conclusion
CVS Health presents an interesting combination of a diversified healthcare platform, a strongly bullish analyst consensus, and forward valuation metrics that appear undemanding relative to peers — particularly the low PEG ratio and forward P/E. However, the negligible near-term upside implied by the average price target, the significant spread in individual analyst estimates, and the execution risk embedded in the earnings recovery story warrant careful consideration. Investors with a longer time horizon and comfort with healthcare sector regulatory uncertainty may find the risk-reward profile worth evaluating, but the near-term picture is finely balanced.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 21-07-2026. Not investment advice.