
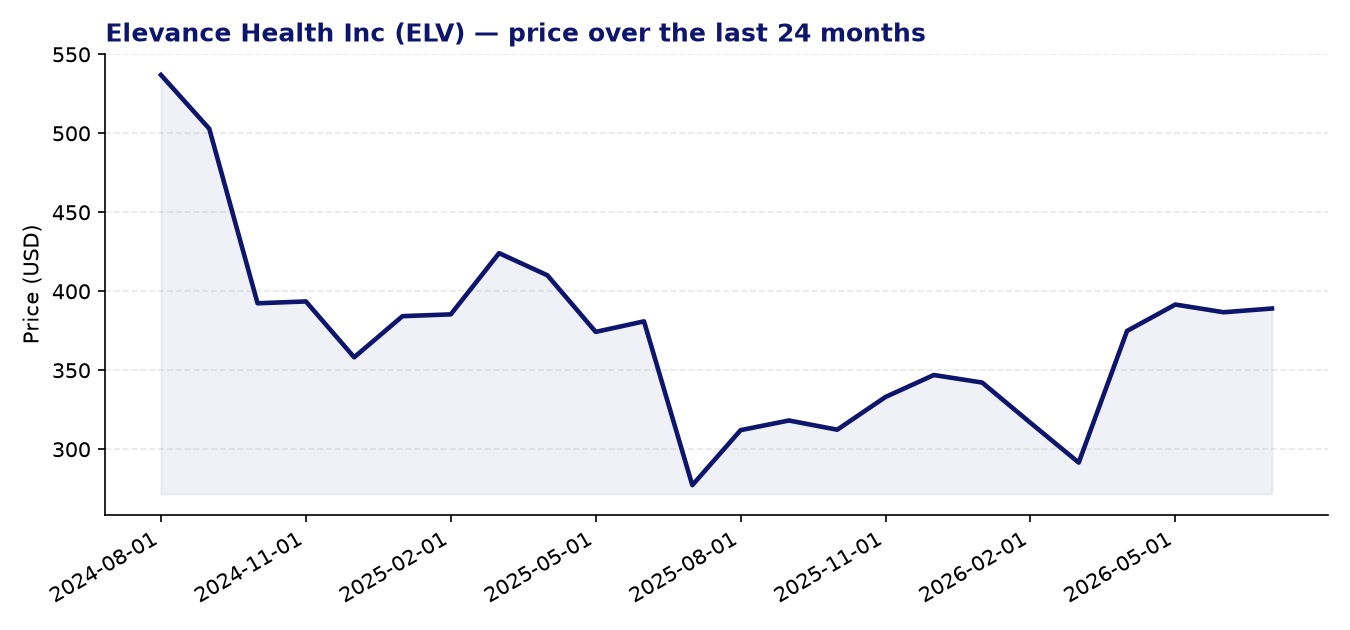
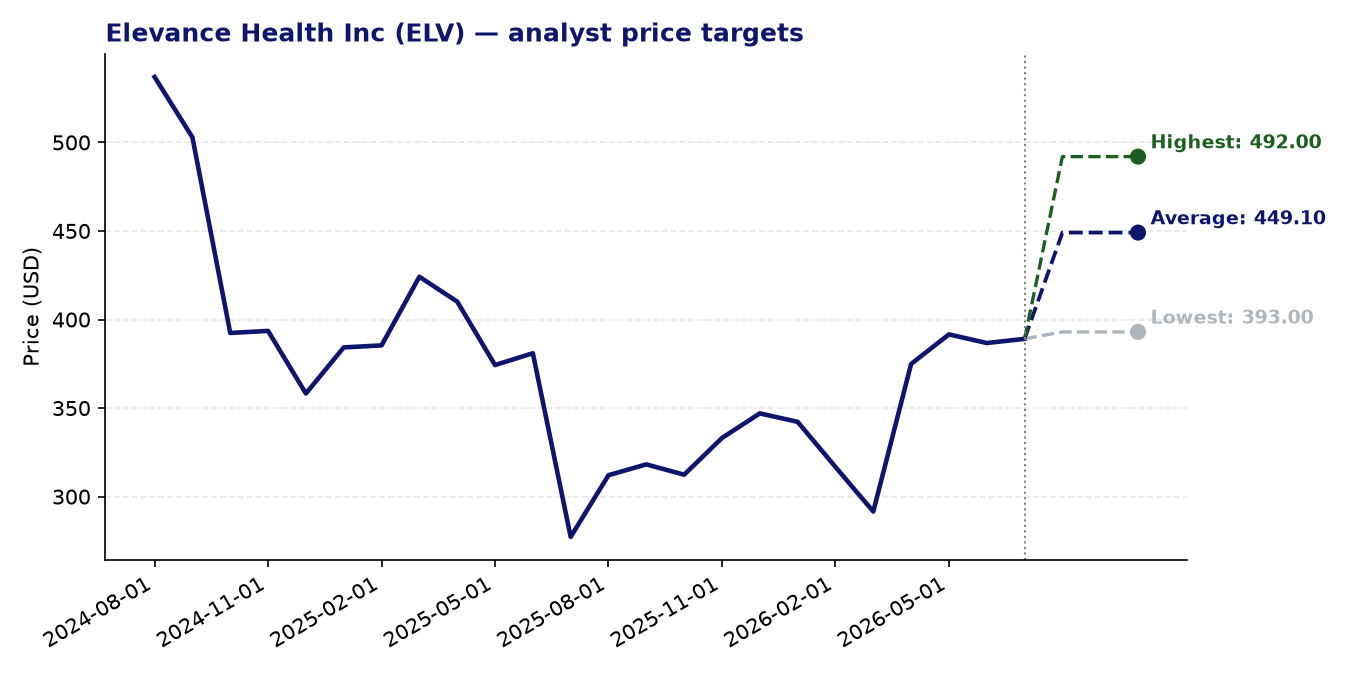
Elevance Health Inc (ELV) — current price: 389.09 USD | average price target: 449.10 USD | potential: +15.4%
About Elevance Health Inc
- Elevance Health is one of the largest US health benefits companies, offering a broad range of health plans to individual, employer group, Medicare, Medicaid, and federal employee programme members under the Anthem Blue Cross and Blue Shield, Wellpoint, and Carelon brands.
- The company operates four segments: Health Benefits, CarelonRx, Carelon Services, and Corporate & Other, allowing it to serve members across insurance, pharmacy, and care management.
- Through its CarelonRx division, Elevance provides pharmacy benefit management services including home delivery, specialty pharmacy, formulary management, and infusion therapies.
- Carelon Services delivers a wide array of healthcare capabilities including behavioural health, palliative care, virtual care, payment integrity, and data analytics via its HealthOS platform.
- Formerly known as Anthem Inc., the company rebranded as Elevance Health in June 2022 and is headquartered in Indianapolis, Indiana.
Recent news
- Elevance Health reported second-quarter 2026 results that exceeded Wall Street expectations, with earnings supported by stronger premium yields and continued expansion of its Carelon business, though the modest upgrade to full-year guidance was seen as underwhelming by the market, sending shares lower.
- Following the post-earnings share price decline, CEO Gail Boudreaux made her first open-market stock purchase since 2025, a signal of management confidence at current valuation levels.
- In the first quarter of 2026, Elevance posted revenues of approximately $50.2 billion and adjusted EPS of $12.58, both ahead of consensus estimates, with the stock rising around 5.5% on that release.
- The company has maintained full-year adjusted EPS guidance of approximately $26.75, providing a degree of earnings visibility for the remainder of 2026.
Strengths
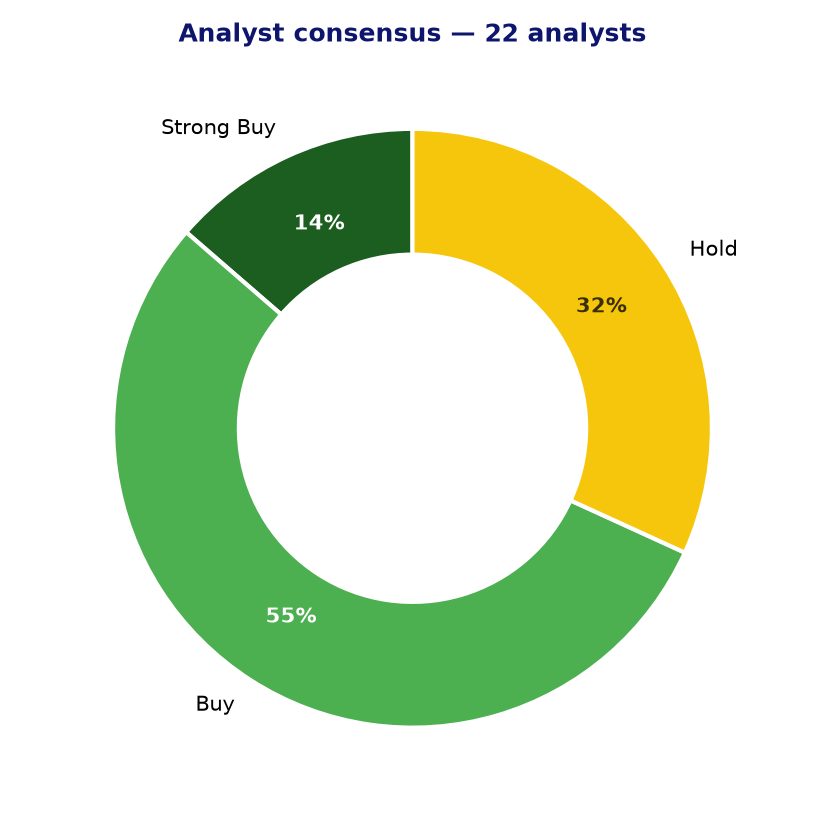
- The analyst community remains broadly constructive, with 15 out of 22 covering analysts rating the stock a buy or strong buy, and an average price target of $449.10, implying roughly 15% upside from the current price of $389.09.
- The 24-month Z-score momentum reading of 2.30 indicates that the stock has shown meaningful positive price momentum relative to its historical range, which can be a constructive technical signal.
- The forward P/E of 13.1x is meaningfully below the trailing P/E of 17.2x, suggesting earnings are expected to recover or grow, and the valuation does not appear stretched relative to the broader healthcare sector.
- CEO share purchases following a price decline are generally regarded as a meaningful vote of confidence from insiders who have detailed knowledge of the company’s operational outlook.
- Elevance’s diversified model — spanning insurance, pharmacy benefits, and healthcare services — reduces dependence on any single revenue stream and provides multiple avenues for organic growth.
Points of attention and risks
- Despite beating estimates, the market reacted negatively to second-quarter results, interpreting the modest guidance raise as insufficient given ongoing cost pressures in the managed care sector — a sign that investor expectations remain high and sentiment is fragile.
- EPS growth is currently reported at -0.16, reflecting near-term earnings pressure; while the forward P/E implies a recovery, this is not yet visible in trailing figures and introduces execution risk.
- The PEG ratio of 1.39 is above 1.0, suggesting the stock is not obviously cheap relative to its near-term growth rate, particularly if earnings recovery proves slower than currently projected.
- Managed care companies are exposed to structural pressures including rising medical cost ratios, Medicaid redetermination impacts, and ongoing regulatory scrutiny over prior authorisation and coverage practices.
- The lowest analyst price target of $393.00 sits only marginally above the current price, indicating that not all analysts see meaningful near-term upside, and that downside scenarios are plausible if guidance is revised lower.
Analyst consensus and price targets
Conclusion
Elevance Health presents a reasonably diversified healthcare business trading at a moderate forward valuation, with the majority of analysts maintaining positive ratings and a consensus price target pointing to mid-teens percentage upside. However, near-term earnings pressure, a market that appears to be holding the company to a high standard, and sector-wide cost headwinds temper the overall picture. Investors may find the combination of insider buying and a forward P/E of around 13x worth monitoring, while remaining attentive to upcoming guidance updates and medical cost trends as the year progresses.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 22-07-2026. Not investment advice.