
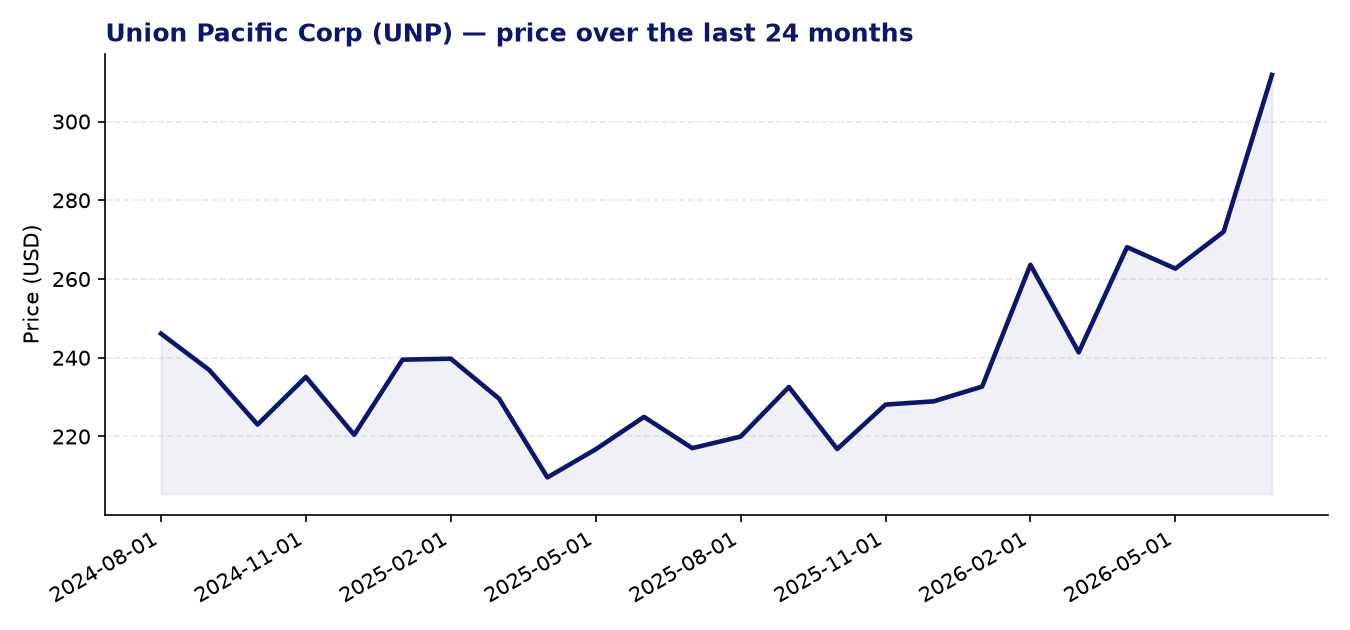
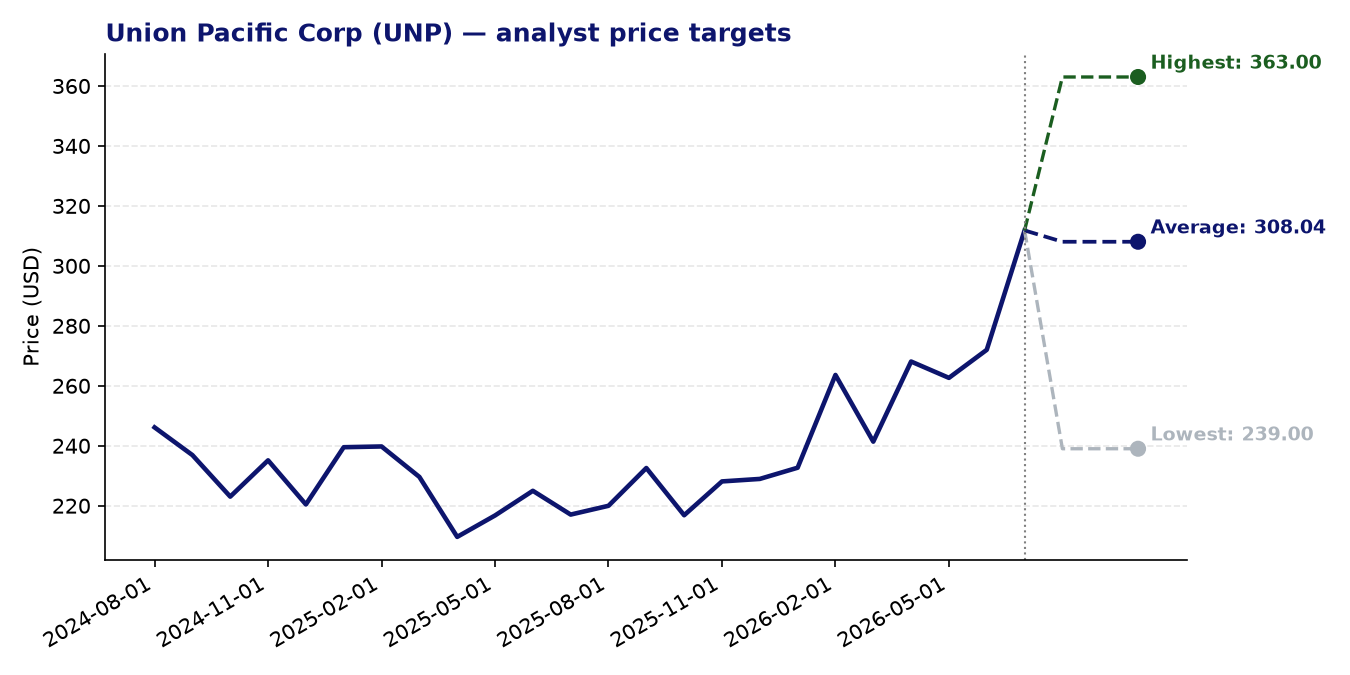
Union Pacific Corp (UNP) — current price: 311.83 USD | average price target: 308.04 USD | potential: -1.2%
About Union Pacific Corp
- Union Pacific Corporation, founded in 1862 and headquartered in Omaha, Nebraska, is one of the largest freight railroad operators in the United States, serving 23 western states.
- The company transports a broad range of commodities including agricultural products, coal, industrial chemicals, plastics, metals, petroleum, and finished automobiles.
- Its intermodal business moves merchandise in containers, connecting rail networks with broader supply chains across the US economy.
- Union Pacific serves a diverse customer base spanning grain processors, energy producers, manufacturers, and automotive companies.
Recent news
- Union Pacific delivered a stronger-than-expected second quarter, with revenue rising approximately 12% year-over-year and adjusted EPS of $3.41 coming in above the consensus estimate of $3.23.
- The company also reported meaningful improvement in its operating ratio during Q2, a key efficiency metric for railroad operators, alongside positive freight volume trends.
- Reports indicate that Union Pacific is engaged in discussions around a potential merger with Norfolk Southern, a development that could have significant strategic implications for the US rail industry.
- Net income for Q2 reached approximately $1.99 billion, or $3.36 per share on a reported basis, with the adjusted figure reflecting costs associated with merger and acquisition activity.
Strengths
- The Q2 earnings beat demonstrates improving operational momentum, with revenue growth of 12% and a better operating ratio signalling enhanced cost discipline.
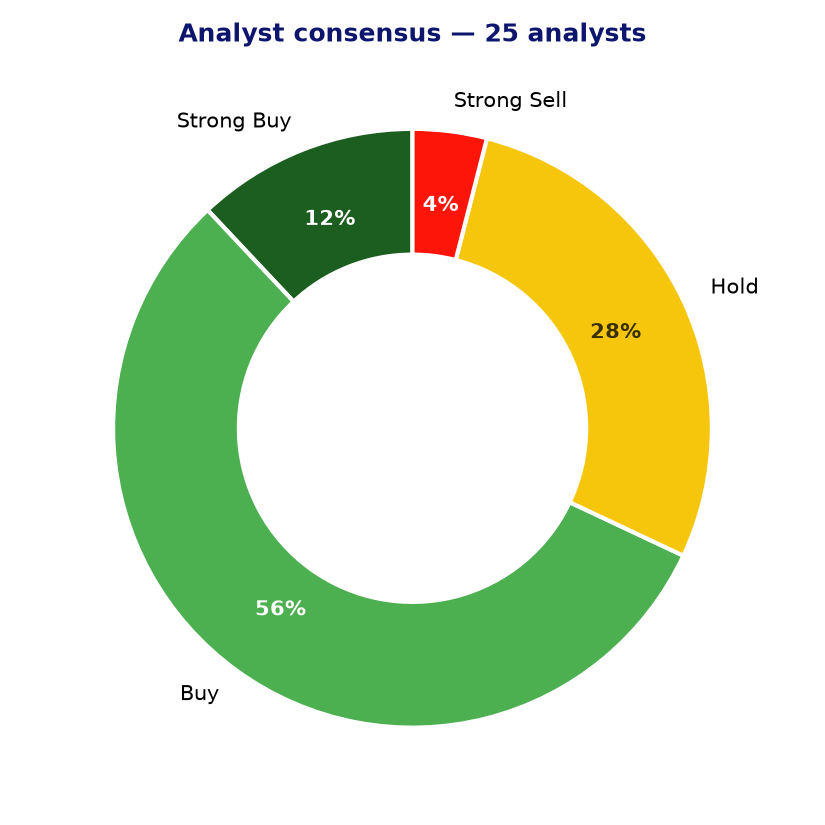
- Analyst sentiment is broadly constructive: 17 of 25 covering analysts rate the stock a buy or strong buy, with only one strong sell, reflecting confidence in the company’s long-term positioning.
- The 24-month Z-score momentum reading of 2.64 indicates that the stock has exhibited sustained relative price strength, a positive technical signal.
- Union Pacific’s diversified freight mix — spanning agriculture, energy, industrials, and automotive — provides meaningful revenue resilience across different economic cycles.
- The forward P/E of 22.46 represents a modest discount to the trailing P/E of 25.69, suggesting the market anticipates continued earnings progression over the near term.
Points of attention and risks
- At the current price of $311.83, the stock is trading modestly above the analyst consensus price target of $308.04, implying limited near-term upside on a consensus basis and leaving little margin for valuation error.
- The PEG ratio of 3.54 is elevated, indicating that the current valuation may not be well-supported by near-term earnings growth rates, with EPS growth of just 5% appearing modest relative to the multiple.
- The potential Norfolk Southern merger, while strategically interesting, introduces execution risk, regulatory uncertainty, and near-term cost drag, as reflected in the Q2 adjusted earnings.
- The railroad sector is sensitive to macroeconomic conditions, including industrial production levels, commodity prices, and trade volumes — factors that remain uncertain in the current environment.
- The wide spread between the lowest and highest analyst price targets ($239 to $363) reflects meaningful disagreement about the company’s prospects, highlighting the range of plausible outcomes for investors.
Analyst consensus and price targets
Conclusion
Union Pacific enters the second half of 2026 with solid operational momentum, a broad analyst buy consensus, and a convincing earnings beat that demonstrates its ability to improve efficiency while growing volumes. However, the stock is currently trading slightly above the consensus price target, the PEG ratio suggests a full valuation relative to near-term growth, and the potential Norfolk Southern merger adds a layer of strategic and regulatory uncertainty that warrants careful monitoring. Investors with a long-term horizon may find the franchise quality compelling, but those considering entry at current levels should weigh the limited consensus upside and elevated growth-adjusted valuation with care.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 23-07-2026. Not investment advice.