
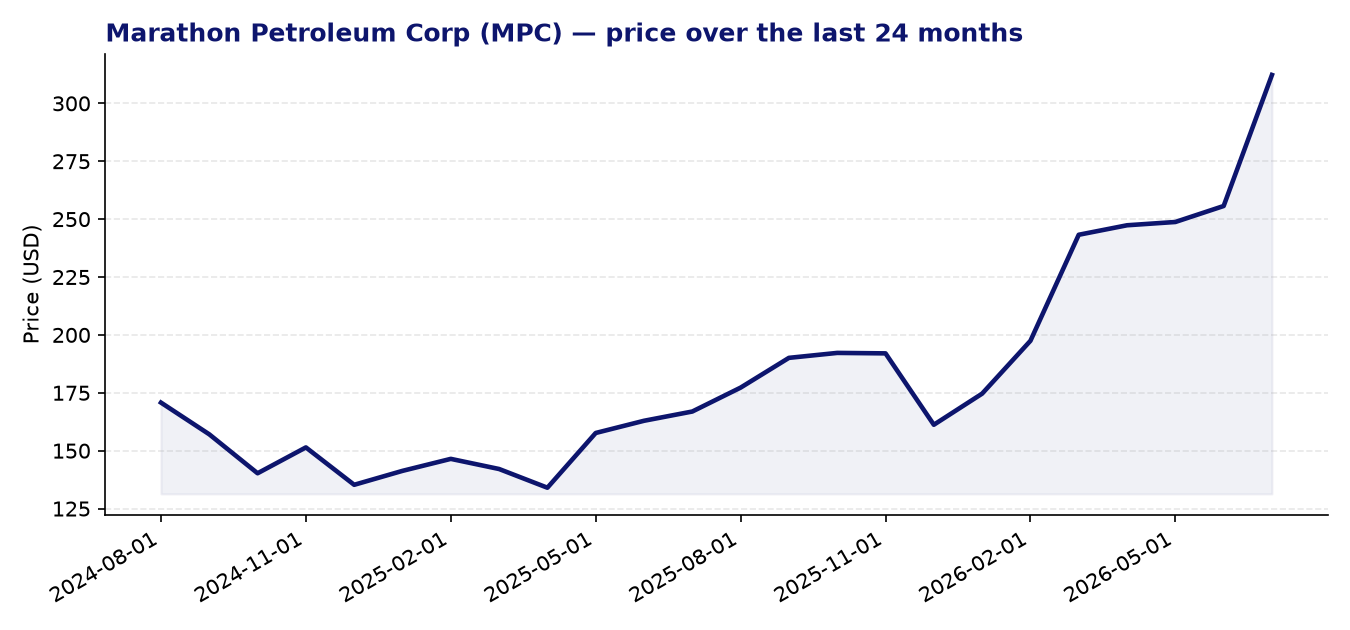
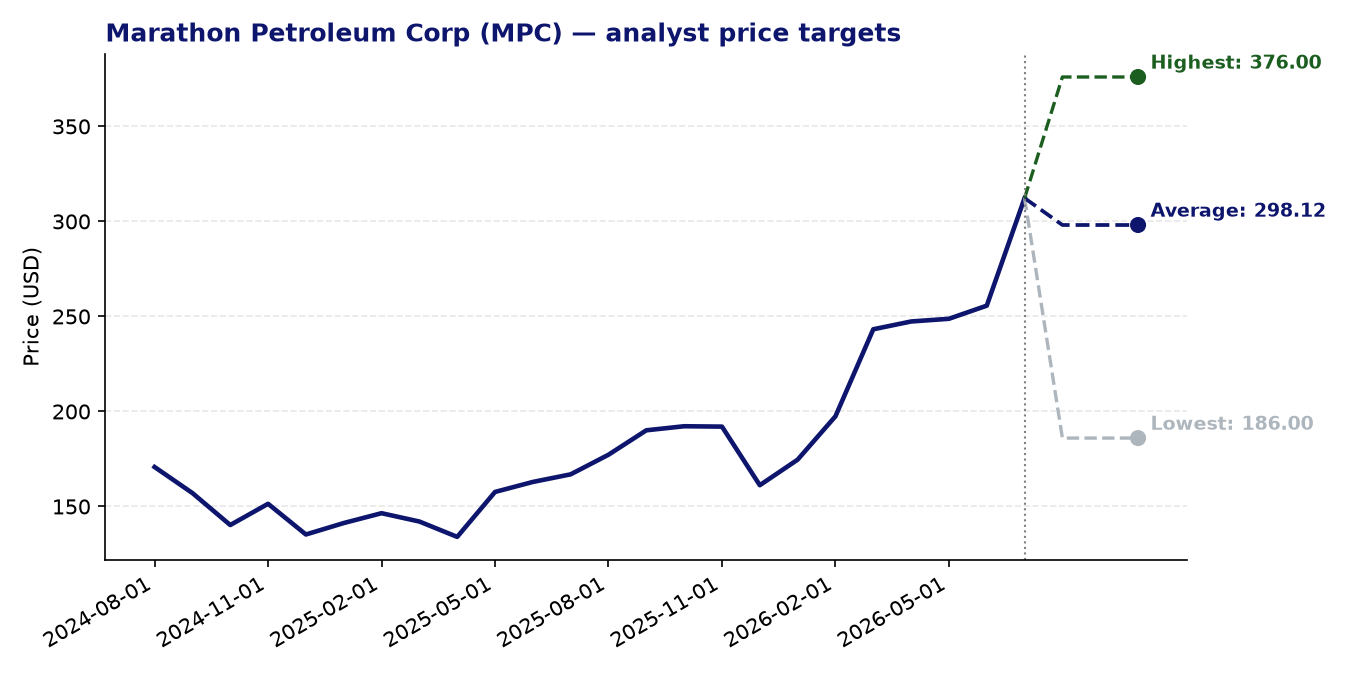
Marathon Petroleum Corp (MPC) — current price: 312.27 USD | average price target: 298.12 USD | potential: -4.5%
About Marathon Petroleum Corp
- Marathon Petroleum is one of the largest integrated downstream energy companies in the United States, operating the nation’s biggest refining system across Gulf Coast, Mid-Continent, and West Coast locations.
- Its Refining & Marketing segment processes crude oil and other feedstocks into transportation fuels, heavy fuel oil, asphalt, propane, and petrochemicals, distributing them under brands including Marathon and ARCO.
- The Midstream segment handles gathering, transportation, storage, and marketing of crude oil, refined products, natural gas, and natural gas liquids through an extensive network of pipelines, terminals, and marine assets.
- A dedicated Renewable Diesel segment processes renewable feedstocks into renewable diesel, sold to wholesale customers and direct dealers, reflecting the company’s measured move toward lower-carbon fuel production.
- Founded in 1887 and headquartered in Findlay, Ohio, Marathon Petroleum also holds a significant stake in MPLX LP, its publicly traded midstream partnership.
Recent news
- Zacks upgraded Marathon Petroleum to its top Strong Buy ranking in late May, citing a sustained upward trend in earnings estimate revisions as the primary driver.
- Morgan Stanley raised its price target on MPC from $233 to $265 in mid-June while reaffirming an Overweight rating, signalling continued institutional confidence in the company’s outlook.
- Ahead of its upcoming earnings release, commentary highlighted MPC’s position as operator of the largest U.S. refining system, with cash flow generation and refining margin trends identified as key variables to watch.
- Market observers have flagged mixed valuation signals for MPC, with cash flow strength viewed positively but current pricing prompting debate about whether the stock fully reflects near-term refining fundamentals.
Strengths
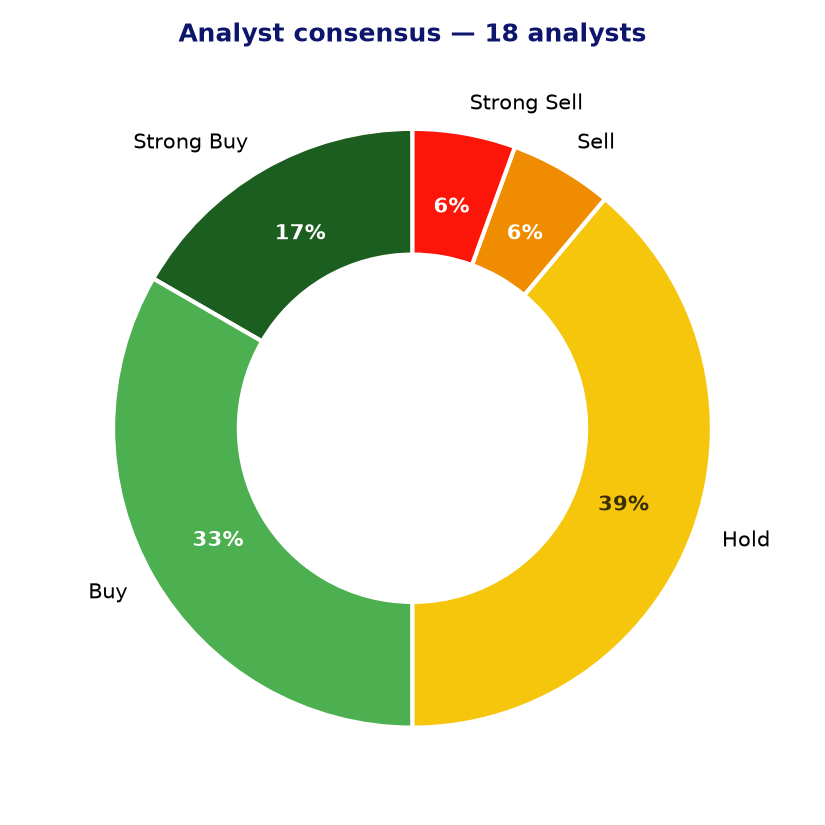
- Analyst sentiment leans constructive, with 9 out of 18 covering analysts carrying a buy or strong buy rating, and the Zacks Strong Buy upgrade reflecting positive earnings estimate momentum.
- The Forward P/E of 10.7x is meaningfully lower than the trailing P/E of 20.6x, suggesting the market anticipates a significant earnings recovery or improvement in refining margins over the next twelve months.
- A Z-score momentum reading of 2.23 over a 24-month window indicates that MPC’s price trend has been statistically strong relative to its own history, pointing to sustained investor interest.
- Marathon’s scale as the largest U.S. refiner provides operational leverage and cost advantages, while the midstream segment offers more stable, fee-based cash flows that partially offset the inherent cyclicality of refining.
- The renewable diesel segment positions the company to participate in growing demand for lower-carbon fuels without requiring a wholesale transformation of its existing asset base.
Points of attention and risks
- The current share price of $312.27 sits approximately 4.5% above the average analyst price target of $298.12, meaning the consensus view implies the stock is modestly ahead of fair value at current levels.
- The wide dispersion between the lowest ($186) and highest ($376) analyst price targets reflects genuine uncertainty about the earnings outlook, likely tied to volatile refining crack spreads and crude differentials.
- No near-term EPS growth is currently forecast, which, combined with a PEG ratio of 1.59, suggests the valuation is not especially cheap relative to expected growth on a standard earnings-growth basis.
- Refining margins are highly sensitive to macroeconomic conditions, crude oil price movements, and fuel demand trends — all factors outside management’s control and difficult to predict with confidence.
- The sell and strong sell ratings from two of the 18 analysts, alongside seven hold ratings, indicate that a meaningful portion of the analyst community sees limited upside or elevated risk at the current price level.
Analyst consensus and price targets
Conclusion
Marathon Petroleum combines the scale of the largest U.S. refining operation with a complementary midstream business and a developing renewable diesel segment, and its strong momentum score and low forward earnings multiple are genuine points of interest for value-oriented investors. That said, the stock currently trades above the average analyst price target, earnings growth visibility is limited, and the company’s profitability remains closely tied to refining margin cycles that are notoriously difficult to time. Investors with a view on the refining cycle and a tolerance for sector volatility may find MPC worth examining in depth, while those prioritising near-term earnings clarity may prefer to wait for a more attractive entry point.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 23-07-2026. Not investment advice.