
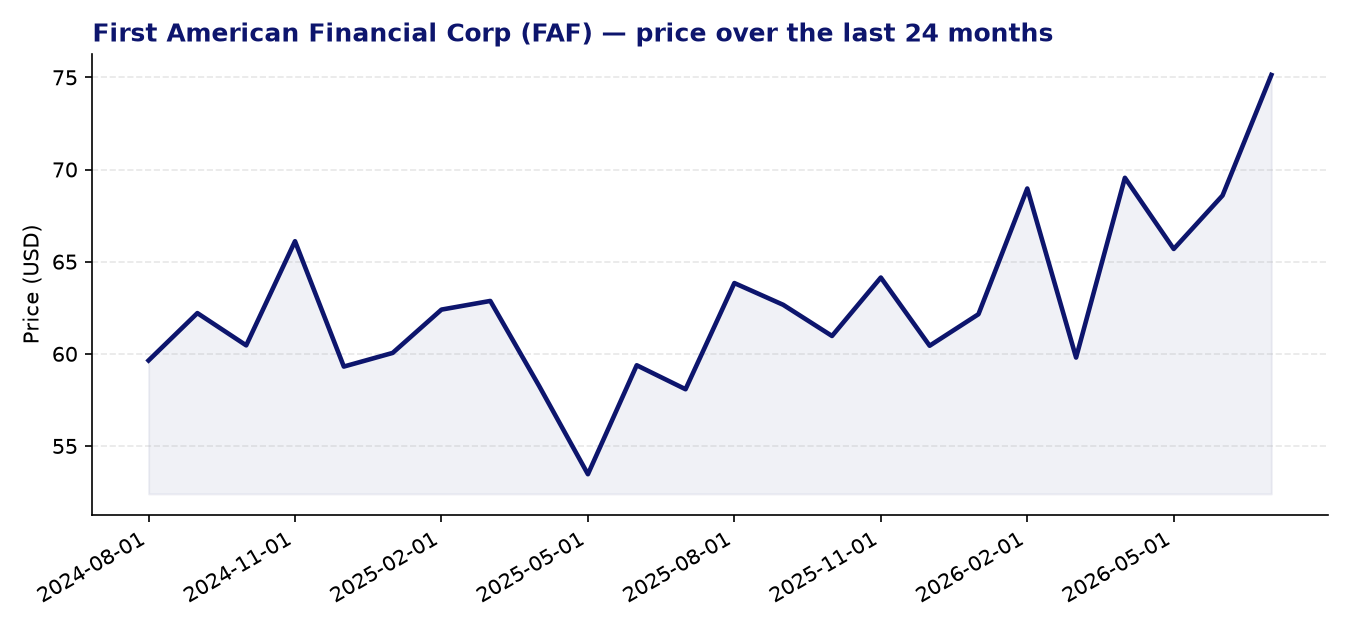
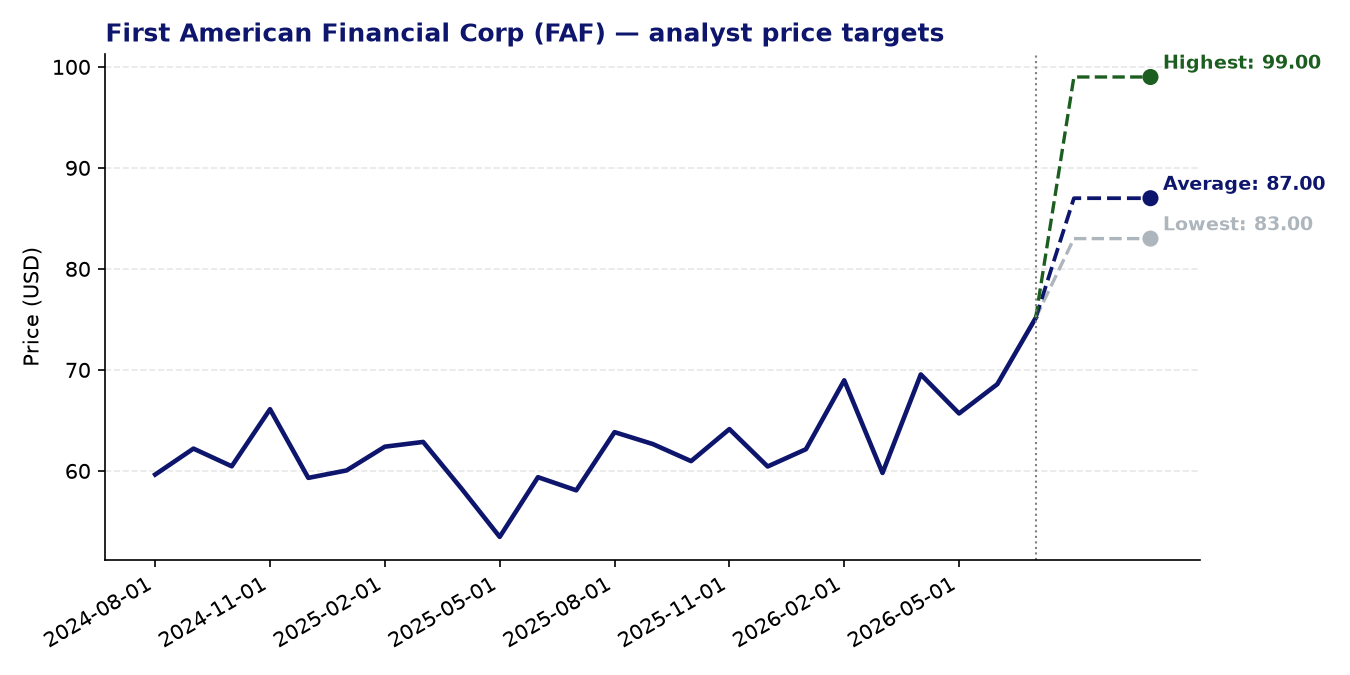
First American Financial Corp (FAF) — current price: 75.13 USD | average price target: 87.00 USD | potential: +15.8%
About First American Financial Corp
- First American Financial Corporation, founded in 1889 and headquartered in Santa Ana, California, is one of the largest providers of title insurance and settlement services in the United States.
- Its Title Insurance and Services segment issues policies on both residential and commercial property, and supports real estate transactions through escrow, closing, appraisal, and warehouse lending services across the US, Canada, the UK, Australia, and several other markets.
- The company also operates a Home Warranty segment, offering residential service contracts that cover heating, air conditioning, and appliance failures resulting from normal use.
- Additional capabilities include tax-deferred real estate exchanges, document generation, mortgage subservicing, and banking and wealth management services delivered through a mix of direct operations and agent networks.
Recent news
- Barclays analyst Terry Ma reaffirmed a Buy rating on FAF and set a price target of $83, citing confidence in the company’s outlook despite a subdued residential mortgage environment.
- First American’s second-quarter earnings came in stronger than expected, with growth in commercial title activity, rising investment income from deposit growth, and ongoing AI-related efficiency initiatives helping to compensate for weak residential purchase volumes.
- Multiple sources have highlighted FAF as a compelling value and income opportunity, pointing to its low earnings multiple and consistent dividend profile as distinguishing characteristics in the current market.
- A Seeking Alpha analysis reiterated a Buy view with a price target of $78–$80, noting that margin improvements driven by technology investment are supporting earnings resilience even as overall mortgage activity remains subdued.
Strengths
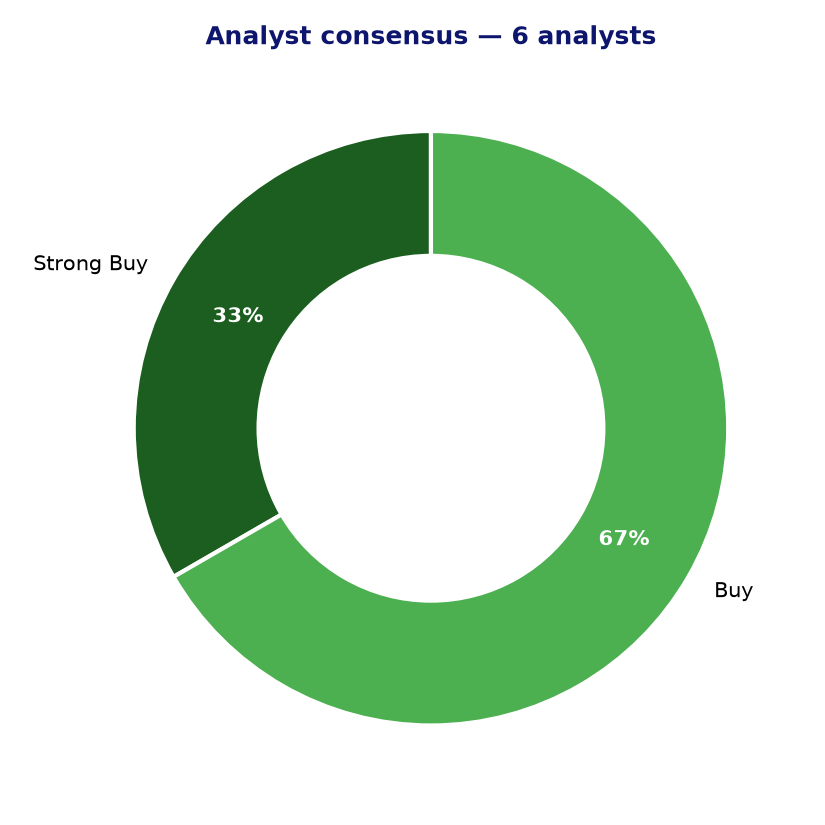
- Analyst sentiment is uniformly constructive: all six covering analysts rate FAF a Buy or Strong Buy, with an average price target of $87.00, implying approximately 15.8% upside from the current price of $75.13.
- The stock trades at a modest 10.42x trailing earnings and 10.14x forward earnings, suggesting the market is not pricing in a meaningful recovery in residential mortgage volumes — leaving room for positive surprises.
- A 24-month Z-score momentum reading of 2.42 indicates the shares have exhibited above-average relative price strength, a constructive technical signal.
- The commercial title segment is demonstrating tangible resilience, and management’s investment in artificial intelligence is beginning to generate margin improvements that partially offset the drag from slower residential activity.
- FAF has a long-established dividend track record, making it of potential interest to income-oriented investors seeking exposure to the real estate services value chain.
Points of attention and risks
- The PEG ratio of 2.98 is elevated relative to the low P/E, reflecting very modest near-term EPS growth of approximately 0.5% — meaning the valuation is not as undemanding on a growth-adjusted basis as the headline multiple implies.
- Residential mortgage origination volumes remain constrained by persistently high interest rates, and this segment is a core driver of FAF’s title insurance revenues; a prolonged higher-rate environment would continue to limit top-line recovery.
- Title insurance is inherently cyclical and closely tied to real estate transaction volumes, which exposes the company to downturns in housing activity that can be both sharp and difficult to predict.
- The lowest analyst price target of $83 sits only modestly above the current price, suggesting that even among bulls there is a range of views on how much near-term upside is available.
- The home warranty segment, while diversifying, operates in a competitive and margin-sensitive market, and its contribution to overall group earnings remains relatively limited.
Analyst consensus and price targets
Conclusion
First American Financial presents a picture of a well-established, modestly valued business navigating a challenging period for residential real estate, with commercial activity, investment income, and technology-driven efficiency providing meaningful offsets. The unanimous Buy consensus and double-digit price-target upside reflect genuine analyst conviction, though the limited near-term EPS growth and continued rate-related headwinds in residential mortgages are legitimate constraints on the pace of earnings recovery. Investors with a medium-term horizon and an interest in financial services exposure to an eventual housing market normalisation may find the current valuation worth examining carefully.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 24-07-2026. Not investment advice.