
Metlife Inc (MET) — current price: 94.83 USD | average price target: 97.75 USD | potential: +3.1%
About Metlife Inc
- MetLife is one of the world’s largest financial services groups, offering life insurance, annuities, employee benefits, and asset management across more than 40 countries.
- The company operates through six segments: Group Benefits, Retirement and Income Solutions, and four international divisions covering Asia, Latin America, EMEA, and its legacy MetLife Holdings unit.
- Its product range spans group and individual life, dental, disability, vision and pet insurance, as well as pension risk transfer, structured settlements, and a broad suite of annuity products.
- MetLife also serves institutional clients with funding agreements, longevity reinsurance, and capital markets investment products, and provides executive benefit financing through corporate-owned life insurance structures.
Recent news
- MetLife reaffirmed its dividend policy in mid-July 2026, keeping the stock in focus for income-oriented investors and prompting renewed discussion about its valuation relative to capital strength.
- The company issued a cautious update on variable investment income in late June 2026, signalling some near-term uncertainty in this revenue line, which is sensitive to equity market and private-asset conditions.
- UBS analyst Michael Ward maintained a Buy rating and a price target of $105 per share in early October 2026, implying meaningful upside from the then-prevailing share price of around $91.67.
- Ahead of its next quarterly earnings report, analyst commentary highlighted the stock’s strong 78% total return over a recent multi-year period, alongside an independent valuation estimate suggesting the shares could be materially undervalued on a fundamental basis.
Strengths
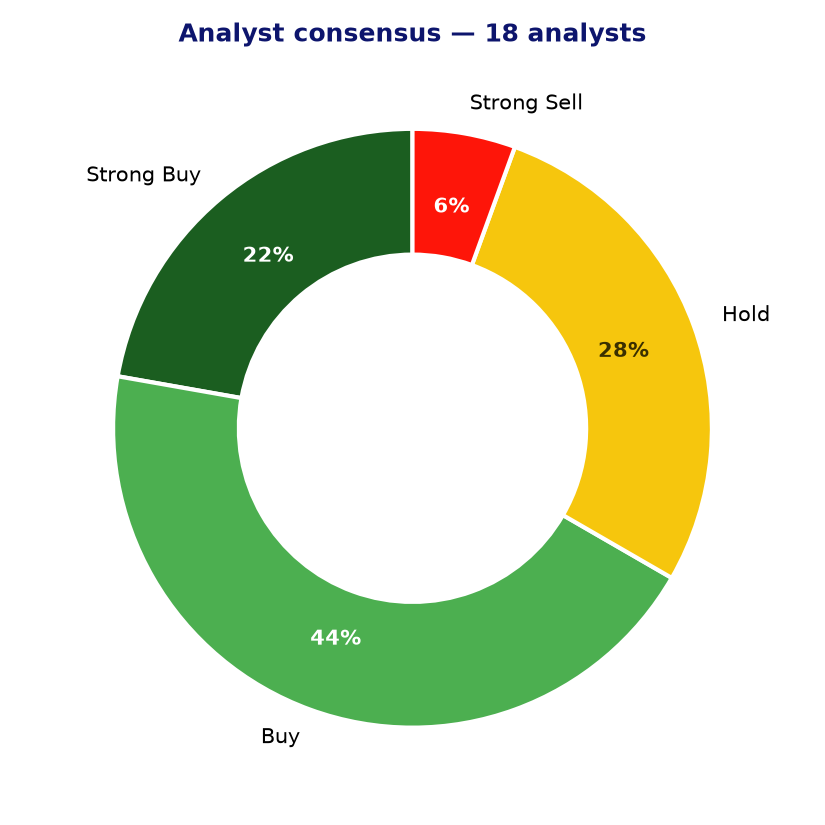
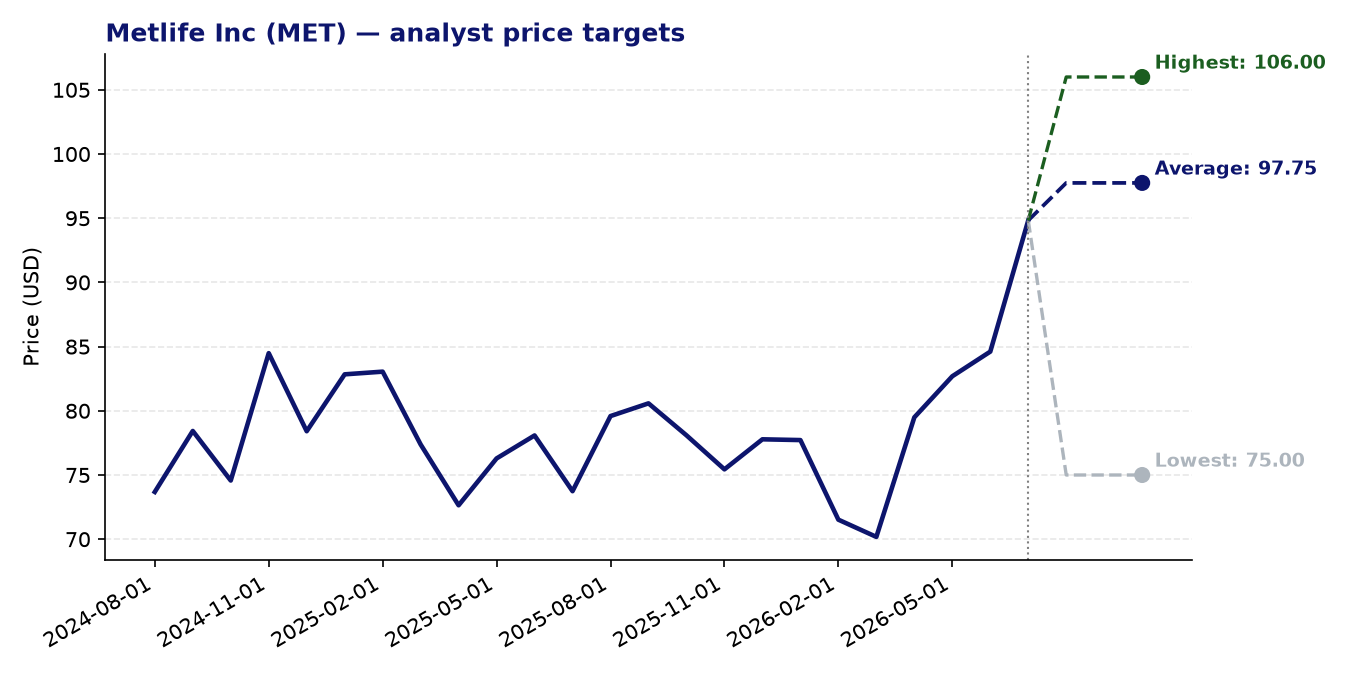
- The analyst community leans constructively on the stock: of 18 analysts covering MetLife, 12 rate it Buy or Strong Buy, with only one Strong Sell, and the consensus price target sits at $97.75.
- Valuation metrics appear attractive relative to earnings power: a forward P/E of 8.63x and a PEG ratio of 0.49 suggest the market may not be fully pricing in the company’s earnings growth trajectory.
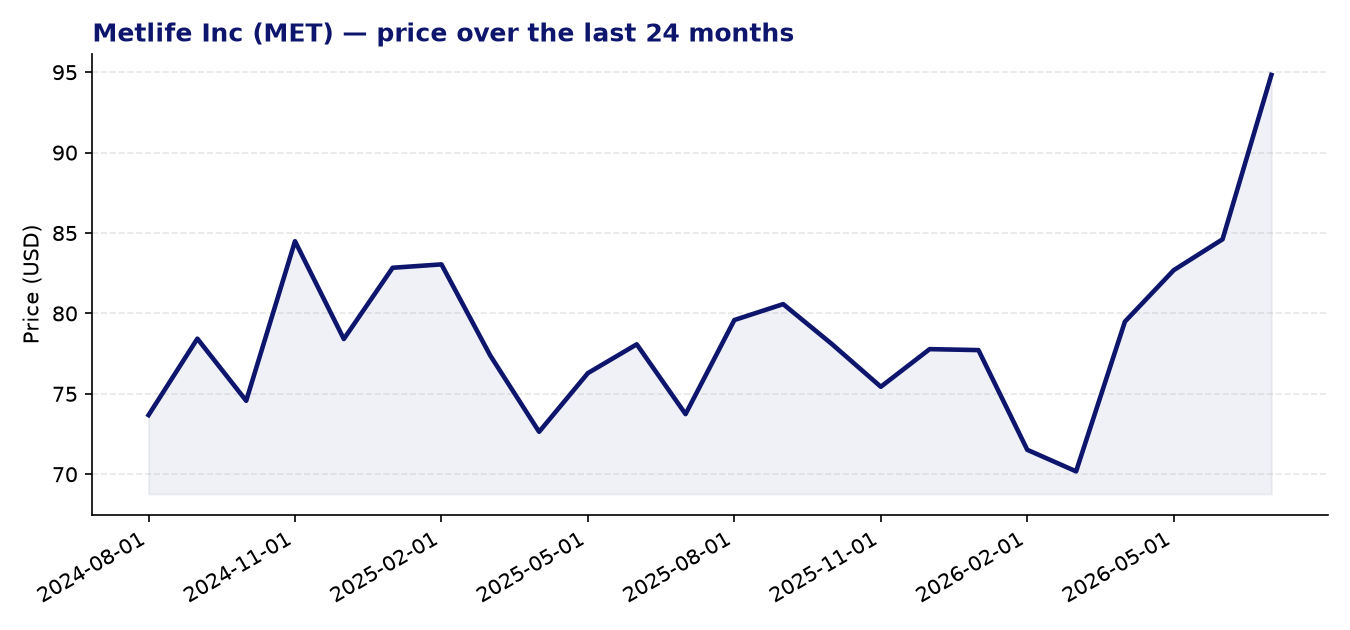
- The 24-month Z-score momentum reading of 2.39 indicates that the share price has exhibited notably positive relative strength over the period, reflecting sustained market confidence.
- MetLife’s diversified geographic and product footprint provides resilience across economic cycles, with the international segments offering exposure to structurally growing insurance markets in Asia and Latin America.
- A reaffirmed dividend policy underscores management’s confidence in capital generation, supporting the stock’s appeal for investors seeking a combination of income and potential capital appreciation.
Points of attention and risks
- The consensus average price target of $97.75 implies only about 3% upside from the current price of $94.83, limiting the near-term margin of safety for new investors even if analyst sentiment is broadly positive.
- The company’s own cautious update on variable investment income introduces uncertainty around a revenue line that can fluctuate materially with credit spreads, private equity valuations, and broader market conditions.
- The trailing P/E of 18.34x is considerably higher than the forward P/E of 8.63x, which may reflect one-off items or the market’s view that reported earnings do not fully represent normalised profitability — worth scrutiny ahead of the next results.
- As a large, globally active life insurer, MetLife carries structural sensitivity to prolonged low interest rates, which compress the spread earned on general account assets and can pressure margins in its Retirement and Income Solutions segment.
- The wide dispersion between the lowest ($75) and highest ($106) analyst price targets signals meaningful disagreement about fair value, reflecting genuine uncertainty around the pace and durability of earnings growth.
Analyst consensus and price targets
Conclusion
MetLife presents a mixed but broadly constructive picture: its diversified business model, favourable forward valuation multiples, and positive price momentum are notable strengths, and the majority of analysts maintain a constructive stance. However, the limited consensus upside to the current price, the cautionary note on variable investment income, and the inherent sensitivity of life insurers to interest rate and credit conditions mean that investors should weigh these factors carefully. The stock may suit those comfortable with insurance-sector dynamics who are attracted by its income credentials and international growth exposure, but the modest near-term upside implied by analyst targets warrants measured expectations.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 25-07-2026. Not investment advice.