
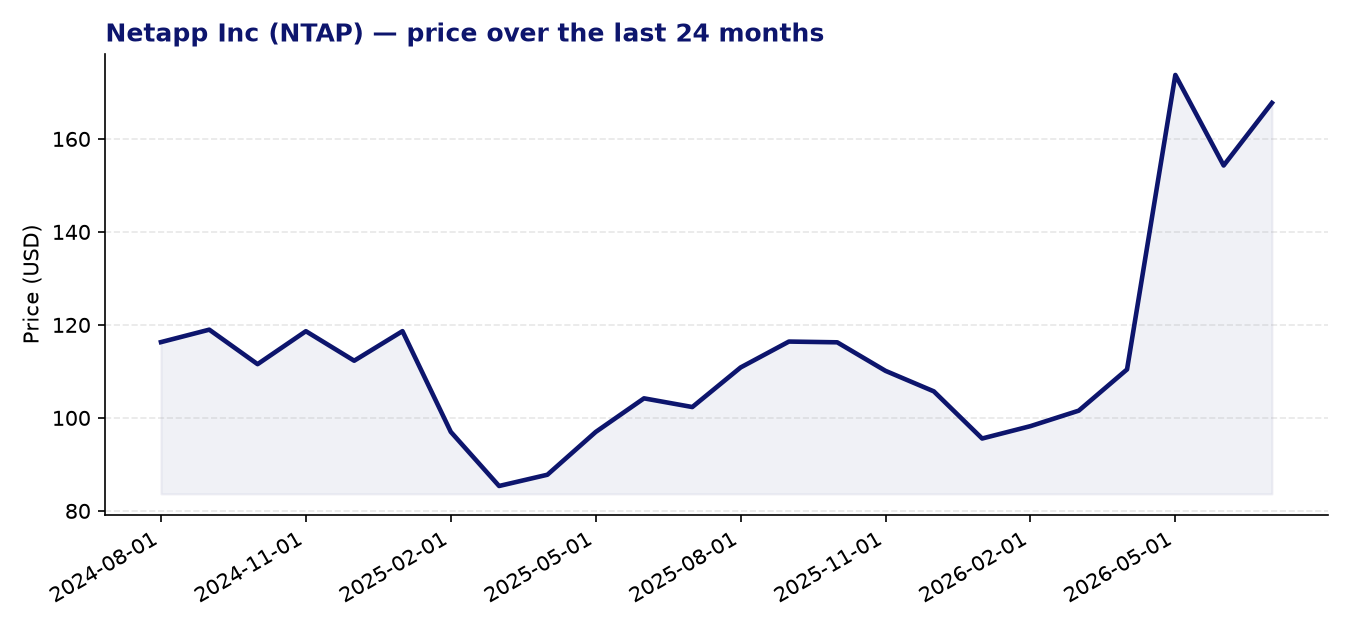
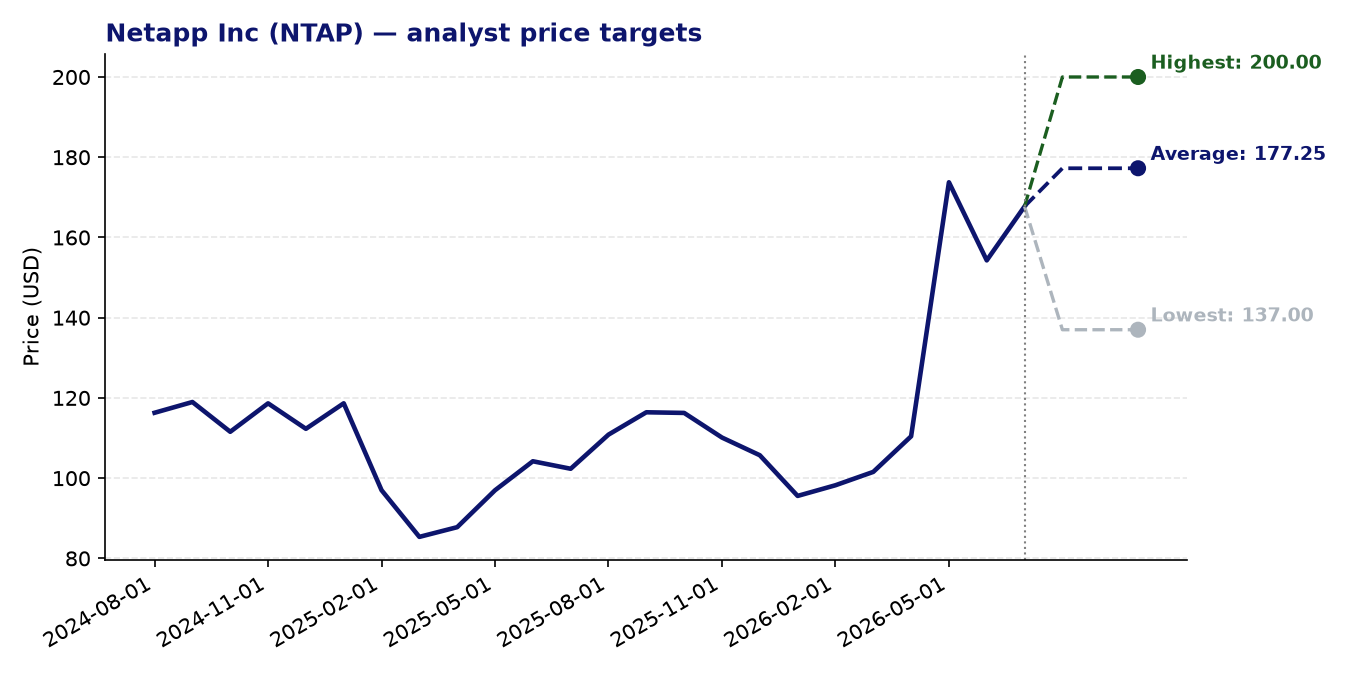
Netapp Inc (NTAP) — current price: 167.74 USD | average price target: 177.25 USD | potential: +5.7%
About Netapp Inc
- NetApp provides enterprise data infrastructure solutions spanning software, hardware systems, and cloud services, serving customers across North America, Europe, the Middle East, Africa, and Asia Pacific.
- Its two operating segments — Hybrid Cloud and Public Cloud — address both on-premises storage needs and cloud-native data management through partnerships with Microsoft Azure, AWS, and Google Cloud.
- The company’s flagship ONTAP data management software underpins a broad portfolio of storage products, including all-flash arrays and object storage systems designed for performance-intensive workloads.
- NetApp offers ransomware protection, data backup, disaster recovery, and professional services, positioning itself as an end-to-end data protection and cyber-resilience provider.
- A strategic alliance with Commvault Systems strengthens its enterprise data protection capabilities, while its Instaclustr platform extends its reach into managed open-source database services.
Recent news
- NetApp’s fiscal Q4 2026 earnings, released in late May, came in strongly ahead of expectations, triggering a share price gain of more than 26% in the weeks following the announcement.
- The stock has risen approximately 45% in 2026 to date, with analysts attributing much of the re-rating to accelerating demand for AI-related storage infrastructure and a notable improvement in revenue growth rates.
- NetApp’s CFO presented at the Evercore Global TMT Conference in early June, offering management’s perspective on the company’s positioning in the evolving enterprise AI and hybrid cloud landscape.
- Shares pulled back sharply in mid-July — falling over 7% in a single session — even as broader market indices moved higher, highlighting the stock’s sensitivity to profit-taking after its strong run.
Strengths
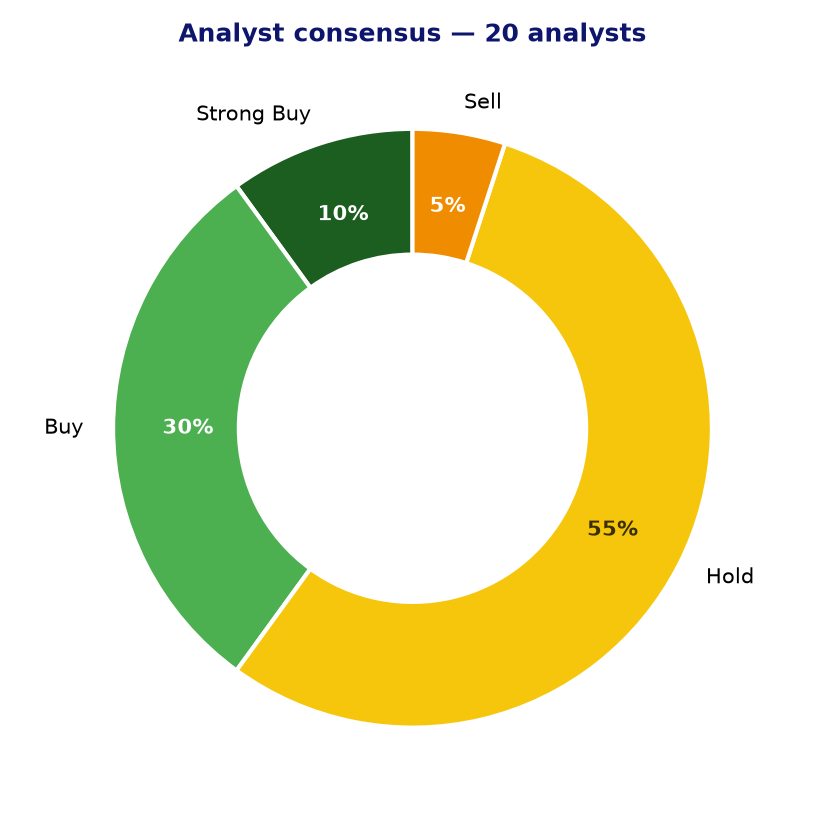
- The analyst consensus leans constructively, with 8 out of 20 covering analysts rating the stock a buy or strong buy, and the average price target of $177.25 implying modest further upside of around 5.7% from current levels.
- A Z-score momentum reading of 2.30 over the past 24 months indicates that the stock has exhibited meaningfully positive price momentum relative to its own history, consistent with the strong year-to-date performance.
- The forward P/E of 17.05 is notably lower than the trailing P/E of 26.37, suggesting the market is pricing in meaningful earnings growth ahead — a view supported by management’s commentary on AI-driven storage demand.
- NetApp’s broad integration with all three major hyperscalers (AWS, Azure, Google Cloud) gives it a relatively rare position as a cloud-agnostic infrastructure layer, reducing dependency on any single platform.
- The company’s expanding ransomware protection and cyber-resilience offering addresses one of enterprise IT’s most pressing priorities, providing a recurring revenue opportunity alongside its core storage business.
Points of attention and risks
- Following a gain of roughly 45% in 2026, much of the near-term good news may already be reflected in the share price; the consensus price target implies only about 5.7% additional upside from current levels.
- The trailing P/E of 26.37 and PEG ratio of 1.85 suggest the stock is not inexpensive on a historical or growth-adjusted basis, leaving limited margin of safety if earnings momentum were to disappoint.
- EPS growth of 0.19 (19%) is solid but not exceptional for a stock that has re-rated sharply upward; any slowdown in that trajectory could weigh disproportionately on the valuation.
- The mid-July single-day decline of over 7% in a rising market serves as a reminder of the stock’s vulnerability to sentiment shifts and profit-taking after an extended rally.
- Infrastructure spending by large enterprises remains sensitive to macroeconomic conditions and IT budget cycles; a broader slowdown in capital expenditure could temper the AI storage tailwind that has driven recent enthusiasm.
Analyst consensus and price targets
Conclusion
NetApp has undergone a meaningful re-rating in 2026, supported by stronger-than-expected earnings and a credible positioning in the AI infrastructure storage theme. The fundamentals are improving, the momentum is real, and the cloud-agnostic strategy offers genuine differentiation. That said, the share price already reflects a good deal of optimism, the near-term analyst price target implies limited upside from here, and valuation multiples leave the stock somewhat exposed to any earnings miss or shift in sentiment around enterprise AI spending.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 25-07-2026. Not investment advice.