
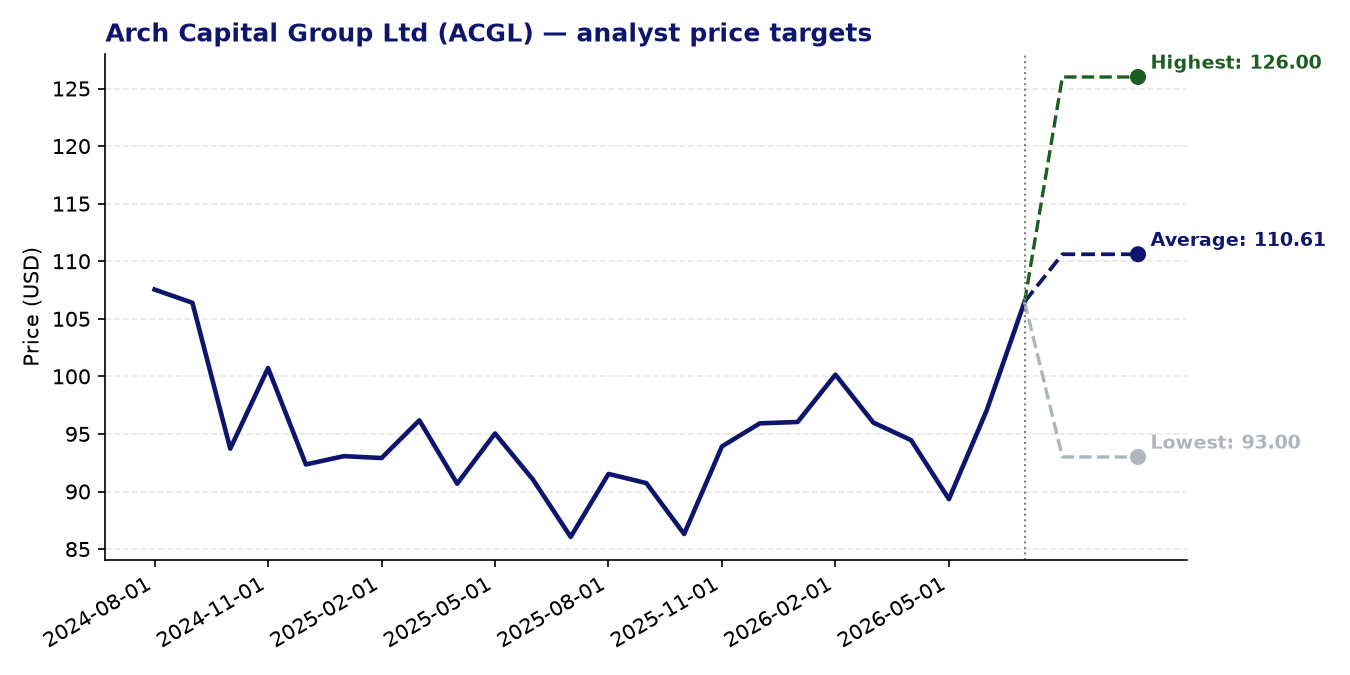
Arch Capital Group Ltd (ACGL) — current price: 106.48 USD | average price target: 110.61 USD | potential: +3.9%
About Arch Capital Group Ltd
- Arch Capital Group Ltd. is a Bermuda-headquartered specialty insurer and reinsurer operating across the United States, Canada, the UK, Europe, and Australia.
- The company’s three business segments — Insurance, Reinsurance, and Mortgage — cover a broad range of commercial and specialty risks, from property catastrophe reinsurance to professional liability.
- Its Mortgage segment is a notable differentiator, offering U.S. primary mortgage insurance predominantly on loans backed by Fannie Mae and Freddie Mac, alongside international mortgage insurance and credit-risk transfer business.
- Products are distributed through licensed independent retail and wholesale brokers, and the company serves both primary insurers and large institutional counterparties.
Recent news
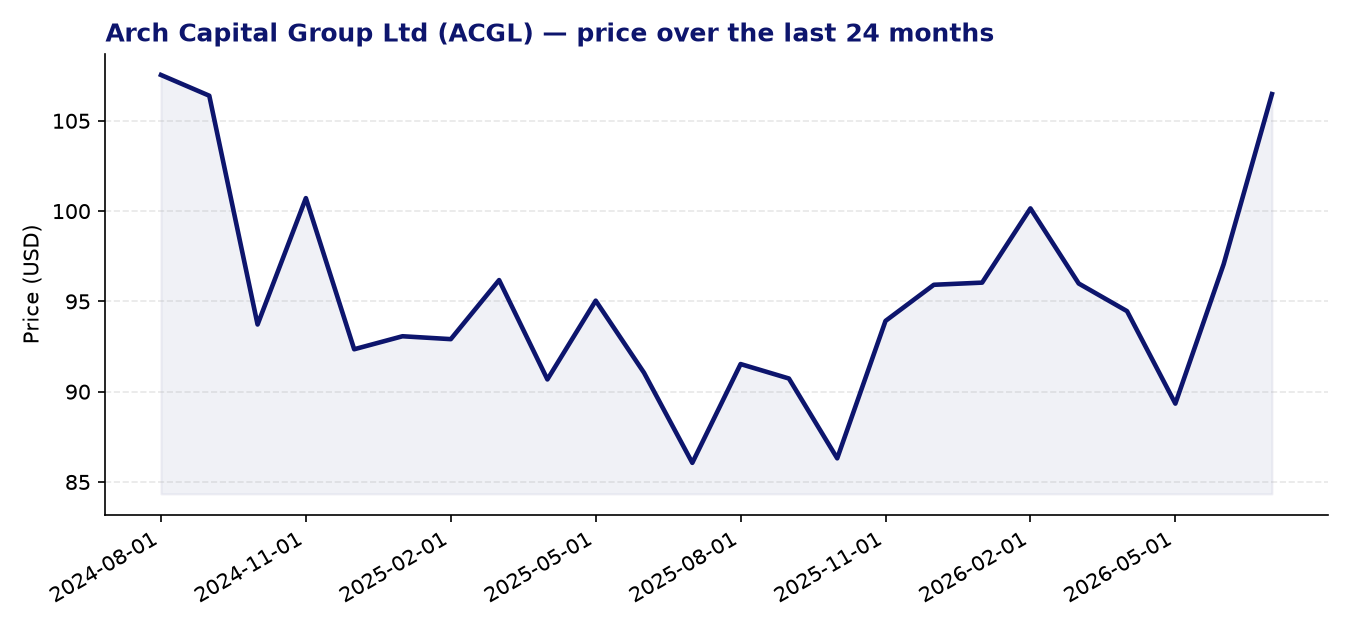
- On several occasions in June and early July 2026, ACGL closed higher on days when the broader S&P 500 declined, suggesting a degree of defensive resilience in the stock’s recent price behaviour.
- The stock has moved from around $92–$94 in mid-June to over $102 by early July, reflecting a meaningful near-term price appreciation ahead of its upcoming earnings report.
- An earnings preview published in mid-July flagged the forthcoming quarterly results as the next key event for investors, with the market capitalisation standing at approximately $35 billion going into the report.
Strengths
- ACGL trades on a trailing P/E of just 8.2x, which is notably modest for a diversified insurer with a track record of underwriting discipline, suggesting the shares are not aggressively priced relative to current earnings.
- A 24-month Z-score momentum reading of 2.51 indicates that the stock has exhibited sustained positive price momentum well above its historical average, a signal that has historically been associated with continued outperformance.
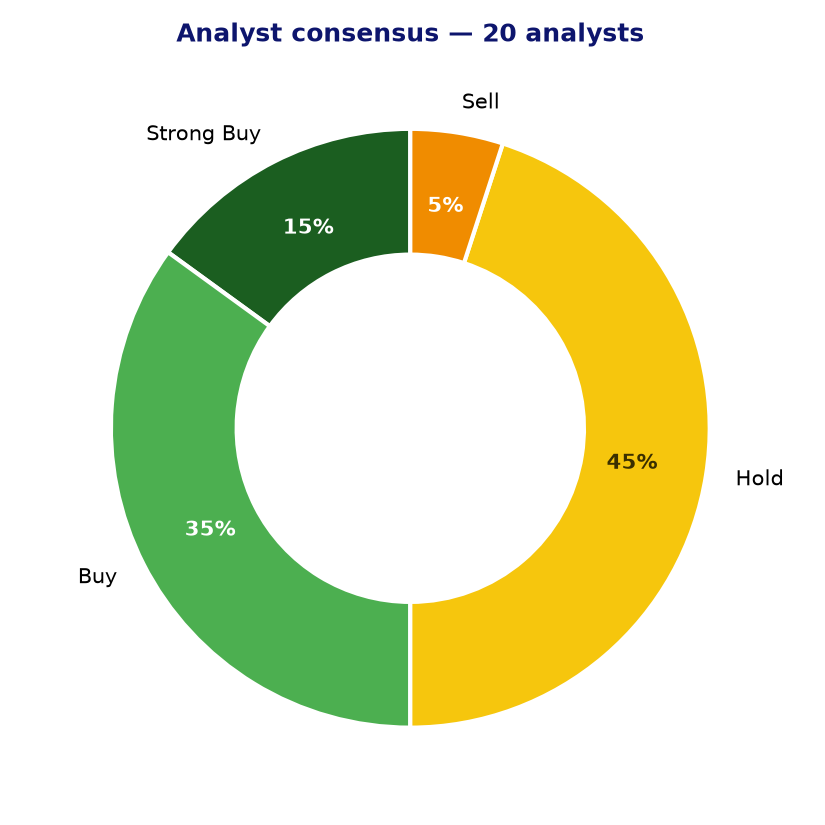
- The analyst community is broadly constructive: 10 of 20 covering analysts rate the stock a Buy or Strong Buy, and only one carries a Sell rating, reflecting general confidence in the business model.
- The PEG ratio of 1.05 implies the shares are roughly fairly valued relative to expected growth, leaving room for re-rating if earnings continue to progress.
- The company’s diversified mix of insurance, reinsurance, and mortgage products across multiple geographies provides meaningful earnings diversification relative to single-line peers.
Points of attention and risks
- The consensus average price target of $110.61 implies only around 3.9% upside from the current price of $106.48, which is a relatively slim margin and suggests limited near-term catalyst for further analyst-driven re-rating.
- Forward P/E of 10.86x is notably higher than the trailing P/E of 8.19x, implying analysts expect earnings to moderate or normalise — a potential headwind after a period of strong profitability.
- The Mortgage segment introduces exposure to U.S. housing market cycles and government-sponsored enterprise policy risk, which can become a source of elevated claims in a housing downturn.
- EPS growth of 0.82 (below 1.0) signals that near-term earnings growth is expected to be slow or potentially declining, which limits the investment case for growth-oriented investors.
- The wide range between the lowest ($93.00) and highest ($126.00) analyst price targets reflects meaningful disagreement about fair value and the earnings outlook, underlining uncertainty around the stock.
Analyst consensus and price targets
Conclusion
Arch Capital Group presents a profile of a well-diversified, conservatively priced insurer with solid momentum and a broadly supportive analyst consensus, though the near-term upside implied by price targets is modest and earnings growth appears set to slow from recent elevated levels. The mortgage segment adds an element of macro-sensitivity that warrants monitoring, particularly in the context of the U.S. housing market. Investors weighing ACGL will need to balance its attractive trailing valuation and defensive qualities against the prospect of earnings normalisation and limited short-term price target headroom.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 28-07-2026. Not investment advice.