
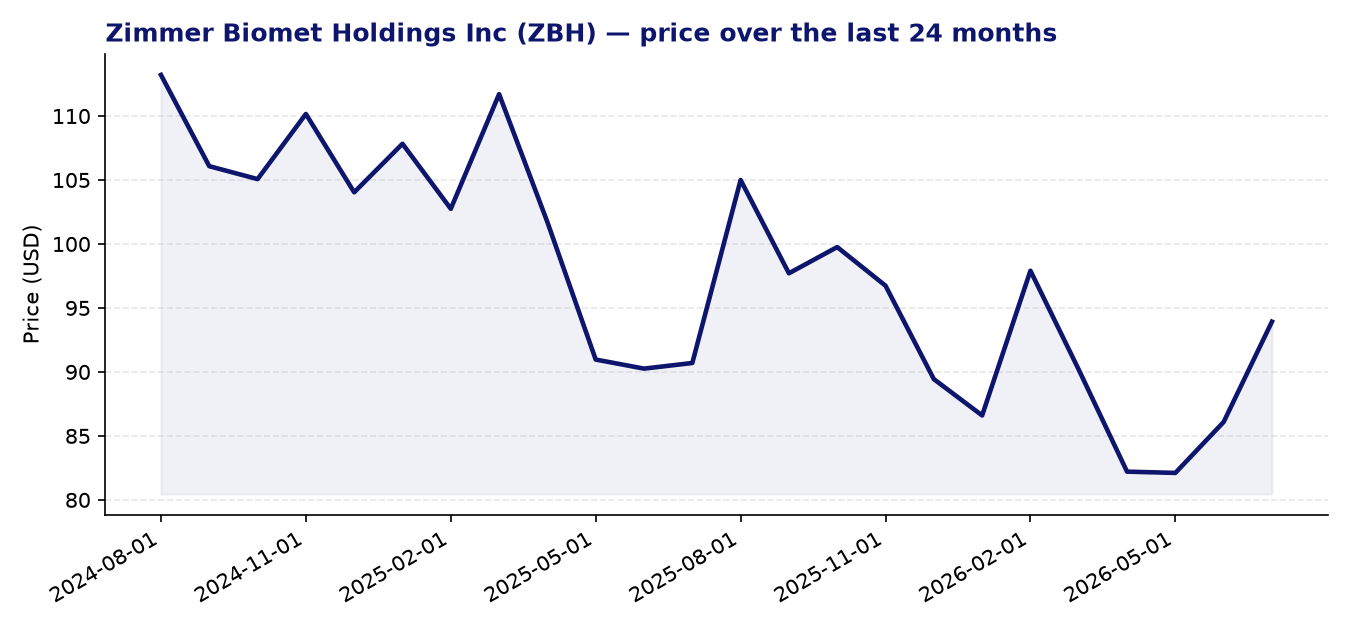
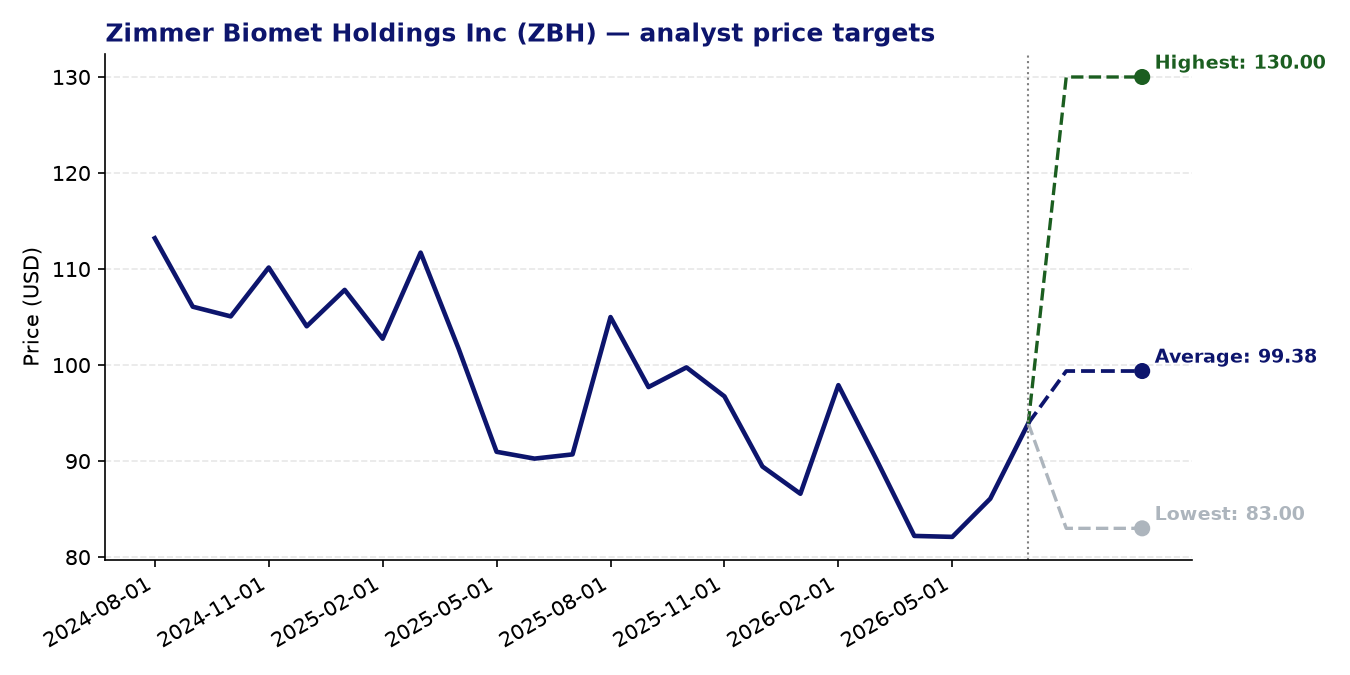
Zimmer Biomet Holdings Inc (ZBH) — current price: 93.93 USD | average price target: 99.38 USD | potential: +5.8%
About Zimmer Biomet Holdings Inc
- Zimmer Biomet, founded in 1927 and headquartered in Warsaw, Indiana, is a global medical technology company specialising in orthopedic reconstructive products, including knee and hip implants.
- The company also produces a broad range of S.E.T. products covering sports medicine, biologics, foot and ankle, upper extremities, and trauma, as well as craniomaxillofacial and thoracic solutions.
- Zimmer Biomet has invested significantly in digital and robotic surgery technologies, notably its ROSA Robot platform, which assists surgeons with implant positioning in knee arthroplasty procedures.
- Its ZBEdge platform integrates robotic and digital tools to capture pre-, intra-, and post-operative data, providing surgeons with actionable insights to support patient care decisions.
- The company serves a wide customer base including orthopedic and neurosurgeons, hospitals, healthcare institutions, and purchasing organisations across global markets.
Recent news
- Following its most recent earnings report, ZBH shares gained approximately 3% over the subsequent month, though this trailed the broader S&P 500’s performance over the same period.
- Canaccord Genuity trimmed its price target on ZBH from $93 to $83 in late April, reflecting some caution, though the stock has since traded above that revised target.
- Commentary from analysts highlights Zimmer Biomet’s ongoing strategic focus on People and Culture, Operational Excellence, and market execution as foundations for expected near-term growth.
- ZBH has been noted in market commentary as a potential long-term momentum play, with its robotic surgery capabilities drawing attention from investors seeking exposure to that theme.
Strengths
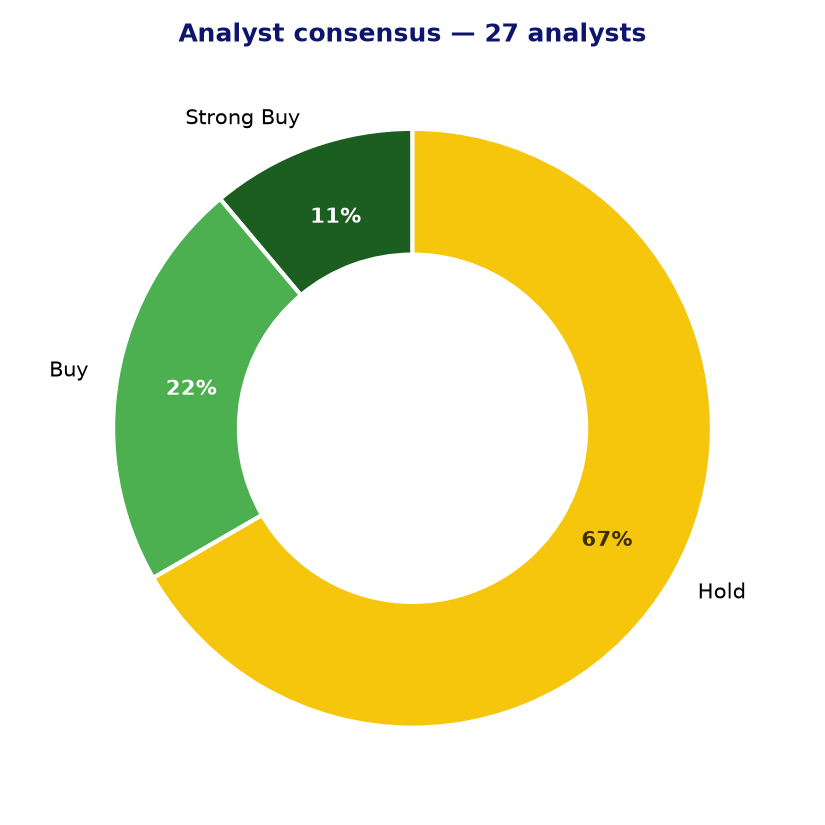
- The analyst consensus across 27 analysts leans constructive, with 9 buy or strong buy ratings and no sell recommendations, suggesting broadly stable institutional confidence in the name.
- The forward P/E of 10.43x is notably low relative to the trailing P/E of 24.33x, indicating that earnings are expected to grow substantially, a view supported by the PEG ratio of 0.69, which implies the stock may not be expensive relative to its growth profile.
- The 24-month Z-score momentum reading of 2.38 places ZBH in positive momentum territory, suggesting the stock has shown relative strength over a meaningful time horizon.
- The average analyst price target of $99.38 implies modest upside of around 5.8% from current levels, providing a reasonable near-term reference point.
- Zimmer Biomet’s expanding robotic and digital surgery ecosystem, particularly ROSA and ZBEdge, positions the company to participate in the longer-term shift toward technology-enabled orthopedic care.
Points of attention and risks
- The wide dispersion between the lowest ($83) and highest ($130) analyst price targets reflects meaningful disagreement about the company’s prospects, introducing uncertainty around the consensus view.
- With 18 of 27 analysts rating the stock a hold, conviction among the analyst community is relatively limited, and only 11% assign a strong buy rating.
- EPS growth of 0.31 on a trailing basis is modest, and investors should note that the compelling forward P/E relies heavily on future earnings delivery that has yet to be demonstrated.
- The orthopedic device sector faces ongoing pricing pressure from hospital purchasing organisations and healthcare cost-containment initiatives, which can weigh on margins over time.
- Canaccord’s recent price target reduction to $83 is a reminder that downside risk exists if execution or macro conditions disappoint, particularly given broader healthcare sector uncertainty.
Analyst consensus and price targets
Conclusion
Zimmer Biomet presents a mixed but broadly balanced picture: a well-established orthopedic franchise with credible digital and robotic surgery capabilities, trading at a valuation that appears undemanding on a forward earnings basis. The dominant hold consensus and limited analyst conviction suggest the market is waiting for clearer evidence of earnings acceleration before re-rating the stock. Investors with a longer time horizon and an interest in medical technology may find the current setup worth monitoring, though near-term catalysts remain modest and execution risk around forward earnings expectations deserves careful attention.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 31-07-2026. Not investment advice.