
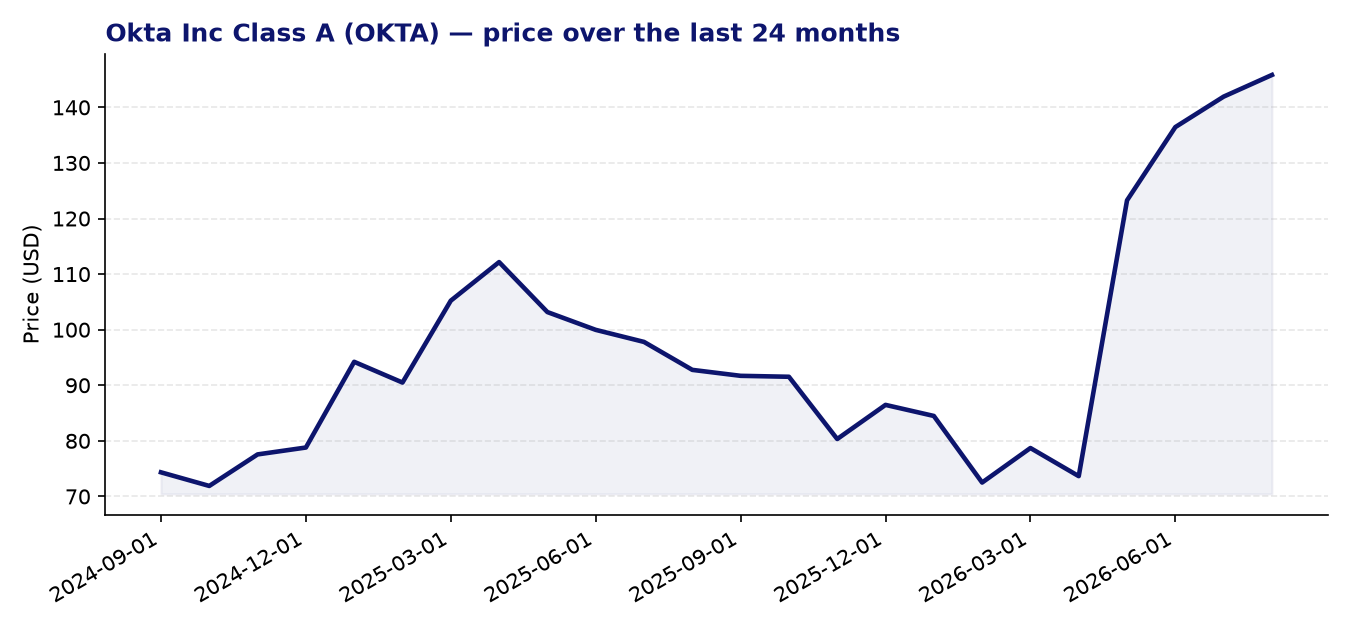
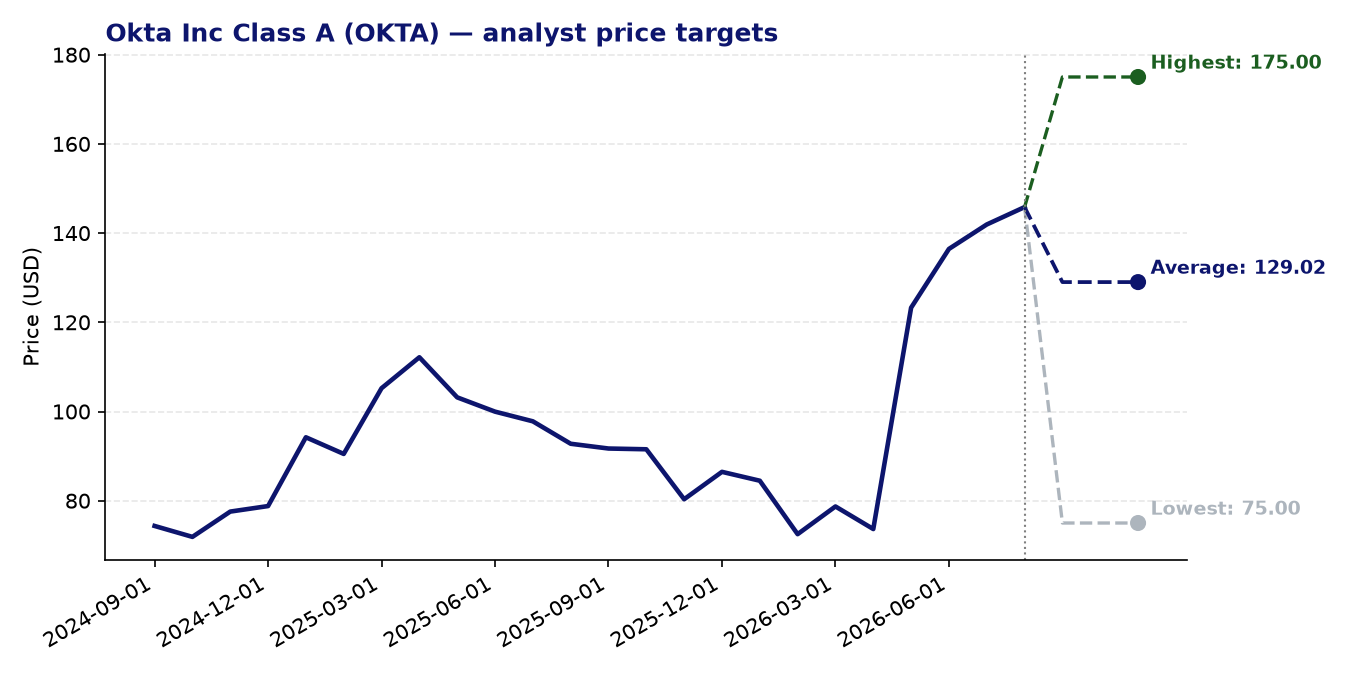
Okta Inc Class A (OKTA) — current price: 145.83 USD | average price target: 129.02 USD | potential: -11.5%
About Okta Inc Class A
- Okta is a leading identity and access management platform, helping organisations securely manage how users, devices, and applications authenticate and connect.
- Its core products include Single Sign-On, Adaptive Multi-Factor Authentication, and a Universal Directory, serving both cloud and hybrid IT environments.
- The company has expanded into AI-focused identity services, offering tools such as Okta for AI Agents and Auth0 for AI Agents to secure the growing ecosystem of autonomous AI applications.
- Okta also provides privileged access management, identity governance, and attack protection tools, positioning it as a broad identity security platform rather than a point solution.
- Founded in 2009 and headquartered in San Francisco, Okta serves a global customer base across the United States and international markets.
Recent news
- Okta has attracted elevated search interest among retail and institutional investors in recent months, reflecting broader market attention on the cybersecurity and identity space.
- At its 2026 annual general meeting, shareholders approved changes to the company’s equity compensation plan alongside the re-election of its governance slate, signalling routine but stable corporate housekeeping.
- No major earnings releases, product announcements, or analyst rating changes featuring substantive detail were available in the recent news cycle, limiting near-term catalysts from the news flow alone.
Strengths
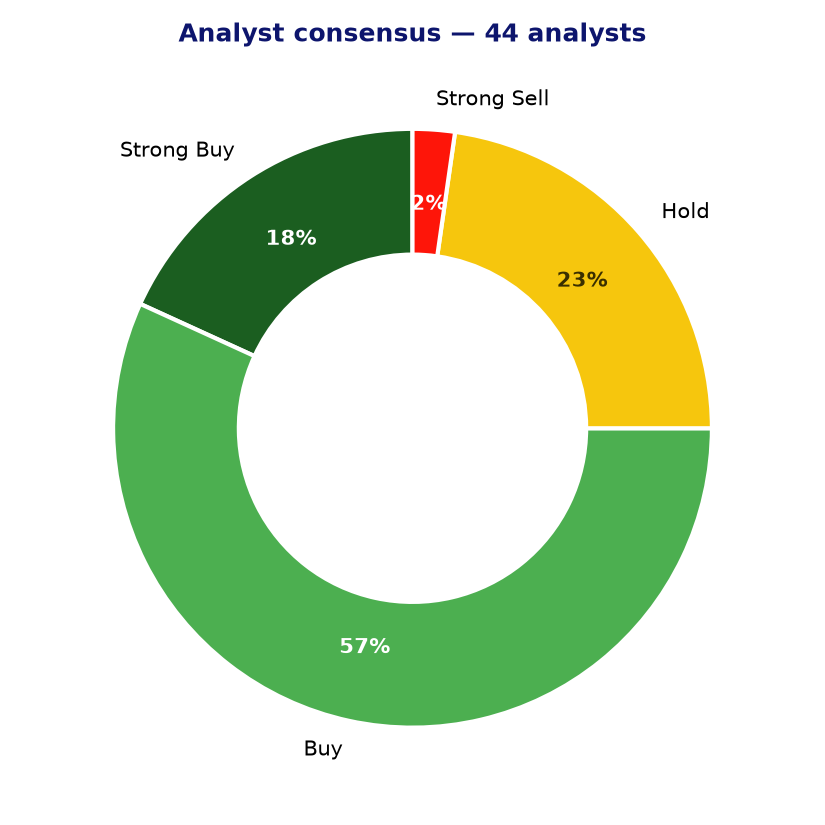
- Analyst coverage is broad and broadly constructive: of 44 analysts covering the stock, 33 rate it a buy or strong buy, with only one strong sell, suggesting a solid consensus on the company’s competitive position.
- The forward P/E of 34x is considerably more measured than the trailing P/E of 105x, implying that earnings are expected to grow meaningfully and that current profitability understates the company’s trajectory.
- A PEG ratio of 1.35 suggests the market is not pricing in excessive growth expectations relative to earnings momentum, which may indicate a more reasonable entry point than headline multiples imply.
- The 24-month Z-score momentum reading of 2.39 indicates that the stock has exhibited strong relative price performance over the medium term, consistent with improving business fundamentals.
- Okta’s early move into AI agent identity management is a credible strategic extension, as securing non-human identities is an emerging and under-addressed challenge across enterprise IT.
Points of attention and risks
- The average analyst price target of approximately 129 USD sits roughly 11.5% below the current trading price of 145.83 USD, suggesting the stock may already reflect, or slightly exceed, consensus fair value estimates.
- The trailing P/E of over 105x remains elevated, and any disappointment in earnings growth could lead to a meaningful re-rating, given how much future improvement is already embedded in the valuation.
- EPS growth of 0.19 on a trailing basis is modest, and Okta will need to demonstrate a sustained and significant acceleration in profitability to justify current market expectations.
- The identity and access management market is increasingly competitive, with Microsoft, CrowdStrike, and other large vendors expanding into adjacent identity services, which could pressure Okta’s pricing power and win rates.
- The wide spread between the lowest (75 USD) and highest (175 USD) analyst price targets reflects genuine uncertainty about the company’s long-term earnings power, indicating that outcomes remain difficult to predict with confidence.
Analyst consensus and price targets
Conclusion
Okta occupies a defensible and strategically important position in enterprise identity security, with a large and constructive analyst following and a credible roadmap into AI-era identity challenges. However, the stock currently trades above the average analyst price target, and its valuation still demands substantial earnings growth to be sustained over time. Investors may wish to weigh the company’s structural growth opportunity in identity management against the near-term price-to-target gap and the competitive pressures from larger technology platforms encroaching on its market.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 03-08-2026. Not investment advice.