
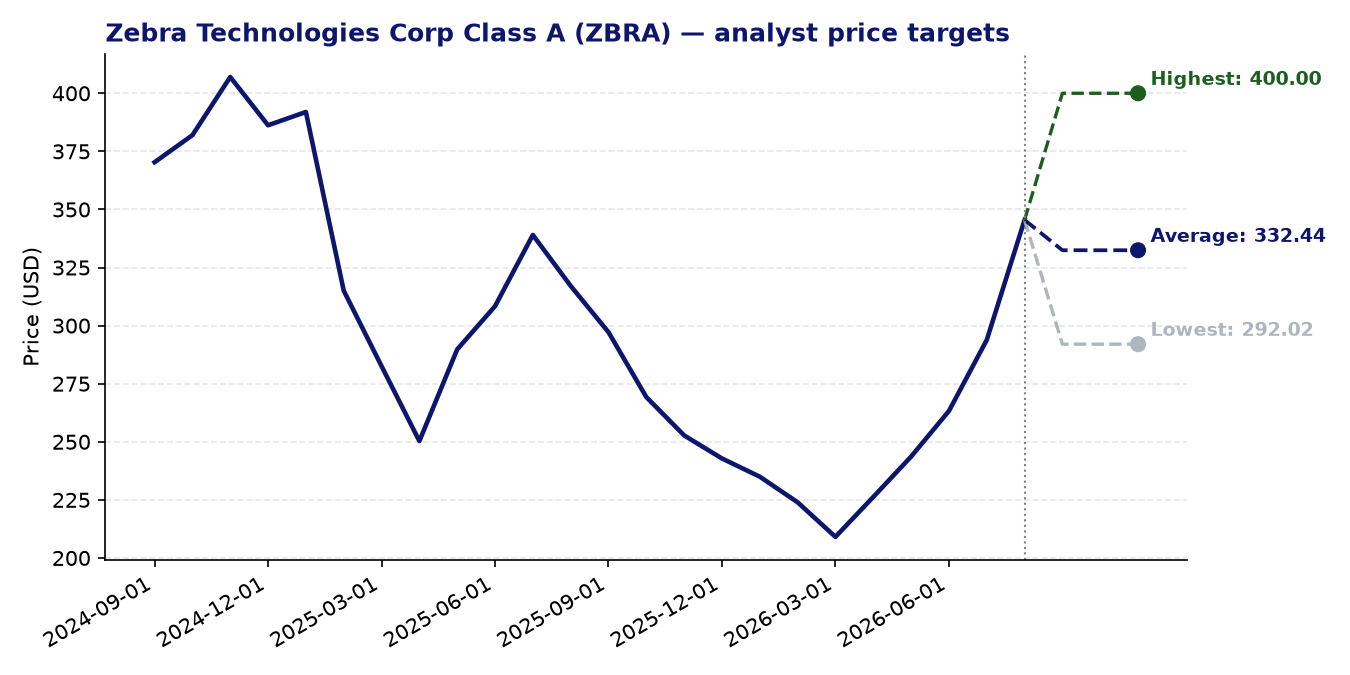
Zebra Technologies Corp Class A (ZBRA) — current price: 345.47 USD | average price target: 332.44 USD | potential: -3.8%
About Zebra Technologies Corp Class A
- Zebra Technologies, founded in 1969 and headquartered in Lincolnshire, Illinois, is a global provider of automatic identification and data capture (AIDC) solutions, serving industries including retail, manufacturing, healthcare, and transportation and logistics.
- The company operates through two segments — Connected Frontline and Asset Visibility and Automation — offering hardware ranging from barcode scanners and RFID printers to rugged mobile computers and industrial machine vision cameras.
- Zebra also provides a broad suite of software and services, including workflow optimization, workforce management, prescriptive analytics, cloud-based platforms, and real-time location systems.
- Its products and solutions are sold through a direct sales force and an extensive network of channel partners worldwide.
Recent news
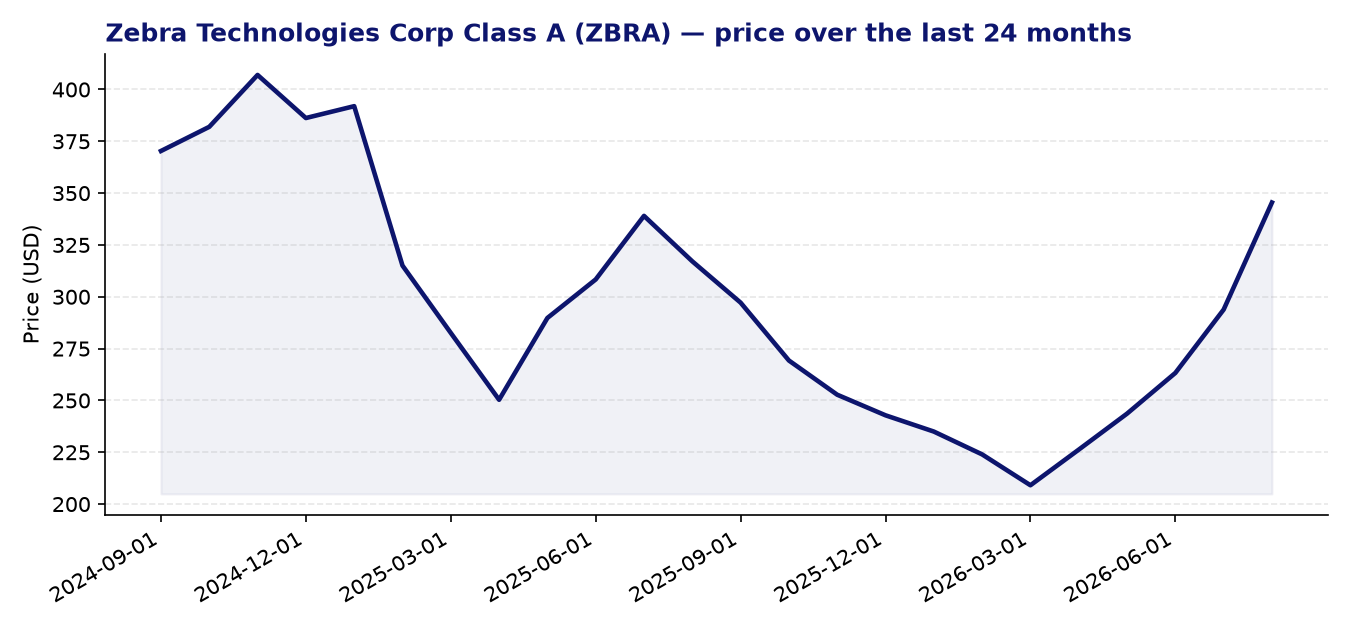
- Zebra shares experienced notable volatility over recent months, including a sharp single-day decline of approximately 7.4% in early October 2026, significantly underperforming broader market moves on that session.
- On several other trading days the stock outpaced its peers to the upside, suggesting episodic swings rather than a consistent directional trend.
- The recent price action across these sessions reflects heightened sensitivity to broader market sentiment, with moves in both directions exceeding index-level returns.
Strengths
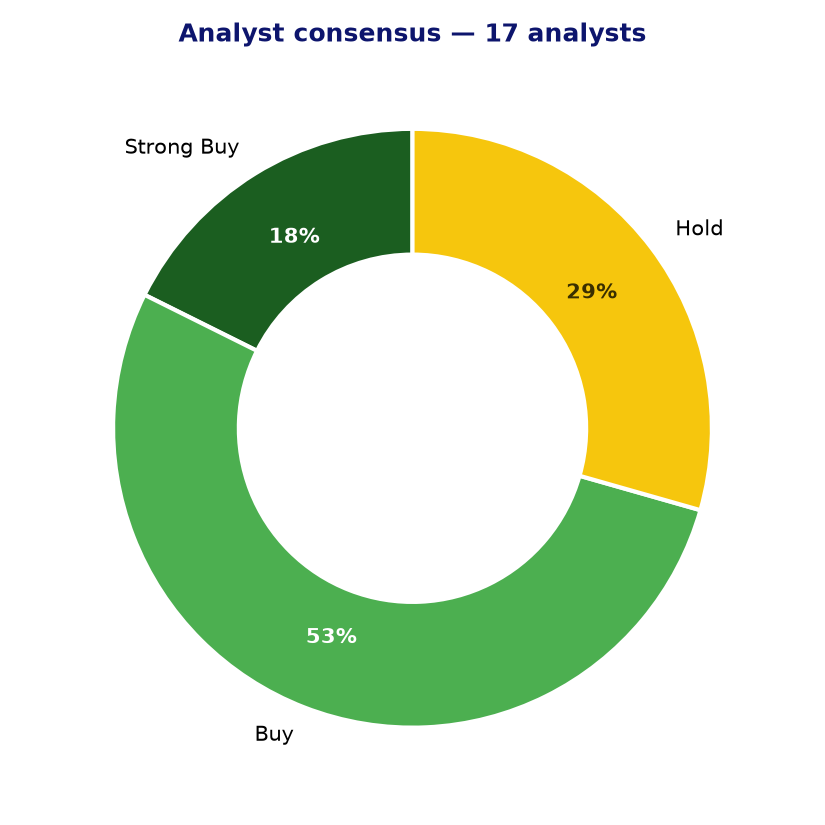
- Analyst sentiment is broadly constructive: of 17 covering analysts, 12 carry a buy or strong buy rating, with no sell recommendations on record.
- The forward P/E of 16.68 looks materially more modest than the trailing P/E of 42.03, suggesting analysts expect a meaningful recovery in earnings over the near term.
- A PEG ratio of 0.63 implies the stock may be reasonably valued relative to its expected earnings growth, often considered a signal of potential undervaluation on a growth-adjusted basis.
- The 24-month Z-score momentum reading of 2.87 indicates that price momentum has been notably positive relative to its own historical trend, reflecting sustained investor interest over the medium term.
- The highest analyst price target stands at $400.00, indicating that more bullish forecasters see meaningful upside from current levels, even if consensus is modestly below the current price.
Points of attention and risks
- The consensus price target of $332.44 sits roughly 3.8% below the current market price of $345.47, suggesting that the average analyst view implies limited near-term upside at prevailing levels.
- The trailing P/E of 42.03 is elevated for a hardware and equipment-focused business, leaving limited margin for error if earnings recovery takes longer than the market anticipates.
- Near-zero EPS growth (-0.01) in the most recent period highlights that the earnings rebound embedded in the forward P/E is not yet materialising, introducing execution risk.
- Zebra operates in cyclical end-markets such as manufacturing, retail, and logistics, which are sensitive to capital expenditure cycles and broader economic slowdowns.
- Ongoing tariff and supply-chain pressures affecting hardware manufacturers, combined with competitive dynamics in the AIDC and enterprise mobility space, represent structural risks to both margins and revenue growth.
Analyst consensus and price targets
Conclusion
Zebra Technologies presents a mixed but reasonably balanced investment case: a supportive analyst consensus, an attractive PEG ratio, and solid medium-term price momentum sit alongside a consensus price target that implies the stock is modestly ahead of itself at current levels. The anticipated earnings recovery built into the forward multiple has yet to fully show up in reported results, which warrants monitoring over the coming quarters. Investors with a longer horizon and comfort with hardware-sector cyclicality may find the growth-adjusted valuation compelling, but near-term risk-reward appears more finely balanced than the headline analyst ratings might suggest.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 04-08-2026. Not investment advice.