
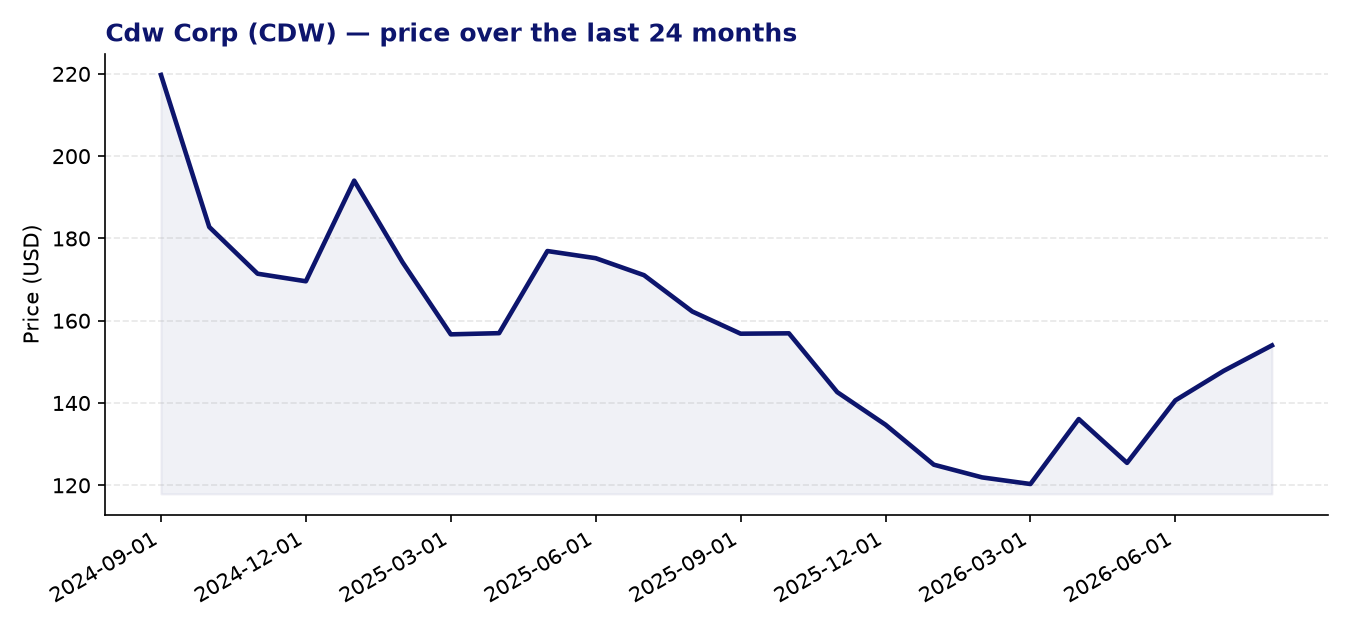
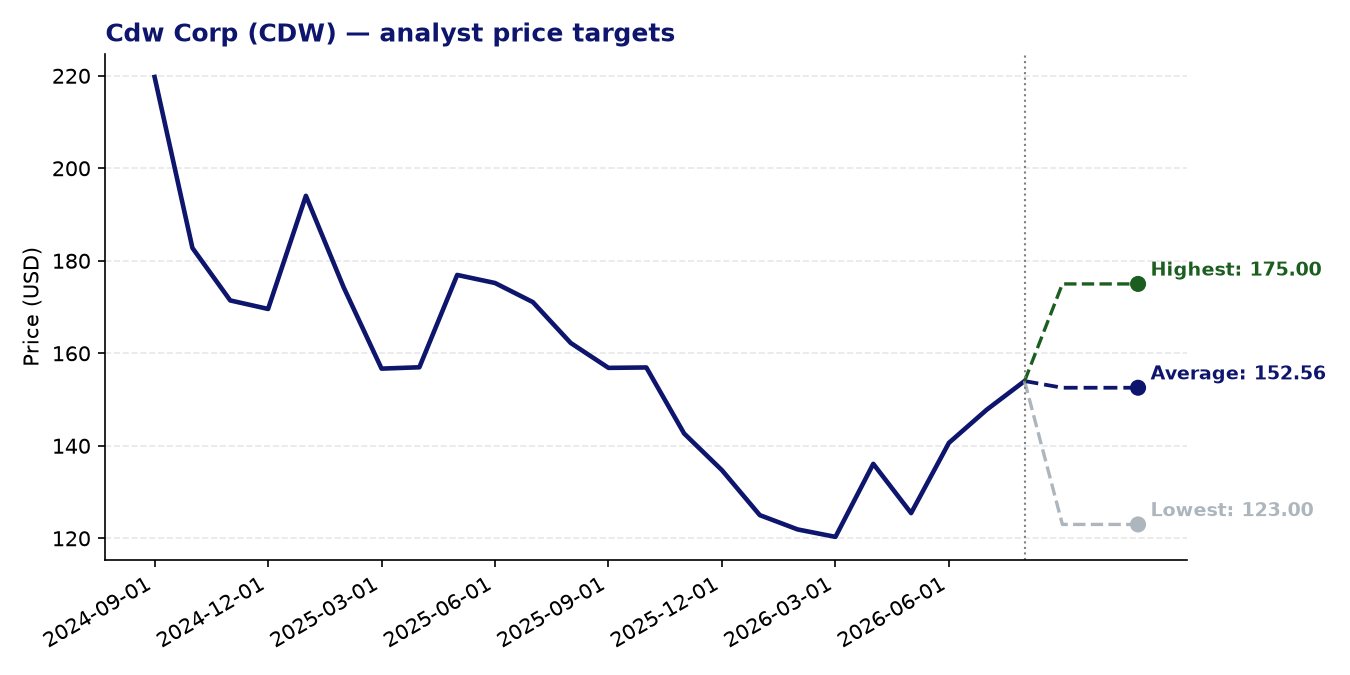
Cdw Corp (CDW) — current price: 154.00 USD | average price target: 152.56 USD | potential: -0.9%
About Cdw Corp
- CDW Corporation is a US-based IT solutions provider founded in 1984, serving customers in the United States, United Kingdom, and Canada.
- The company operates across three segments — Commercial, Government, and Education — serving business, government, healthcare, and education clients.
- CDW offers a broad portfolio spanning hardware (notebooks, servers, network equipment, storage) and software (cloud, security, virtualization, productivity suites).
- Beyond product resale, CDW provides integrated IT solutions including hybrid infrastructure, digital experience, and cybersecurity, as well as managed and advisory services.
Recent news
- Morgan Stanley upgraded CDW to Overweight in late June 2026, citing growing enterprise server demand, and set higher price targets across the IT infrastructure sector.
- First-quarter 2026 results were mixed: revenue came in ahead of expectations, but earnings per share narrowly missed Wall Street estimates, sending shares to a 52-week low in early May.
- A quarterly earnings preview published in mid-July 2026 notes the market is watching closely whether CDW can convert improving hardware demand into cleaner bottom-line results.
Strengths
- The Morgan Stanley upgrade to Overweight reflects growing confidence that enterprise server refresh cycles and AI-driven infrastructure investment could meaningfully lift CDW’s revenue mix.
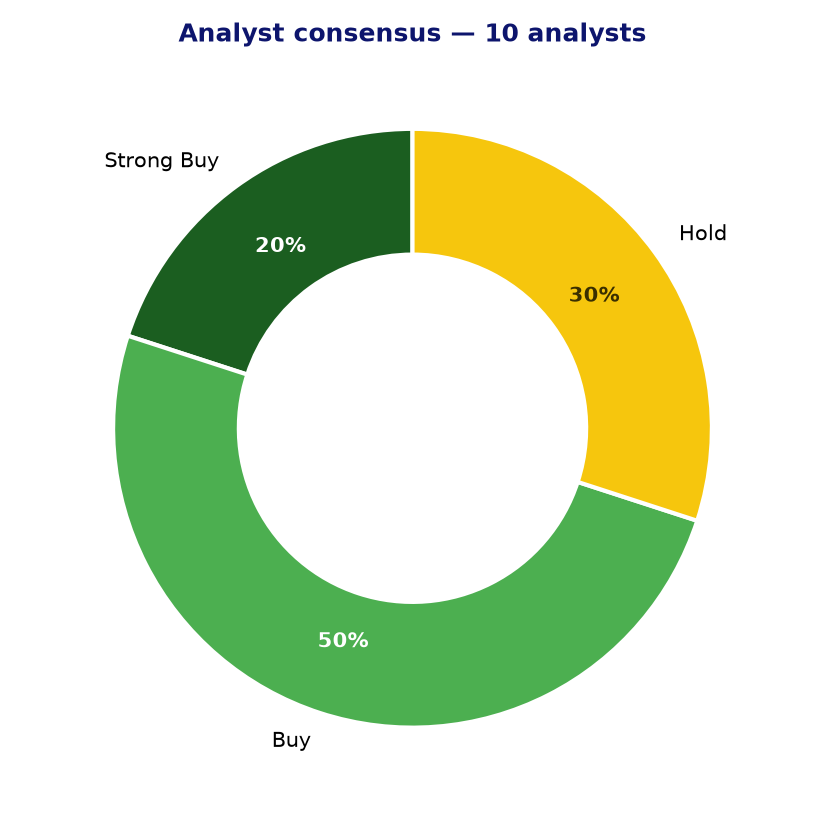
- Analyst sentiment is broadly constructive: 7 out of 10 covering analysts rate the stock Buy or Strong Buy, with no sell ratings on record.
- The 24-month momentum Z-score of 2.44 indicates the stock has shown statistically significant positive price momentum relative to its own history.
- A forward P/E of 13.07 represents a meaningful discount to the trailing P/E of 18.76, suggesting the market expects earnings to improve materially in the near term.
- CDW’s diversified end-market exposure — spanning commercial, government, education, and healthcare — provides some resilience against weakness in any single customer segment.
Points of attention and risks
- The average analyst price target of $152.56 sits marginally below the current share price of $154.00, implying the consensus view reflects fair value rather than meaningful upside at this level.
- First-quarter 2026 earnings narrowly missed estimates, and the resulting drop to a 52-week low is a reminder that execution risk remains a concern in a competitive, low-margin distribution environment.
- EPS growth of just 5% (0.05) is modest, and the PEG ratio of 1.33 suggests the stock is not obviously cheap relative to its near-term growth rate.
- CDW operates in a largely transactional, product-resale-heavy business, which tends to carry thin margins and leaves the company sensitive to vendor pricing changes and component cost inflation.
- The wide spread between the lowest ($123) and highest ($175) analyst price targets signals meaningful uncertainty about the earnings trajectory over the coming year.
Analyst consensus and price targets
Conclusion
CDW sits at an interesting juncture: a well-established IT solutions franchise with broad market coverage, recently upgraded by Morgan Stanley on the back of improving enterprise hardware demand, yet trading at or just above the analyst consensus fair value after a difficult first quarter. The forward earnings multiple looks reasonable if earnings recovery materialises, but modest EPS growth and thin operating margins in a competitive distribution market mean the investment case depends heavily on the pace and scale of the IT refresh cycle. Investors may wish to monitor upcoming quarterly results closely before forming a firm view on whether current pricing adequately reflects both the opportunity and the execution risk.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 04-08-2026. Not investment advice.