
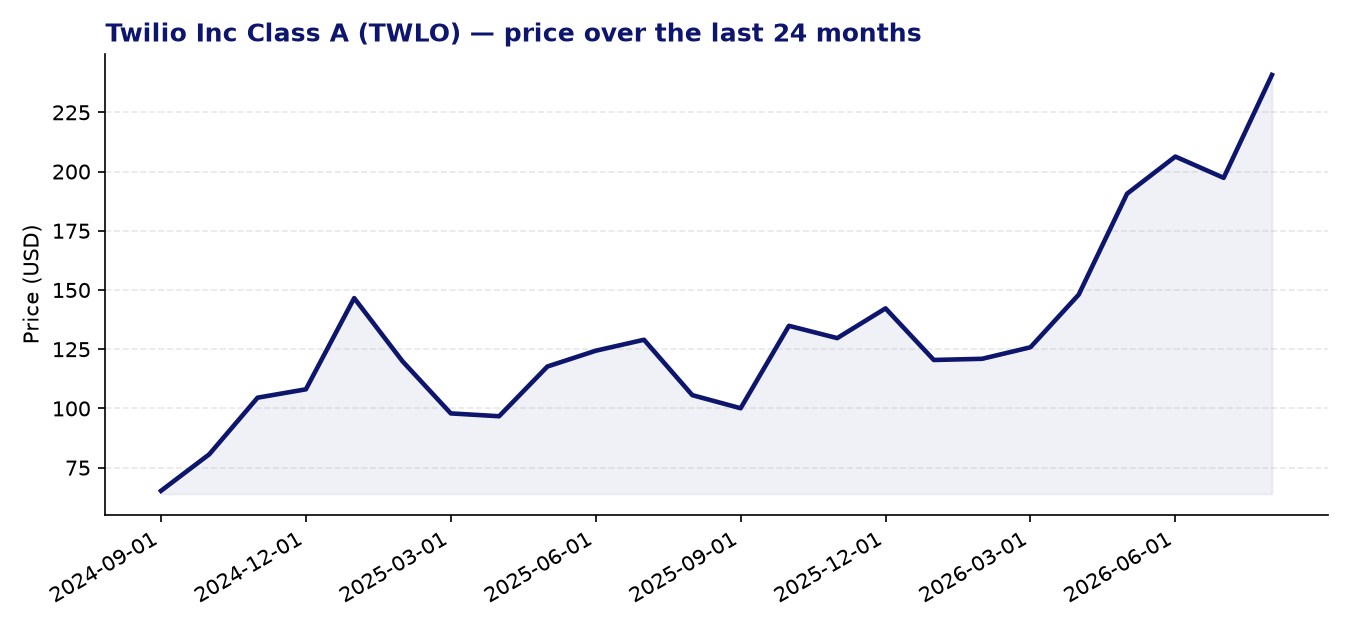
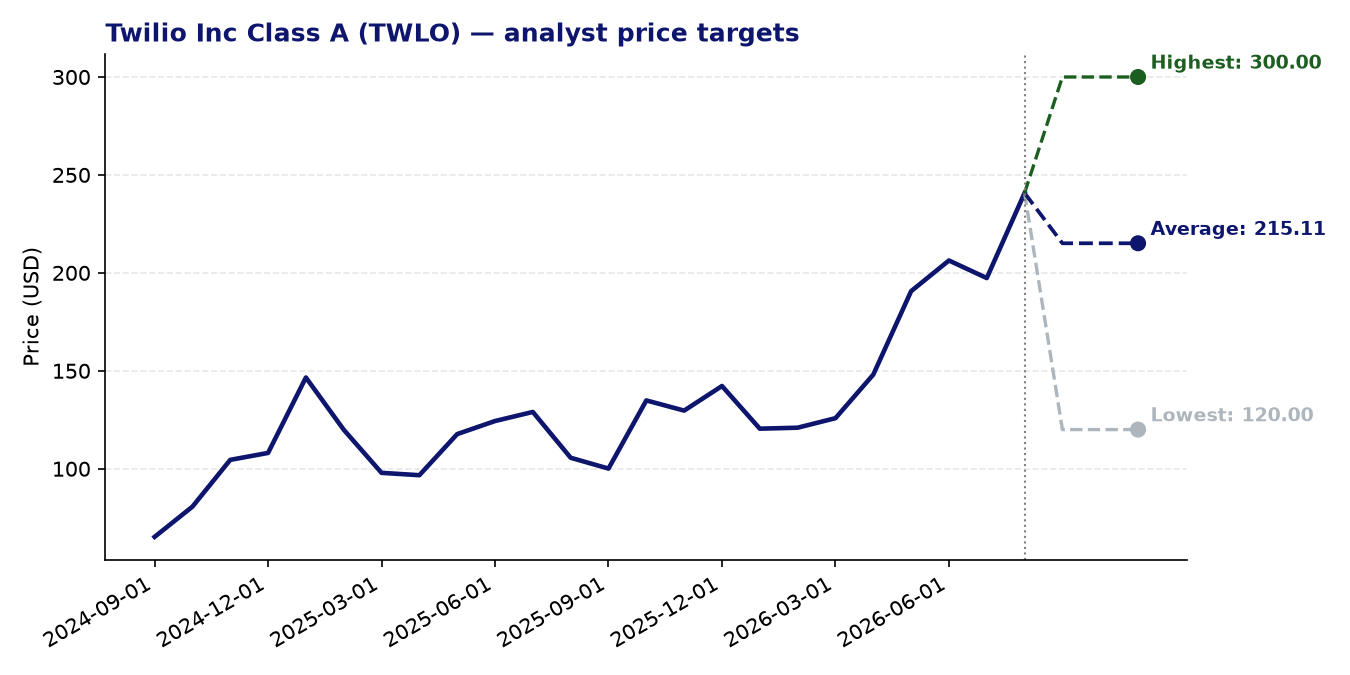
Twilio Inc Class A (TWLO) — current price: 240.78 USD | average price target: 215.11 USD | potential: -10.7%
About Twilio Inc Class A
- Twilio provides a cloud-based customer engagement platform, offering APIs and software that enable businesses to communicate with their customers via messaging, voice, email, and video.
- Its tools support a wide range of use cases, including digital contact centres, marketing campaigns, and user authentication and identity verification.
- Twilio also operates Segment, a customer data platform that consolidates real-time behavioural data from across the customer journey into unified profiles for personalised engagement.
- Founded in 2008 and headquartered in San Francisco, Twilio serves clients across the United States and internationally.
Recent news
- Twilio’s second-quarter 2026 results came in ahead of expectations, with revenue of $1.50 billion surpassing the consensus estimate of $1.43 billion, and earnings also beating forecasts.
- Third-quarter revenue guidance was issued above analyst expectations, reinforcing confidence in the company’s near-term growth trajectory.
- Morgan Stanley maintained its Overweight rating and raised its price target from $200 to $261, citing the early-stage opportunity from AI adoption as a meaningful tailwind.
- Several analysts lifted their forecasts following the Q2 report, though some had previously flagged concerns that the stock’s valuation was already pricing in much of the anticipated AI-driven growth.
Strengths
- Twilio’s Q2 2026 results demonstrated accelerating revenue growth and improving profitability, with voice-based AI tools emerging as a credible new growth driver.
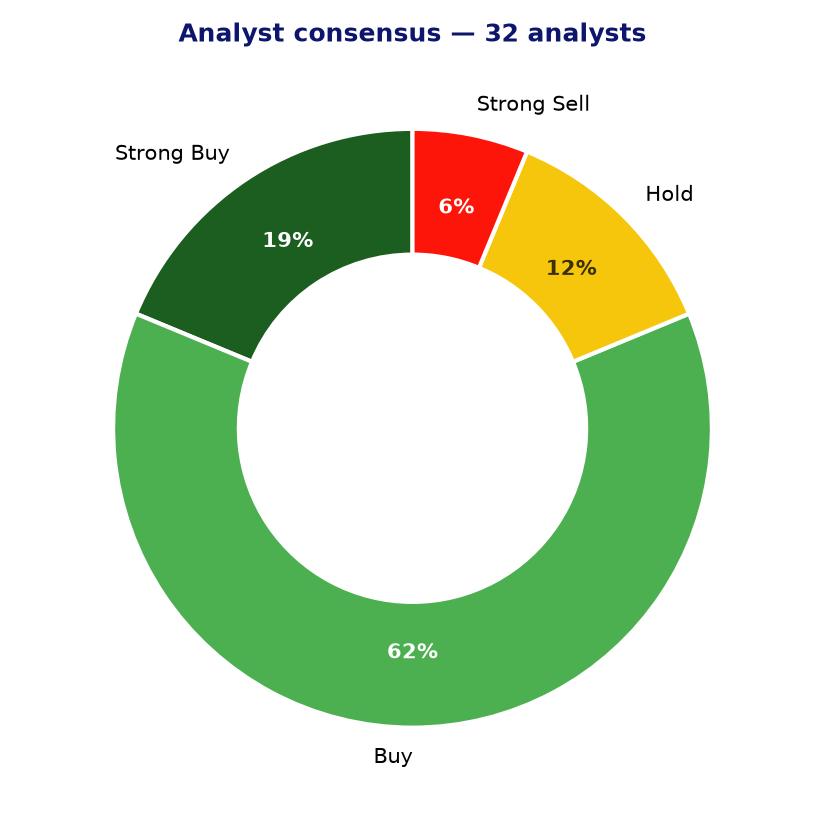
- Analyst sentiment is broadly constructive: of 32 analysts covering the stock, 26 carry a buy or strong buy rating, reflecting confidence in the platform’s strategic direction.
- The forward P/E of 36x is substantially more reasonable than the trailing figure, and a PEG ratio of 0.36 suggests the market may not yet be fully pricing in the expected earnings growth rate.
- A 24-month Z-score momentum reading of 2.39 indicates that the stock has displayed meaningfully positive price momentum relative to its recent history.
- The integration of AI capabilities into Twilio’s communications APIs positions it to benefit from enterprise demand for automated, intelligent customer interactions — a market still considered to be in its early stages.
Points of attention and risks
- At a current price of $240.78, Twilio trades above the analyst consensus price target of $215.11, implying a negative average upside of approximately 10.7% from current levels.
- The trailing P/E ratio of 365x reflects thin current profitability relative to the share price, leaving limited margin for error if earnings growth disappoints.
- EPS growth of 3.5% on a trailing basis is modest for a stock priced at a significant premium, and execution risk remains if AI-driven revenues take longer than anticipated to scale.
- The wide dispersion in price targets — ranging from $120 to $300 — signals material disagreement among analysts about fair value, which itself is a signal of elevated uncertainty.
- Twilio operates in a competitive infrastructure software market where hyperscalers and specialist vendors are actively developing rival communications and customer data capabilities.
Analyst consensus and price targets
Conclusion
Twilio’s strong Q2 results and improving AI-related revenue trends paint an encouraging operational picture, and the PEG ratio and forward earnings multiple suggest the growth story is not entirely reflected in near-term valuation metrics. However, the current share price sits above the average analyst price target, the trailing earnings multiple remains very elevated, and competitive pressures in cloud communications are intensifying. Investors may find the long-term AI opportunity compelling, but the near-term risk-reward balance warrants careful consideration of entry point and position sizing.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 07-08-2026. Not investment advice.