
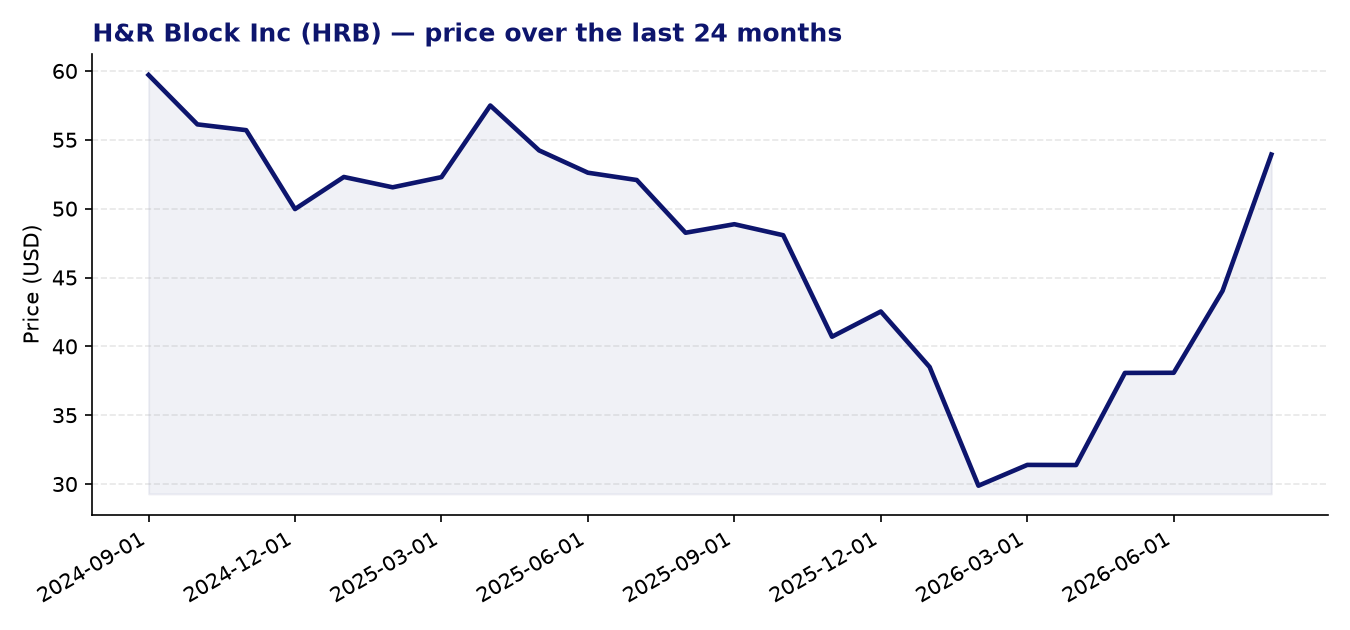
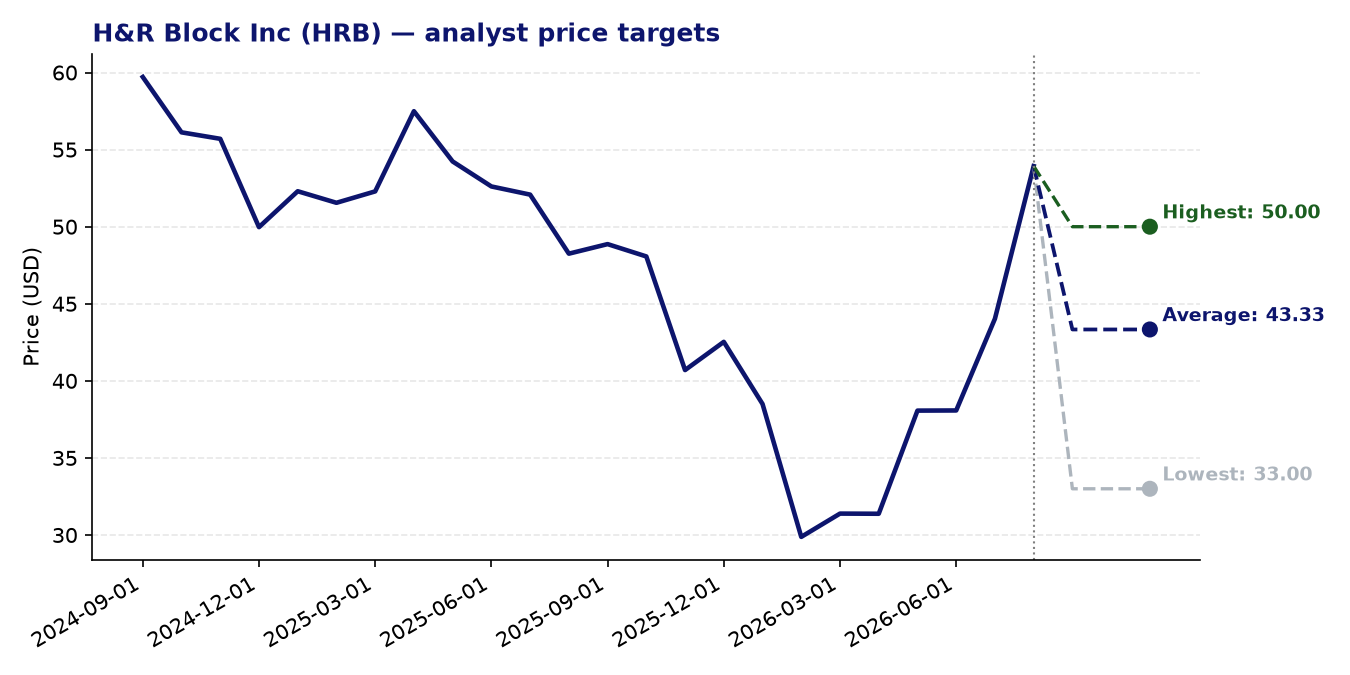
H&R Block Inc (HRB) — current price: 53.93 USD | average price target: 43.33 USD | potential: -19.6%
About H&R Block Inc
- H&R Block is one of the largest tax preparation services companies in the US, offering both assisted (in-person) and do-it-yourself (DIY) filing options across the United States, Canada, and Australia.
- The company operates through a network of company-owned and franchised retail offices, as well as online, mobile, and desktop software platforms.
- Beyond tax preparation, H&R Block offers a range of ancillary financial products, including prepaid debit cards (Emerald and Spruce), short-term refund advance loans, audit protection plans, and tax identity protection services.
- The company also serves small businesses with payment processing, payroll, and bookkeeping solutions, broadening its revenue base beyond the seasonal tax filing window.
Recent news
- H&R Block reported its fiscal fourth-quarter 2026 earnings in August, with an earnings call held on 12 August 2026; specific results were not disclosed in the available excerpts.
- The stock was upgraded to a Strong Buy rating by Zacks in November 2026, driven primarily by an upward revision in earnings estimates, a factor the firm considers a reliable indicator of near-term performance.
- Ahead of the Q4 earnings release, commentary highlighted the stock’s dividend appeal, with an annual yield noted at approximately 3%, attracting income-oriented investors.
- H&R Block was highlighted as a top-ranked value stock in mid-2026, with analysts pointing to its valuation metrics as a potential draw for value-oriented investors in the consumer discretionary space.
Strengths
- The stock trades on a trailing P/E of just 9.48 and a forward P/E of 9.21, suggesting the market is pricing in a modest earnings profile relative to what the company has historically delivered.
- A PEG ratio of 0.62 indicates that the stock may be undervalued relative to its earnings growth trajectory, a metric often favoured by value investors.
- Momentum is notably strong, with a 24-month Z-score of 2.72, reflecting sustained positive price performance relative to its historical norm.
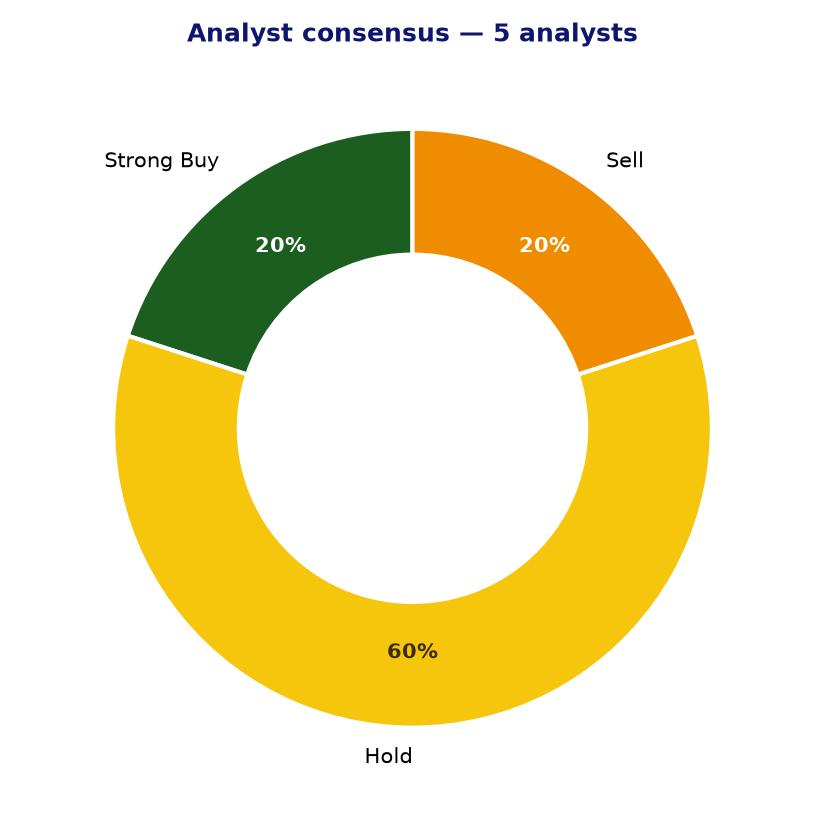
- One of five covering analysts rates the stock a Strong Buy following a recent Zacks upgrade, citing upward earnings estimate revisions as the primary driver.
- A dividend yield of approximately 3% provides a meaningful income component, adding to total return potential for patient, income-focused investors.
Points of attention and risks
- The average analyst price target of $43.33 sits approximately 19.6% below the current share price of $53.93, and even the most optimistic target of $50.00 implies a negative return from current levels — a meaningful caution.
- Analyst coverage is thin (five analysts), with three holding a neutral stance and one carrying a sell rating, suggesting limited conviction among the broader research community at the current price.
- H&R Block’s core tax preparation business is highly seasonal, concentrating revenue and earnings into a narrow window each year, which creates meaningful operational and cash flow variability.
- The consumer tax services market faces structural competitive pressure from free government-provided filing options and well-resourced software competitors, which could constrain pricing power over time.
- EPS growth of 0.17 (17%) appears modest in the context of broader market opportunities, and the company’s ability to sustain growth beyond its core franchise depends on successful expansion into adjacent financial services — an area with its own execution risks.
Analyst consensus and price targets
Conclusion
H&R Block presents an interesting profile for value-oriented investors: a low earnings multiple, a sub-1 PEG ratio, a meaningful dividend yield, and strong recent price momentum all speak in its favour. However, the current share price already sits above every analyst’s price target, including the most bullish, which is a significant consideration that warrants careful attention. The business itself is well-established but faces structural headwinds from competition and seasonality, and the consensus among analysts skews cautious at these levels. Investors may find the fundamentals attractive but should weigh the current valuation against the market’s apparent re-rating of the stock.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 12-08-2026. Not investment advice.