
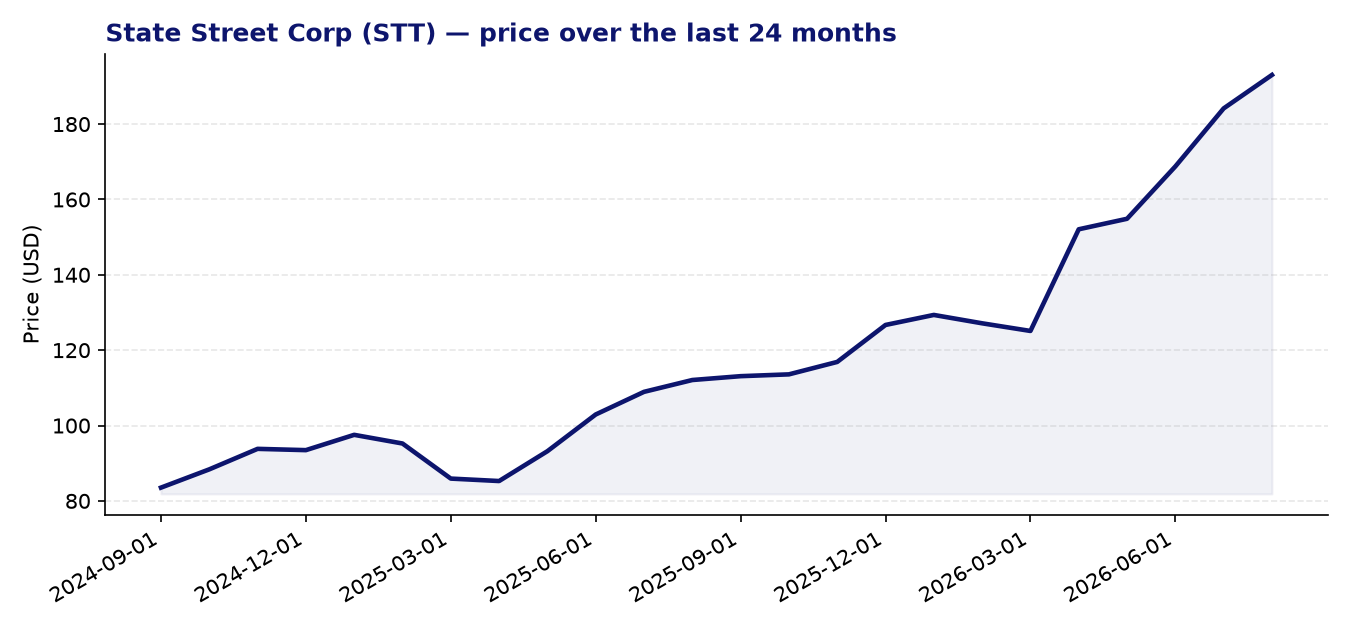
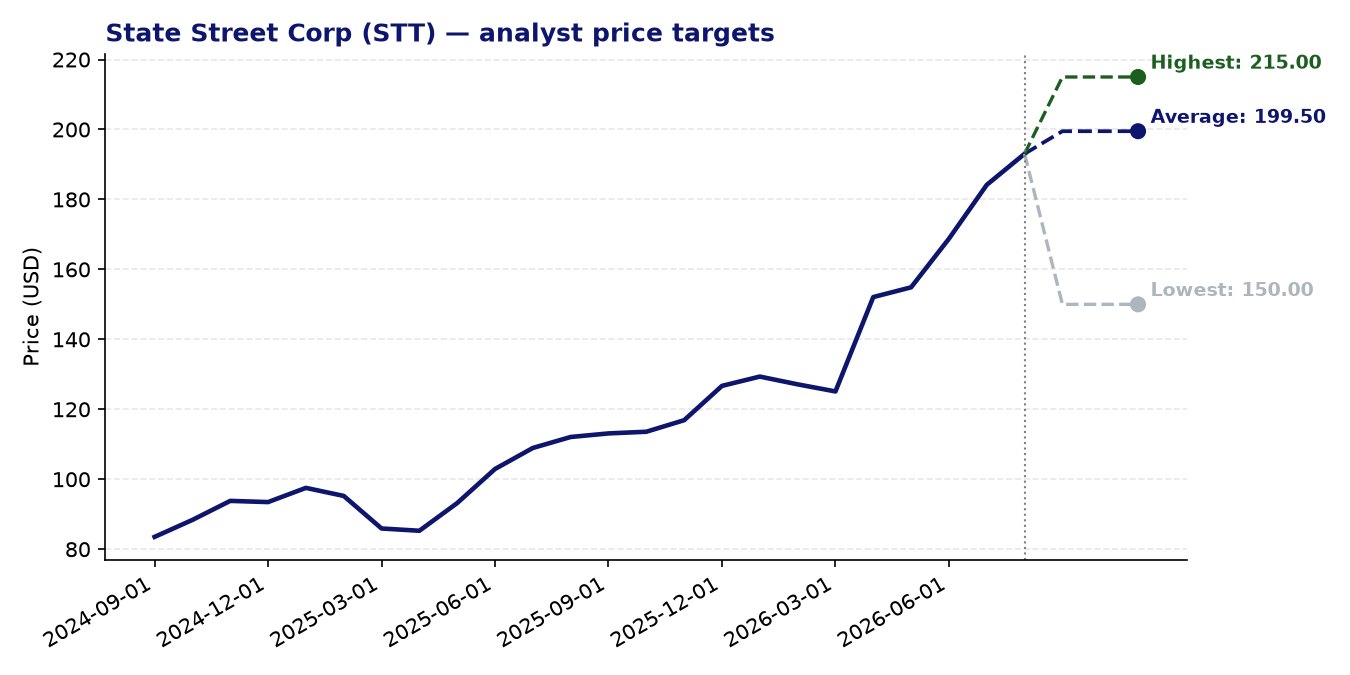
State Street Corp (STT) — current price: 193.04 USD | average price target: 199.50 USD | potential: +3.3%
About State Street Corp
- State Street Corporation, founded in 1792 and headquartered in Boston, is one of the world’s leading providers of financial services to institutional investors, including custody, fund administration, and accounting.
- The company serves a broad client base including mutual funds, pension plans, insurance companies, wealth managers, and endowments.
- State Street offers the Alpha platform, an integrated solution combining portfolio management, trading, analytics, compliance, and data aggregation tools for institutional clients.
- Through its investment management arm, the company provides strategies across equity, fixed income, cash, multi-asset, and alternatives, including a well-established ETF business.
- Additional services include foreign exchange and trading, securities finance, collateral management, and front-office technology outsourcing.
Recent news
- State Street reported Q2 2026 adjusted earnings of $3.65 per share, comfortably ahead of the analyst consensus estimate of $3.30 and representing a significant year-on-year improvement from $2.53 per share in the same quarter of 2025.
- Management commentary following the results pointed to favourable macro conditions — including elevated equity markets boosting asset-based fee income — as key drivers of strong revenue growth and improved operating leverage, with profitability described as reaching multi-year highs.
- Following the earnings beat, analysts noted that upward revisions to earnings estimates have been accumulating, a trend often associated with continued positive price momentum in the near term.
Strengths
- The Q2 2026 earnings beat was substantial, with reported EPS roughly 10% above consensus, suggesting the business is executing well and benefiting from a supportive market environment.
- The forward P/E of 12.61 and PEG ratio of 0.81 indicate the stock may be priced attractively relative to its expected earnings growth, with a sub-1 PEG often interpreted as a sign of reasonable valuation.
- The Z-score momentum reading of 2.03 over a 24-month window reflects meaningful positive price momentum, suggesting the stock has been gaining ground on a sustained basis.
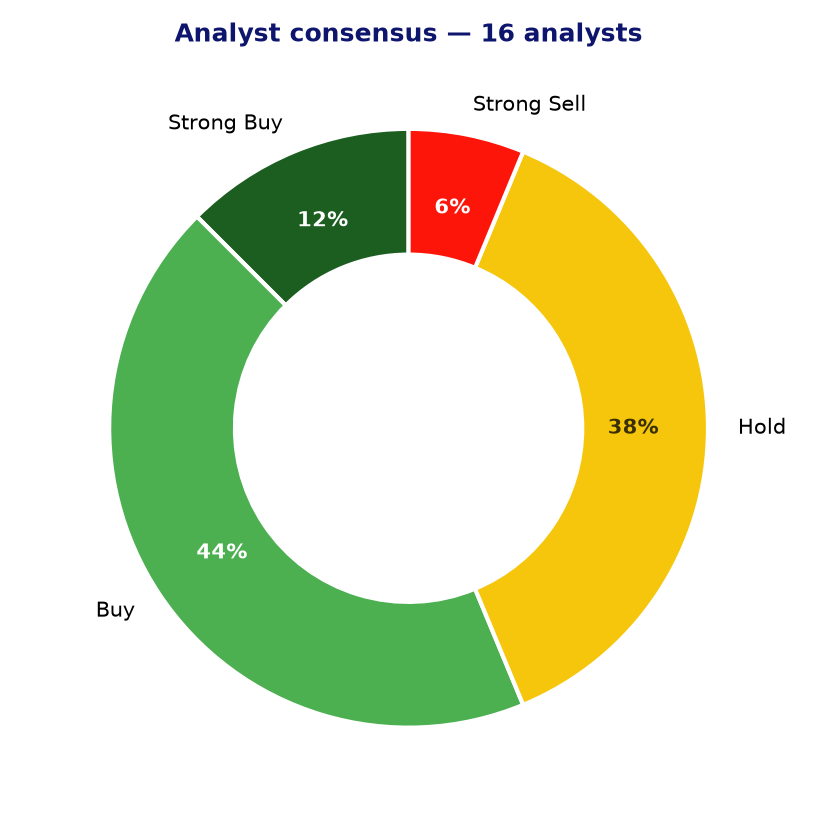
- Analyst sentiment is broadly constructive, with nine of sixteen covering analysts rating the stock a buy or strong buy and no outright sell ratings among the majority.
- The Alpha platform and broad suite of institutional services position State Street well in the growing trend toward outsourcing among asset managers and asset owners.
Points of attention and risks
- The average analyst price target of $199.50 implies only modest upside of around 3.3% from the current price, suggesting much of the positive near-term newsflow may already be reflected in the stock.
- The reported trailing EPS growth figure is marginally negative at -0.24, which, while likely distorted by non-recurring items, warrants scrutiny when assessing the sustainability of earnings improvement.
- Six of sixteen analysts maintain a hold rating, and one has a strong sell, with the lowest price target standing at $150 — a notable 22% below the current price — indicating a meaningful divergence of opinion on valuation.
- A significant portion of State Street’s revenue is tied to asset levels and market activity; a sustained equity market downturn would compress fee income and could quickly reverse the operating leverage gains seen in recent quarters.
- The custody and fund administration business is highly competitive and operationally intensive, with ongoing pressure on fee rates and the need for continued technology investment to retain and grow institutional mandates.
Analyst consensus and price targets
Conclusion
State Street is delivering its strongest profitability numbers in years, supported by a favourable market backdrop and a solid earnings beat in Q2 2026, while its forward valuation metrics appear undemanding relative to peers. However, the limited consensus price target upside and the stock’s dependence on buoyant equity markets for fee income are factors that merit careful consideration. The company’s long institutional heritage and the broadening Alpha platform provide a credible long-term case, but investors should be mindful that much of the current earnings tailwind is cyclically driven rather than purely structural.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 17-08-2026. Not investment advice.