
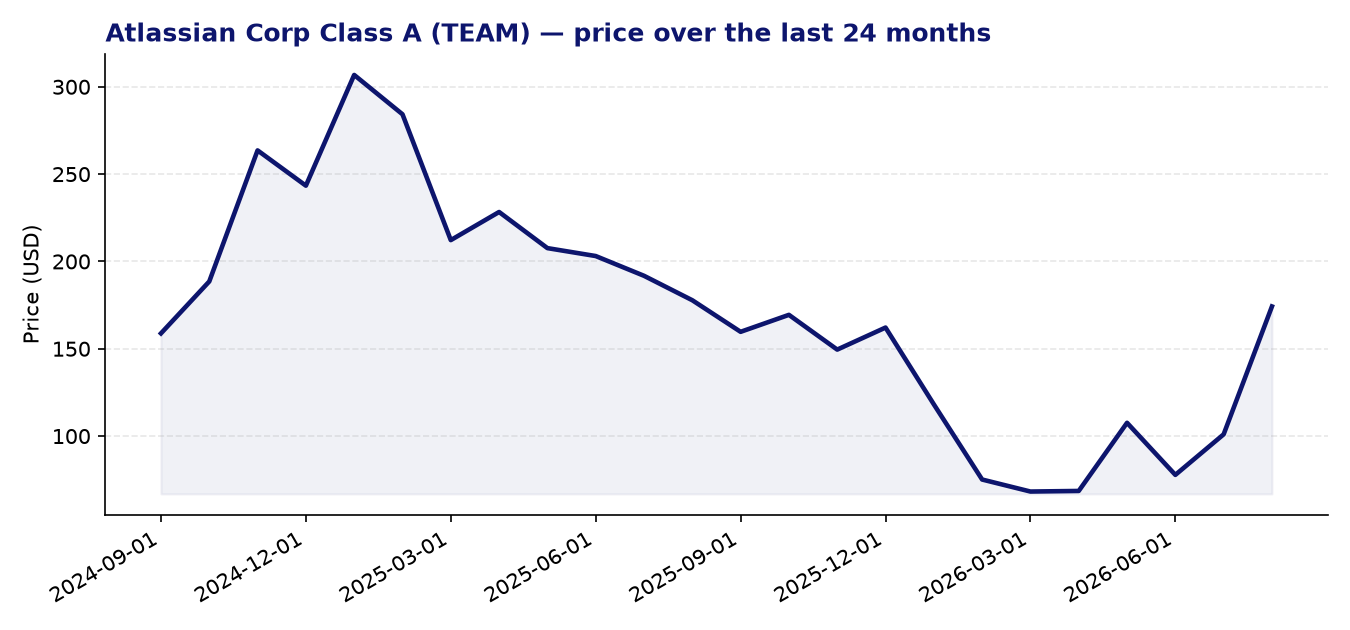
Atlassian Corp Class A (TEAM) — current price: 174.23 USD | average price target: 187.93 USD | potential: +7.9%
About Atlassian Corp Class A
- Atlassian is a Sydney-founded enterprise software company whose platform connects teams across software development, IT service management, and workplace collaboration.
- Its product portfolio spans well-known tools such as Jira, Confluence, Trello, Loom, and Bitbucket, alongside newer offerings including Rovo and Guard.
- The company also offers Collections, curated bundles of apps and AI agents built on its cloud platform to address cross-functional workflows such as strategy, service, and software delivery.
- Atlassian operates as a horizontal SaaS business, serving a broad range of organisations globally rather than targeting a single vertical industry.
Recent news
- Atlassian’s fiscal Q4 results, reported in August 2026, beat market expectations and helped dispel concerns about the company’s growth trajectory, sparking a notable share price rally.
- Jefferies analyst Brent Thill reaffirmed a Buy rating in July 2026, setting a price target of $150, reflecting continued confidence in the company’s medium-term outlook.
- Mizuho Securities reiterated its Buy rating around the same period with a $145 target, at a time when the stock was trading near $92, implying meaningful upside at that point.
- KeyBanc’s Jason Celino maintained a Buy rating in September 2026 with a $115 price target, though the stock has since appreciated well above that level.
Strengths
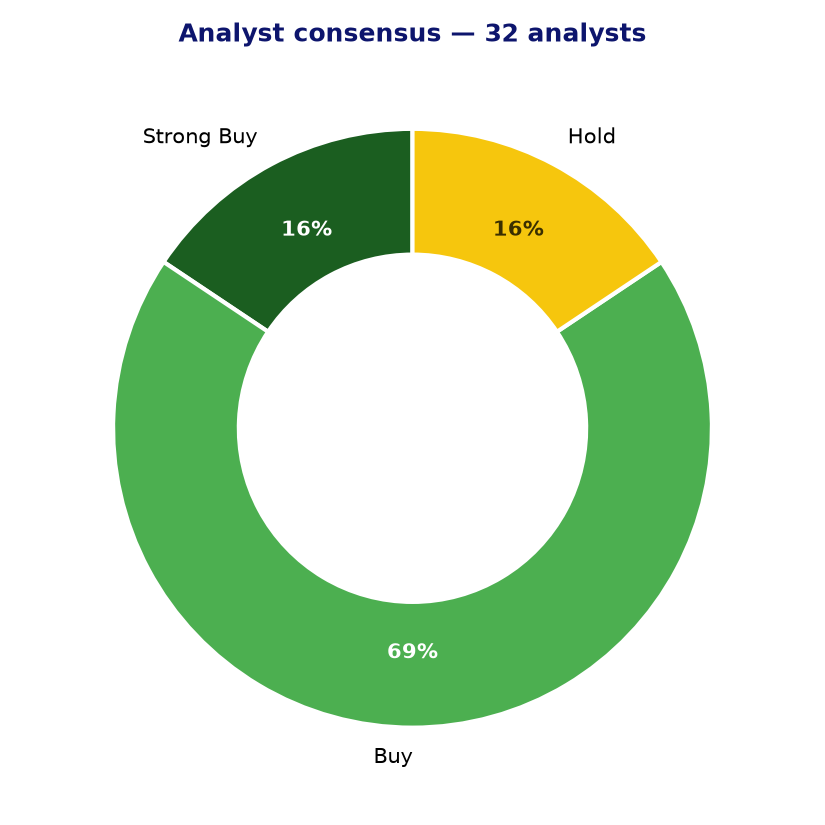
- Analyst sentiment is broadly constructive: 27 of 32 covering analysts rate the stock Buy or Strong Buy, with no sell ratings, suggesting wide professional confidence in the business.
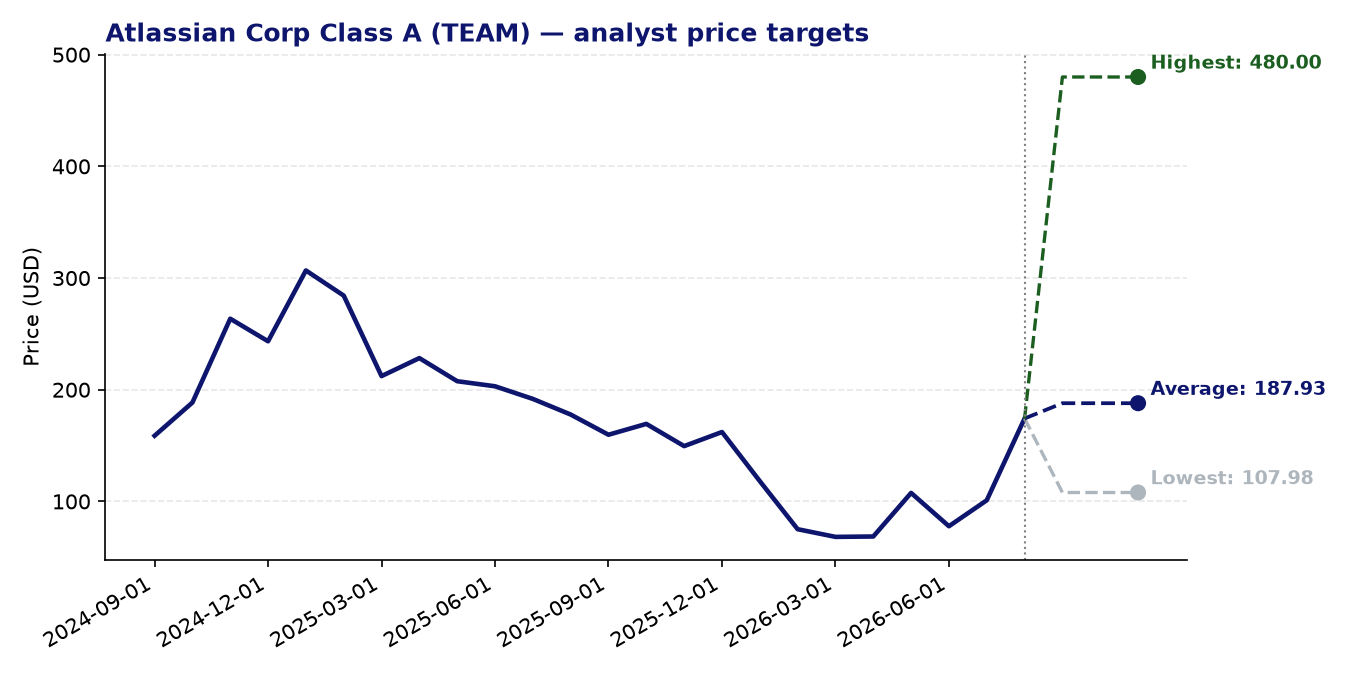
- The consensus price target of $187.93 implies approximately 7.9% upside from current levels, with one analyst holding a target as high as $480, indicating a wide range of bullish scenarios.
- A 24-month Z-score momentum reading of 2.19 points to strong and sustained relative price performance, suggesting the stock has been a consistent outperformer over a two-year horizon.
- The forward P/E of 25.81 is relatively measured for a high-quality SaaS franchise, and the PEG ratio of 1.66 suggests the growth profile is not being ignored in the valuation.
- Atlassian’s cloud-first platform, expanding AI capabilities through products like Rovo, and its large installed base position it well to benefit from continued enterprise digitalisation.
Points of attention and risks
- The stock is trading above several analyst price targets, including those from KeyBanc ($115) and Mizuho ($145), raising questions about whether near-term upside has already been captured.
- The absence of a trailing P/E ratio and no reported EPS figure indicate the company is not yet consistently profitable on a GAAP basis, which warrants attention for more conservative investors.
- The wide gap between the lowest ($107.98) and highest ($480.00) price targets reflects genuine disagreement among analysts about Atlassian’s long-run earnings power and growth durability.
- As a horizontal SaaS provider, Atlassian faces intensifying competition from large incumbents such as Microsoft and ServiceNow, which are embedding collaboration and ITSM features into existing enterprise suites.
- The company’s ongoing transition from server-based licensing to cloud subscriptions, while strategically sound, can create near-term revenue variability and adds execution risk during the migration period.
Analyst consensus and price targets
Conclusion
Atlassian presents a compelling long-term case as a scaled, diversified collaboration and development platform with strong analyst backing and positive price momentum. However, the share price has risen meaningfully, now sitting above several recently issued price targets, which narrows the margin of safety for new investors and heightens the importance of continued execution on cloud growth and AI integration. The lack of GAAP profitability and competitive pressures from larger software vendors are genuine factors to weigh alongside the business’s undoubted strategic strengths. Investors considering a position may find it prudent to assess how much of the recovery already reflected in the current price aligns with their own expectations for the company’s earnings trajectory.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 19-08-2026. Not investment advice.