
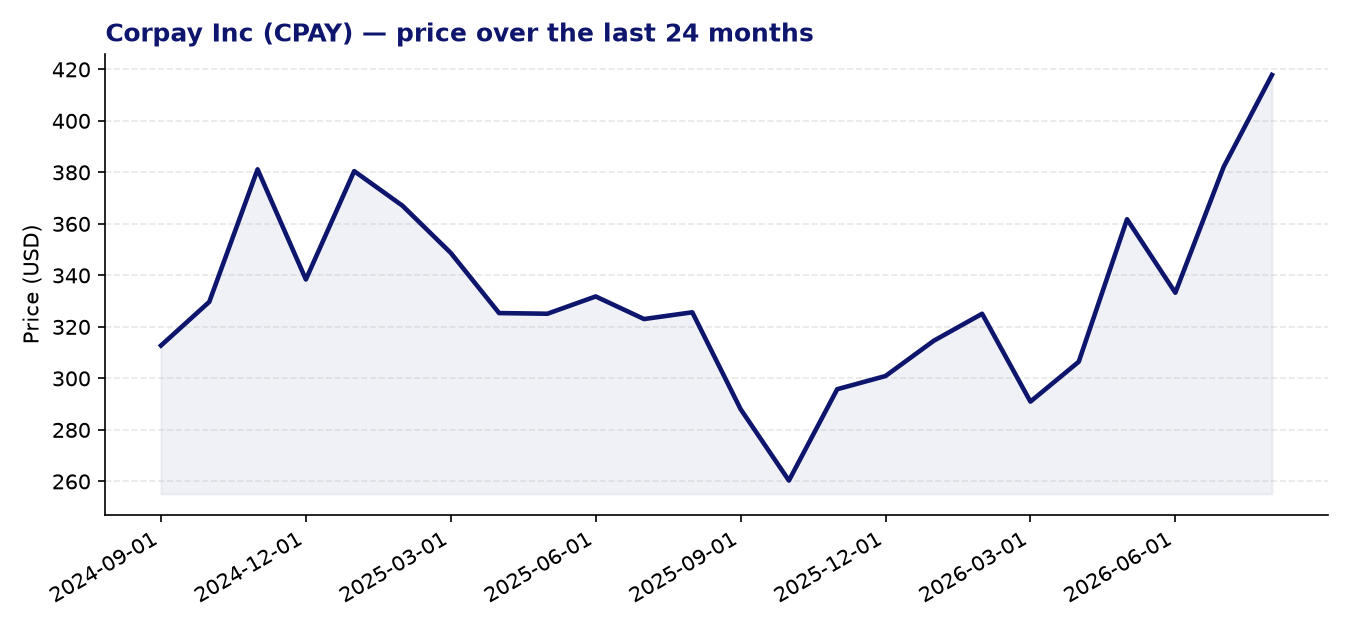
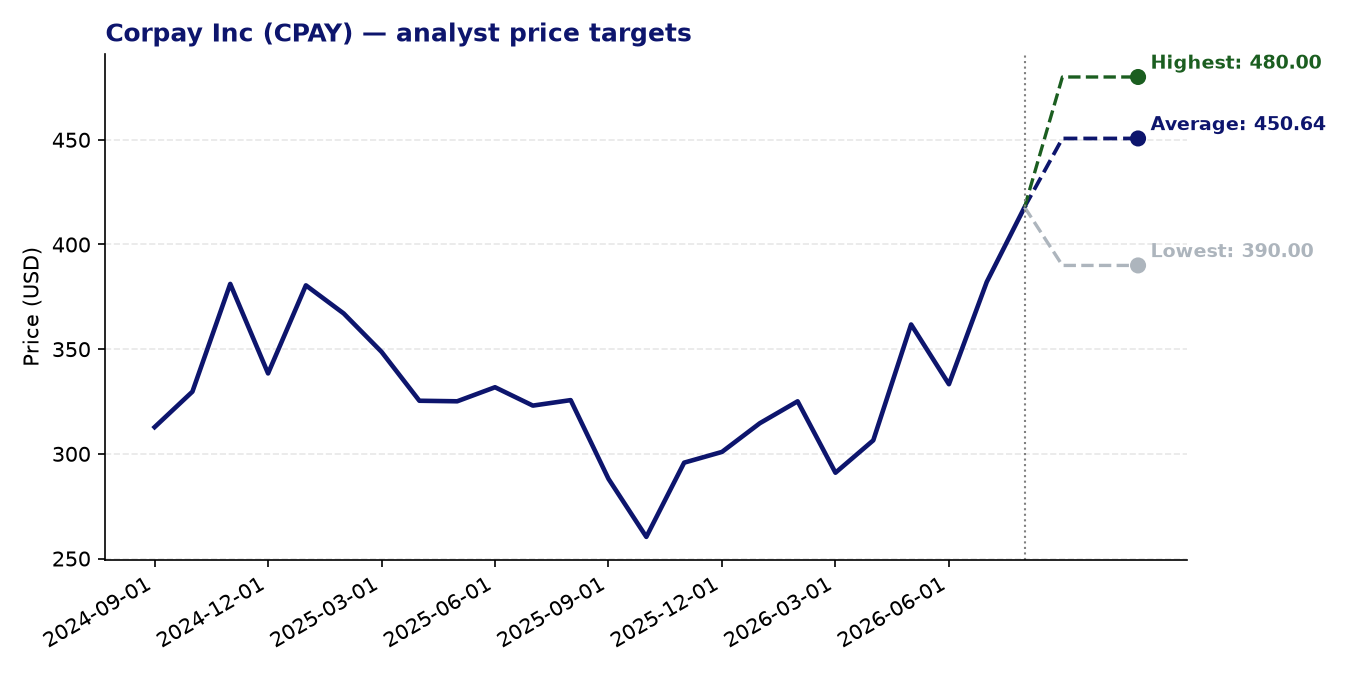
Corpay Inc (CPAY) — current price: 417.82 USD | average price target: 450.64 USD | potential: +7.9%
About Corpay Inc
- Corpay Inc (formerly FLEETCOR Technologies) is an Atlanta-based global payments company founded in 1986, serving businesses and consumers across multiple payment verticals.
- Its Corporate Payments segment offers cross-border payments, AP modernisation, virtual cards, and spend management solutions for companies of all sizes.
- The Vehicle Payments segment provides fleet and fuel cards, toll and parking payments, vehicle compliance, and related transportation services.
- Corpay also operates Lodging Payments solutions, managing overnight accommodation for travelling employees, airline crews, and stranded passengers.
- The company serves a broad base of business, merchant, consumer, and payment network customers globally.
Recent news
- Corpay delivered a record-setting second quarter for fiscal 2026, with revenue of $1.34 billion, up 21% year-over-year and $45 million ahead of its own guidance, while Cash EPS of $7.00 rose 36% year-over-year.
- Following the strong Q2 result, management raised full-year 2026 guidance for both revenue and earnings, reflecting growing confidence in the company’s near-term outlook.
- First-quarter 2026 results were also notably strong, with revenue of $1.26 billion (up 25% year-over-year) and Cash EPS of $5.80 (up 29% year-over-year), both exceeding prior guidance.
- Analyst commentary in mid-2026 highlighted Corpay as both a top-ranked momentum stock and a value stock, reflecting improving market sentiment toward the shares.
Strengths
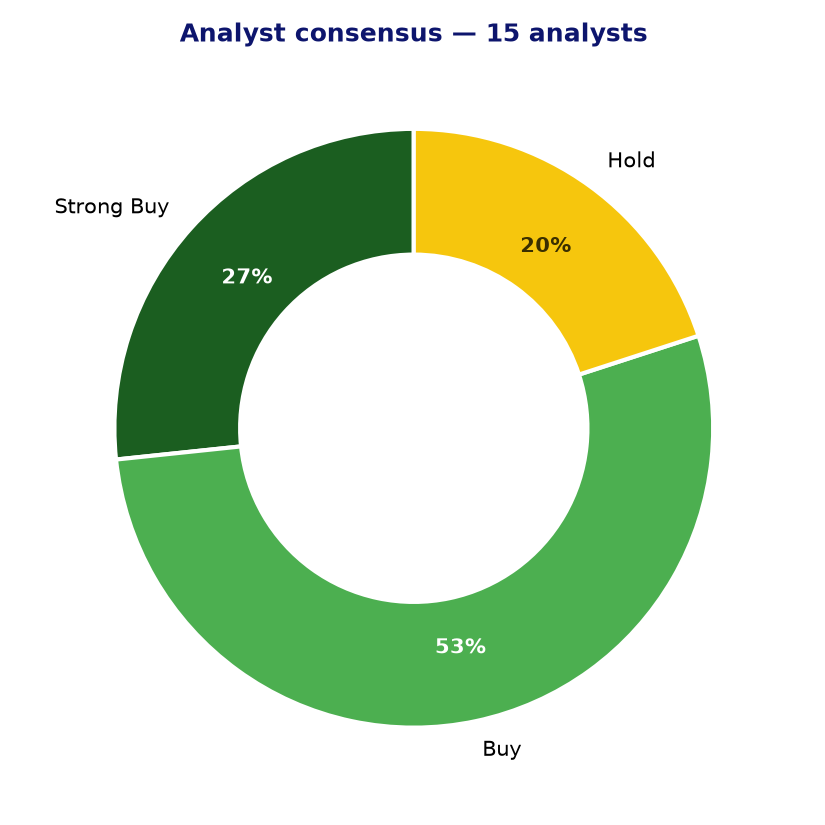
- The analyst community is broadly constructive on the stock, with 12 out of 15 covering analysts rating it buy or strong buy and an average price target of $450.64, implying approximately 7.9% upside from current levels.
- Revenue growth has been exceptional in recent quarters, with back-to-back results materially ahead of guidance and year-over-year increases of 21–25%, suggesting strong underlying business momentum.
- The 24-month Z-score momentum reading of 2.13 indicates that the share price has been trending meaningfully above its historical average, consistent with sustained positive price momentum.
- Valuation metrics appear reasonable relative to growth: the forward P/E of 13.37 and a PEG ratio of 0.93 suggest the market is not yet pricing in an excessive premium for the company’s earnings trajectory.
- Corpay has a track record of beating consensus earnings estimates over multiple consecutive quarters, which tends to support analyst confidence and reduces near-term earnings-surprise risk.
Points of attention and risks
- The trailing EPS growth figure is slightly negative (-0.13%), which may reflect timing differences or one-off charges; investors should monitor whether this is a transitory issue or indicative of underlying pressure on reported earnings.
- At a current P/E of 25.42, the shares are not inexpensive on a trailing basis, and any disappointment in the pace of revenue growth or margin expansion could weigh on the valuation.
- The consensus price target range is relatively narrow ($390–$480), and the lowest target sits below the current price, suggesting some analysts see limited upside or even modest downside risk at present levels.
- Corpay operates in a competitive and evolving payments landscape, with exposure to foreign exchange fluctuations (given its cross-border payments business) and potential pressure from fintech disruptors targeting the same corporate spending segments.
- The company’s Vehicle Payments segment faces a structural question over the long term as electric vehicles and changing fleet management needs may alter fuel card usage patterns, though this risk is likely gradual rather than immediate.
Analyst consensus and price targets
Conclusion
Corpay presents a compelling operational picture, with strong double-digit revenue growth, consistent beats against guidance, and a broadly supportive analyst consensus pointing to modest further upside. The forward valuation and PEG ratio suggest the market has not dramatically overpriced these qualities. That said, the negative trailing EPS growth figure and the competitive dynamics of the global payments market warrant ongoing attention, and investors should weigh the relatively narrow analyst target range when considering position sizing.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 21-08-2026. Not investment advice.