
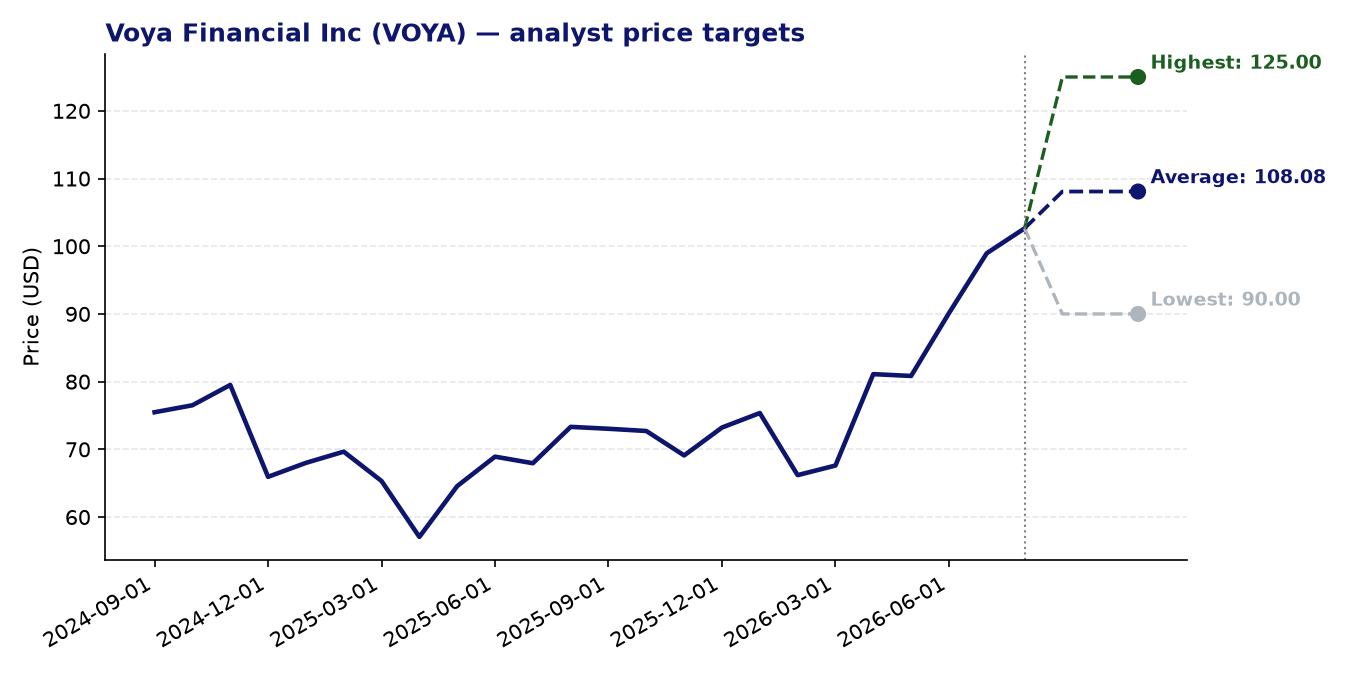
Voya Financial Inc (VOYA) — current price: 102.64 USD | average price target: 108.08 USD | potential: +5.3%
About Voya Financial Inc
- Voya Financial is a New York-based financial services company founded in 1975 (formerly ING U.S., Inc.), focused on workplace benefits, savings solutions, and investment management.
- Its Retirement segment delivers full-service retirement products, recordkeeping, stable value investments, and wealth management services to a broad range of institutional and individual clients including corporates, healthcare organisations, and government bodies.
- The Employee Benefits segment provides group and individual insurance products—such as stop-loss, life, and disability cover—alongside health account solutions and benefits administration tools, primarily for mid-size and large employers.
- The Investment Management segment offers fixed income, equity, multi-asset, and alternative strategies to retail, intermediary, and institutional clients through multiple distribution channels.
Recent news
- Voya’s second-quarter 2026 results came in below expectations, with adjusted EPS of $1.51 falling meaningfully short of the consensus estimate of $1.88 and well below the $2.40 reported in the same quarter a year earlier.
- Revenue for Q2 2026 was reported at $269 million, representing a year-on-year decline of approximately 24%, and also came in slightly below analyst forecasts.
- Management attributed part of the earnings shortfall to weaker alternative investment returns during the quarter, but signalled that these results are expected to recover in Q3 2026.
- Voya announced a share buyback programme of at least $100 million for the third quarter of 2026, reflecting management’s continued confidence in capital deployment despite the softer quarterly print.
Strengths
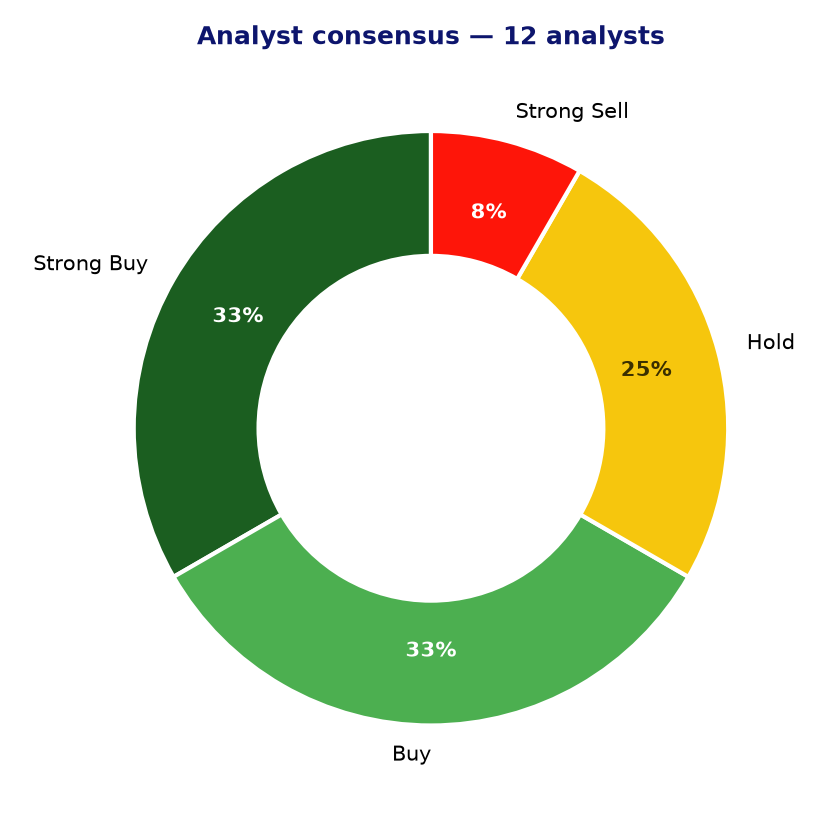
- The analyst community remains broadly constructive, with eight of twelve covering analysts rating the stock either buy or strong buy, and no outright sell ratings beyond one strong sell.
- The average analyst price target of $108.08 implies modest upside of around 5.3% from the current price of $102.64, with the most optimistic target reaching $125.00.
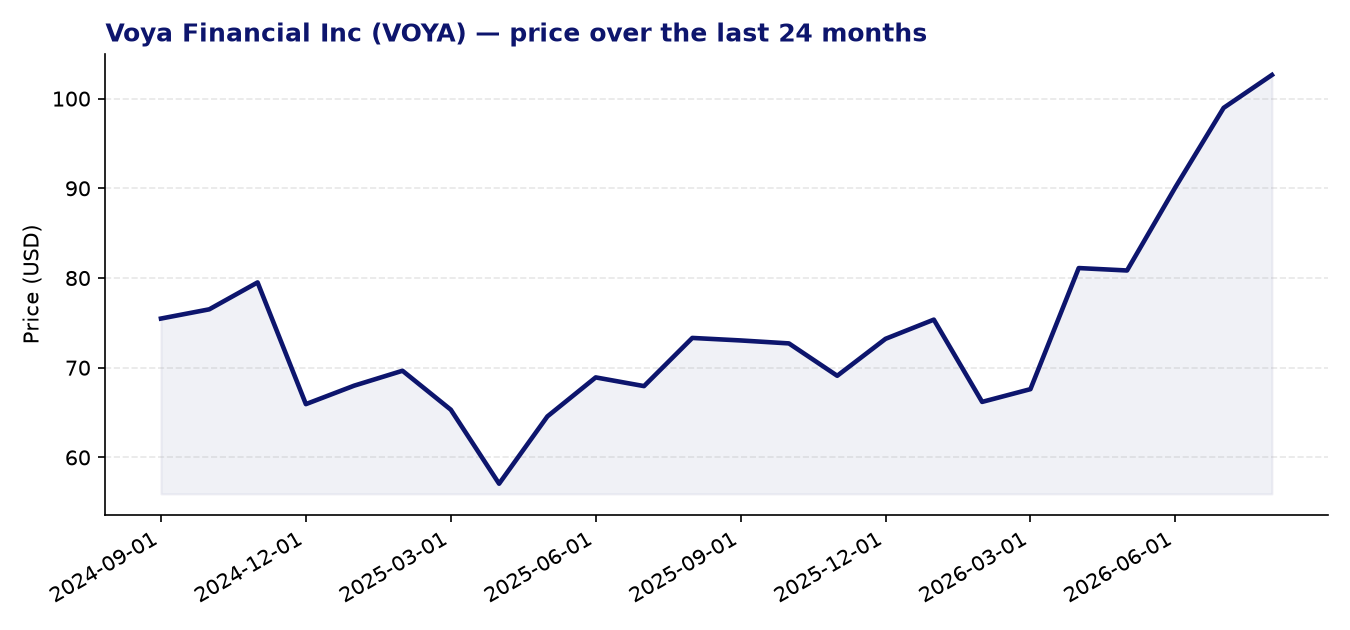
- A 24-month Z-score momentum reading of 2.25 indicates that the stock has exhibited meaningful positive price momentum relative to its historical range, which can reflect improving market sentiment.
- The forward P/E of 9.03 is notably low relative to the trailing P/E of 17.31, suggesting the market anticipates a significant recovery in earnings, which management’s commentary about improving alternative investment income appears to support.
- The commitment to at least $100 million in Q3 buybacks demonstrates active capital returns to shareholders and implies management views the current valuation as attractive.
Points of attention and risks
- The Q2 2026 earnings miss was substantial—adjusted EPS came in roughly 20% below consensus—and year-on-year EPS declined sharply from $2.40 to $1.51, raising questions about near-term earnings trajectory.
- Reported EPS growth is currently negative (-0.43), and revenue declined by more than 24% year-on-year, reflecting genuine pressure on the business rather than a purely one-off event.
- The wide spread between the lowest ($90.00) and highest ($125.00) analyst price targets highlights considerable uncertainty about fair value and the range of plausible outcomes.
- As a financial conglomerate, Voya is exposed to interest rate sensitivity, equity market fluctuations, and credit risk across its retirement, insurance, and investment management businesses simultaneously.
- The company’s earnings recovery thesis depends partly on a rebound in alternative investment income—an asset class that can be volatile and difficult to forecast with precision.
Analyst consensus and price targets
Conclusion
Voya Financial presents a mixed near-term picture: a meaningful Q2 earnings miss and declining revenues sit alongside a low forward valuation, broadly positive analyst sentiment, and a management team actively returning capital through buybacks. The investment case hinges in part on whether the anticipated recovery in alternative investment results materialises and whether the structural momentum in its Retirement and Employee Benefits franchises can sustain fee-based revenue growth. Investors weighing an interest in VOYA may wish to monitor the Q3 results closely to assess whether management’s more optimistic outlook translates into measurable improvement.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 31-08-2026. Not investment advice.