
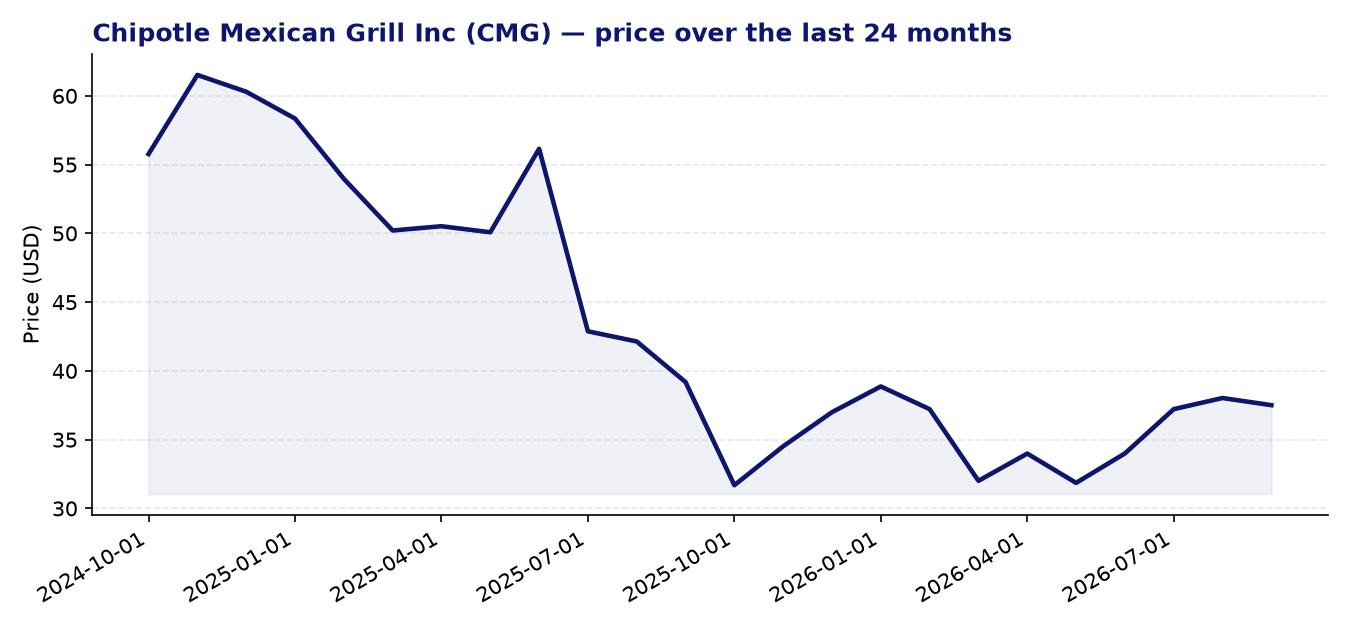
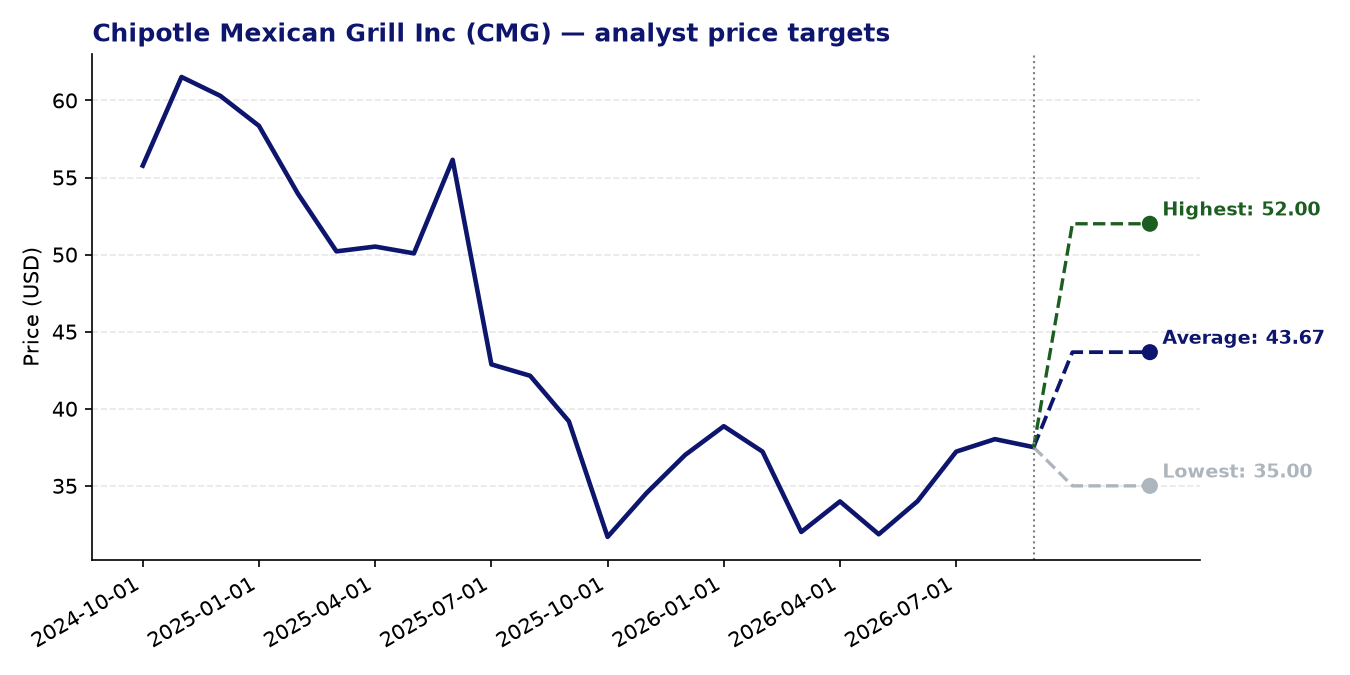
Chipotle Mexican Grill Inc (CMG) — current price: 37.51 USD | average price target: 43.67 USD | potential: +16.4%
About Chipotle Mexican Grill Inc
- Chipotle Mexican Grill owns and operates a chain of fast-casual restaurants serving Mexican-inspired food, including burritos, burrito bowls, tacos, quesadillas, and salads.
- The company emphasises responsibly sourced ingredients, marketing its meats under the ‘Responsibly Raised’ brand.
- Digital ordering — via its own website, mobile app, and third-party delivery platforms — is an important and growing part of its business model.
- Chipotle operates primarily in the United States but also has locations in Canada, France, Germany, and the United Kingdom, with ongoing international expansion underway.
Recent news
- Chipotle’s second-quarter 2026 results beat Wall Street expectations, with earnings of $0.33 per share and revenue of $3.35 billion, sending the stock up sharply in early trading.
- Following the Q2 beat, management raised its full-year same-store sales growth guidance, a signal of improved customer traffic and underlying demand.
- Research firm BTIG reaffirmed its Buy rating and maintained a $45 price target in early August, citing continued confidence in the company’s outlook.
- A recent analysis flagged mixed Q2 signals — including a modest 2.2% comparable-sales increase and some margin compression — as macro headwinds continue to weigh on the broader restaurant sector.
Strengths
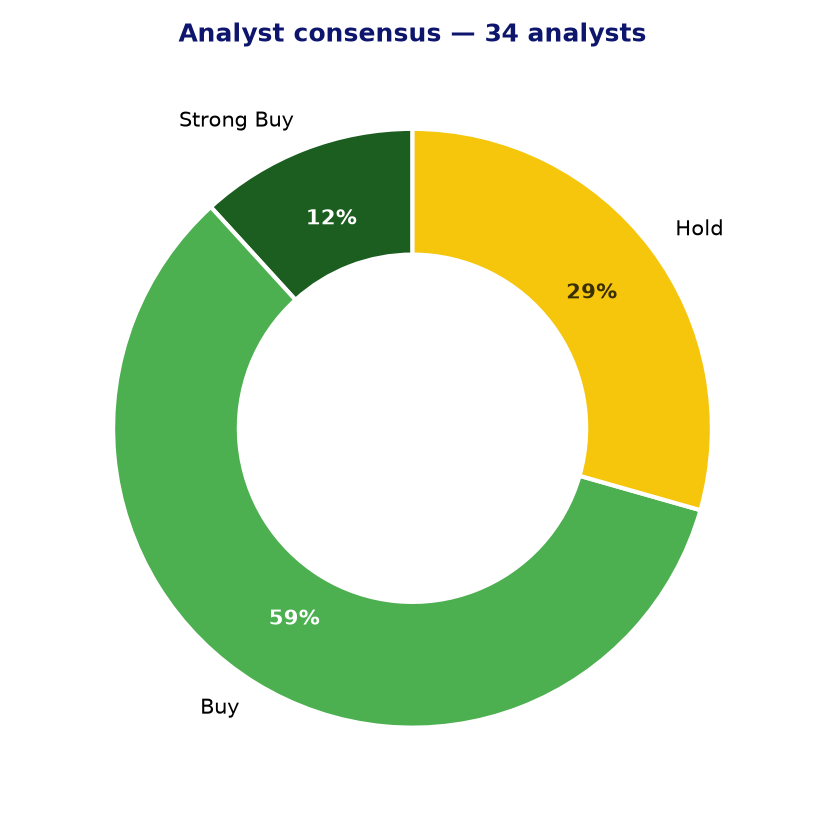
- Analyst sentiment is broadly constructive: 24 of 34 covering analysts rate the stock Buy or Strong Buy, with an average price target of $43.67, implying roughly 16% upside from current levels.
- The 24-month price momentum Z-score of 2.31 indicates that the stock has been trending meaningfully above its historical average, reflecting sustained investor interest.
- The Q2 earnings beat, combined with a raised same-store sales forecast, suggests the business is navigating a difficult consumer environment better than many peers.
- Aggressive share buybacks, noted in recent commentary, provide a degree of capital return to shareholders and offer support to earnings per share over time.
- Chipotle’s international expansion — still at an early stage — represents a long-term growth avenue beyond the already substantial domestic footprint.
Points of attention and risks
- The trailing P/E of 34.7x and a PEG ratio of 2.05 suggest the stock is priced for solid growth; any deterioration in earnings momentum could leave the valuation looking stretched.
- EPS growth is currently slightly negative (-0.07), which sits in tension with a premium multiple and warrants monitoring over coming quarters.
- The Q2 comparable-sales increase of 2.2% was relatively modest, and margin compression points to cost pressures that may persist if the macro environment remains challenging.
- Consumer spending in the restaurant sector faces broader headwinds; a prolonged softening in discretionary spending could weigh on traffic and ticket size.
- The wide range of analyst price targets ($35 to $52) reflects genuine uncertainty about the pace of recovery in profitability, and the lowest target sits below the current share price.
Analyst consensus and price targets
Conclusion
Chipotle remains a well-recognised brand with a loyal customer base, a growing digital channel, and an expansion story — both domestically and internationally — that gives it credible medium-term growth levers. That said, the current valuation already prices in a meaningful degree of optimism, and near-term pressures on margins and comparable-sales growth are worth watching closely. Investors considering a position should weigh the broadly positive analyst consensus and momentum against a premium multiple at a time when earnings growth has yet to fully reassert itself.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 01-09-2026. Not investment advice.