
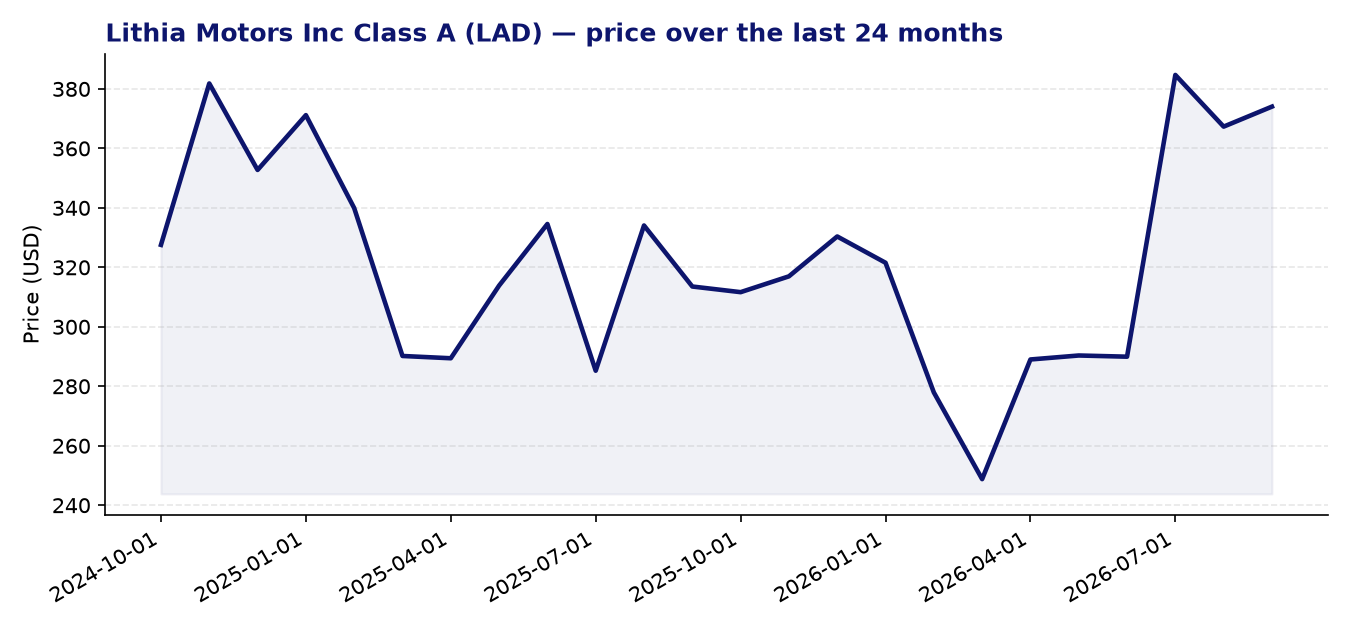
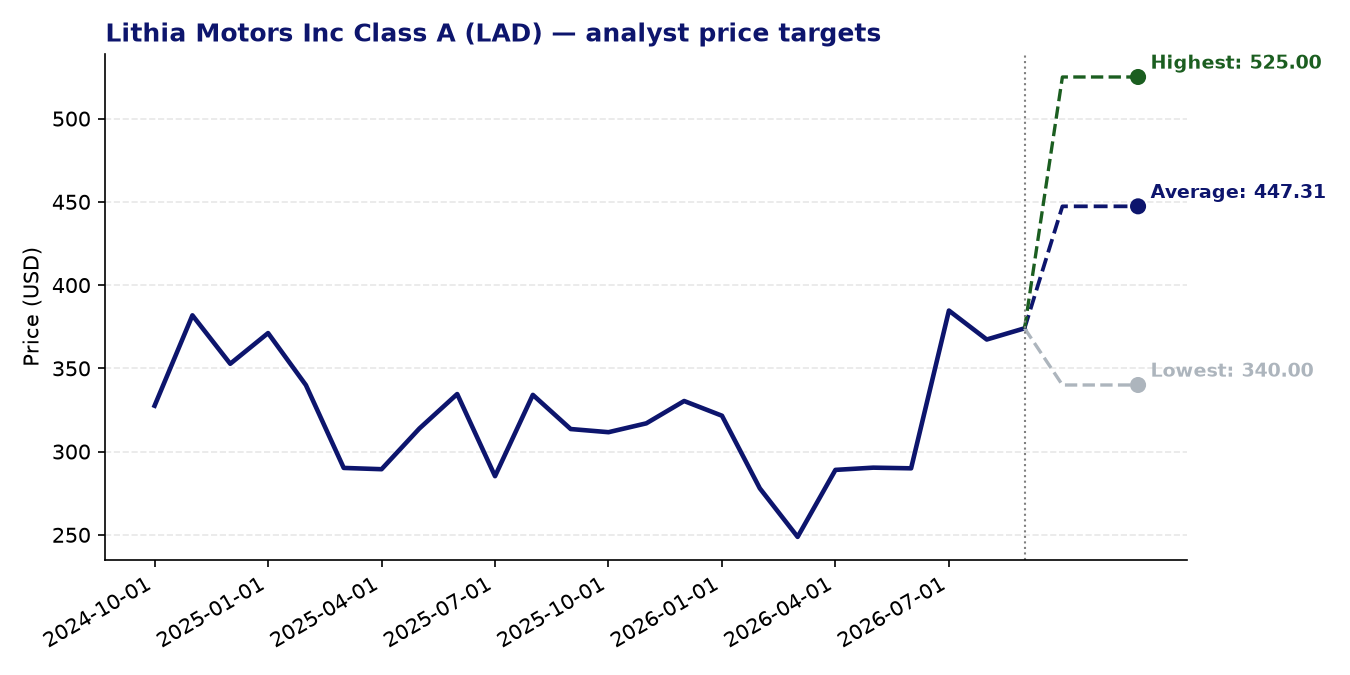
Lithia Motors Inc Class A (LAD) — current price: 374.06 USD | average price target: 447.31 USD | potential: +19.6%
About Lithia Motors Inc Class A
- Lithia Motors, founded in 1946 and headquartered in Medford, Oregon, is one of the largest automotive retailers in the United States, with additional operations in the United Kingdom and Canada.
- The company operates across two segments — Vehicle Operations and Financing Operations — covering the full vehicle ownership lifecycle from purchase to aftersales maintenance.
- Its product and service mix includes new and used vehicle sales, financing and insurance products, and automotive repair and maintenance services.
- Lithia reaches customers through a combination of physical dealership locations, e-commerce platforms under its Driveway brand, and captive finance solutions, reflecting a hybrid retail model.
Recent news
- Lithia reported Q2 2026 adjusted earnings per share of $10.03, comfortably ahead of the consensus estimate of around $8.67–$8.78, representing a roughly 9% increase on the prior-year quarter on an adjusted basis.
- The strong results triggered a roughly 20% intraday share price rally on 29 July 2026, pushing the stock to a record high and signalling a meaningful positive market re-rating.
- Alongside the earnings beat, management announced a 23% increase in the quarterly dividend, indicating confidence in the sustainability of the company’s cash generation.
- Reported net income for Q2 2026 came in at approximately $260 million, or $11.54 per share on a reported basis, with the gap to adjusted EPS reflecting non-recurring items.
Strengths
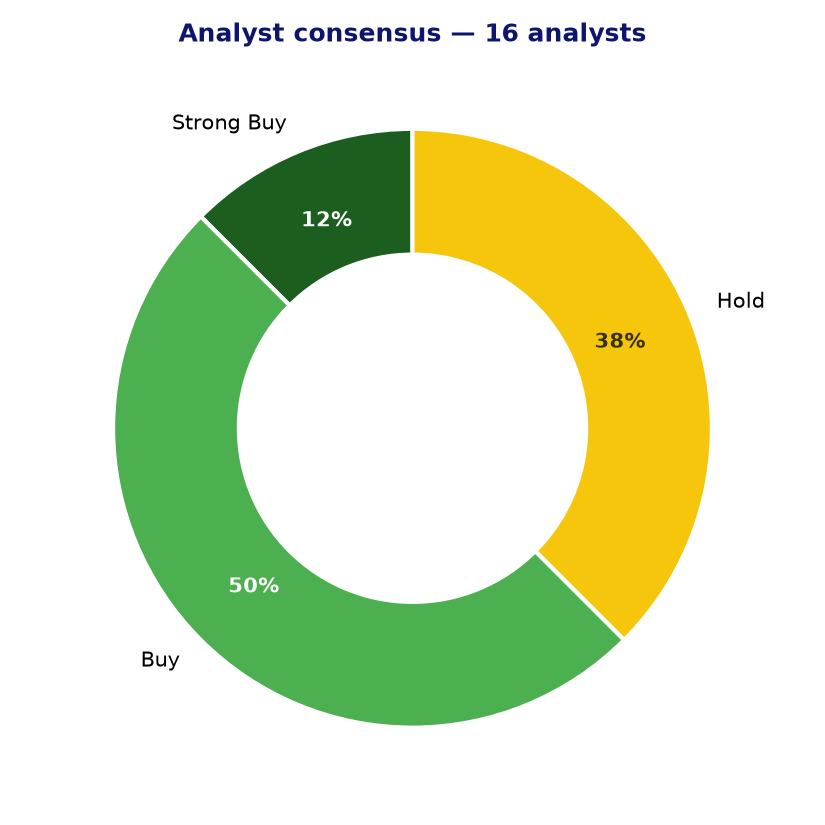
- Analyst sentiment is predominantly constructive: 10 of 16 covering analysts rate the stock a buy or strong buy, with an average price target of $447.31, implying roughly 19.6% upside from the current price of $374.06.
- A 24-month Z-score momentum reading of 2.39 suggests the stock has exhibited sustained positive price momentum relative to its history, which can be an indicator of continued institutional interest.
- Valuation metrics appear undemanding for a company of this scale: a trailing P/E of 12.4x and a forward P/E of 8.86x compare favourably within the consumer cyclical sector, while a PEG ratio of 0.77 suggests the stock may not be fully pricing in its growth prospects.
- The 23% dividend increase announced alongside Q2 results points to management’s confidence in the durability of free cash flow, and adds an income dimension to the investment case.
- Lithia’s diversified business model — spanning new and used vehicles, finance and insurance, aftersales, and digital channels — provides some resilience against weakness in any single revenue stream.
Points of attention and risks
- Underlying EPS growth is currently very modest, with the reported EPS growth figure near flat (0.01), and the Q2 adjusted EPS of $10.03 remains fractionally below the year-ago figure of $10.24 on a like-for-like basis.
- Auto dealerships are inherently cyclical and sensitive to consumer confidence, interest rate levels, and vehicle affordability — all of which remain under pressure in the current macroeconomic environment.
- Elevated interest rates continue to weigh on vehicle financing costs for consumers, which could dampen demand for new and used vehicles and compress margins in the financing segment.
- The lowest analyst price target of $340 sits below the current share price, a reminder that not all covering analysts share the bullish view, and downside scenarios exist if earnings momentum stalls.
- Following the post-earnings rally of approximately 20%, near-term expectations may already be elevated, potentially reducing the margin of safety for investors entering at current levels.
Analyst consensus and price targets
Conclusion
Lithia Motors enters the second half of 2026 with tangible operational momentum, having delivered a meaningful earnings beat alongside a significant dividend increase, and the stock’s valuation — on both a trailing and forward basis — remains relatively modest for a business of its scale and diversification. That said, the near-cyclical nature of auto retailing, subdued near-term EPS growth, and the sharp post-earnings re-rating all warrant careful consideration of entry timing and price. Investors with a longer-term horizon may find the combination of analyst consensus, valuation, and momentum metrics worth investigating further, while keeping an eye on the evolving consumer credit environment.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 02-09-2026. Not investment advice.