
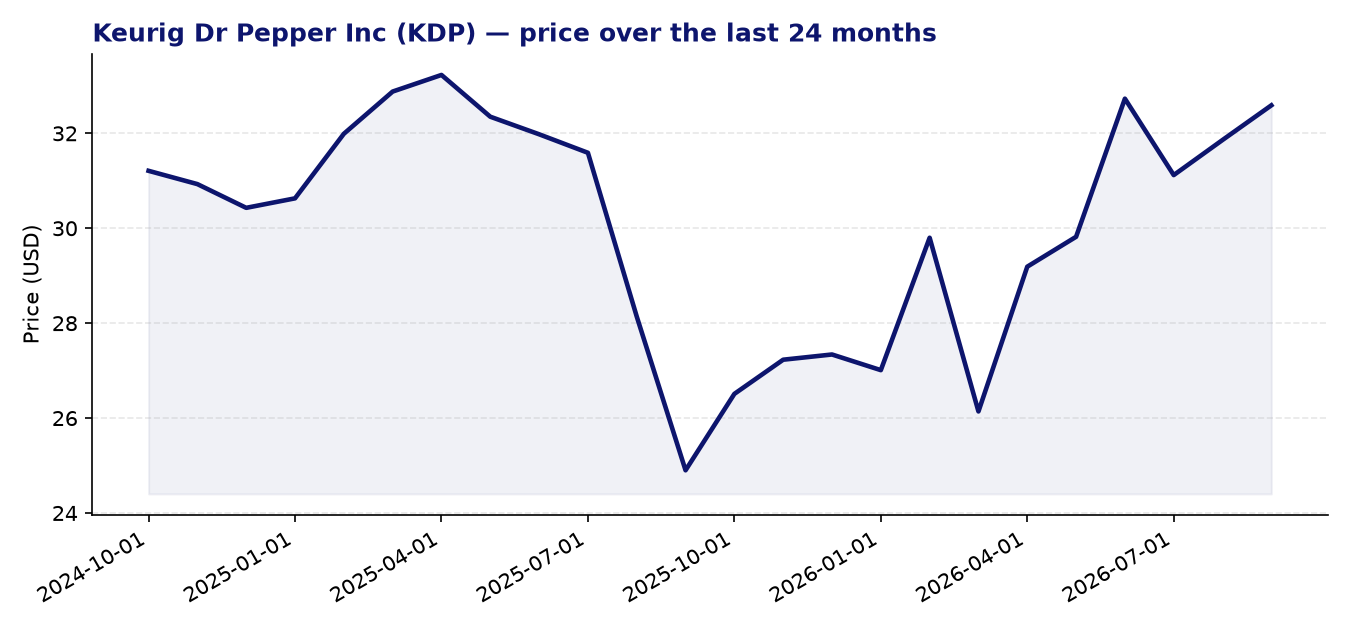
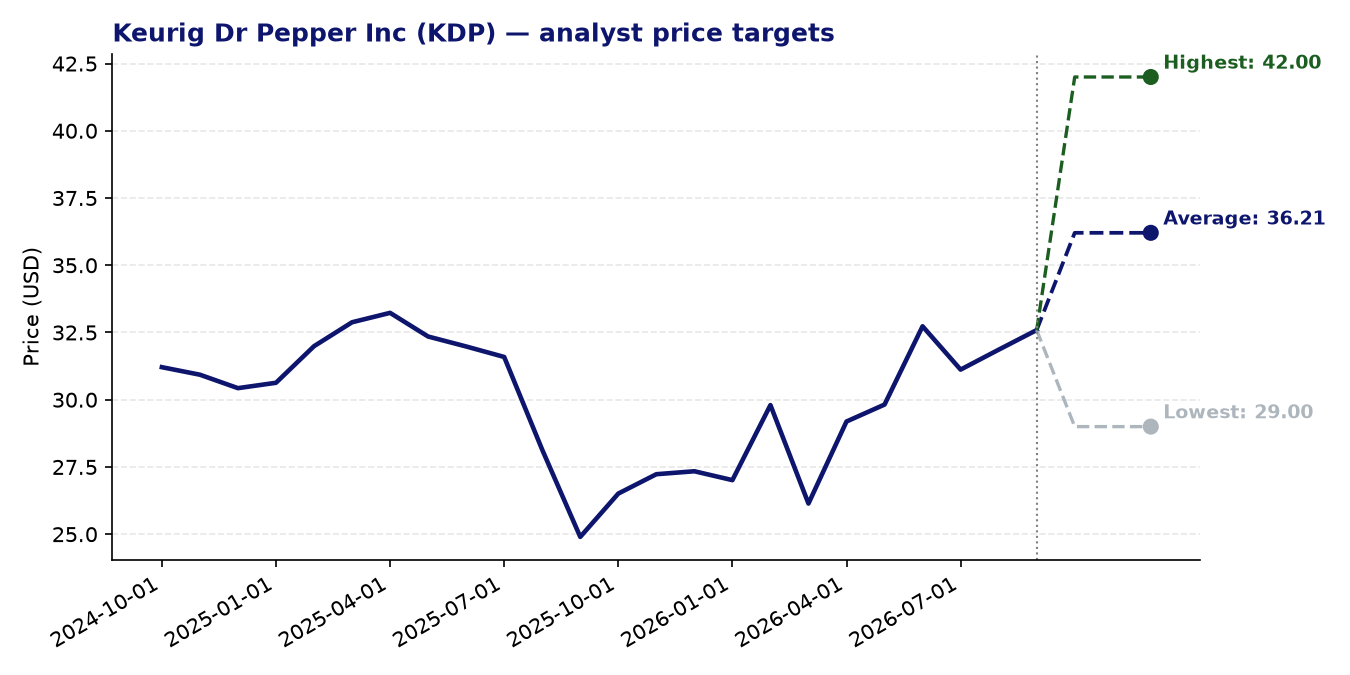
Keurig Dr Pepper Inc (KDP) — current price: 32.59 USD | average price target: 36.21 USD | potential: +11.1%
About Keurig Dr Pepper Inc
- Keurig Dr Pepper is a major US-headquartered beverage company operating across three segments: U.S. Refreshment Beverages, U.S. Coffee, and International.
- The company manufactures and distributes an extensive portfolio of soft drinks, juices, teas, energy drinks, and water brands, including Dr Pepper, Snapple, Canada Dry, Core Hydration, C4 Energy, and Electrolit.
- Its coffee division covers both at-home single-serve brewing systems (Keurig) and a wide range of licensed and owned coffee brands, such as Green Mountain, McCafé, Starbucks, Dunkin’, Peet’s, and Folgers K-Cup pods.
- Products are sold through a broad range of channels including supermarkets, convenience stores, vending, foodservice, e-commerce, and direct-to-consumer via Keurig.com.
Recent news
- KDP reported stronger-than-expected Q2 2026 earnings, with adjusted EPS of $0.57 coming in above the consensus estimate of $0.55 and meaningfully ahead of the $0.49 reported in the same quarter a year earlier.
- Total Q2 revenues surged approximately 76% year-on-year to $7.3 billion, largely reflecting the first-time consolidation of JDE Peet’s results into KDP’s financials — a significant structural change to the company’s earnings profile.
- The earnings beat drove a positive market reaction, with the stock rising in early trading following the results announcement in early August 2026.
Strengths
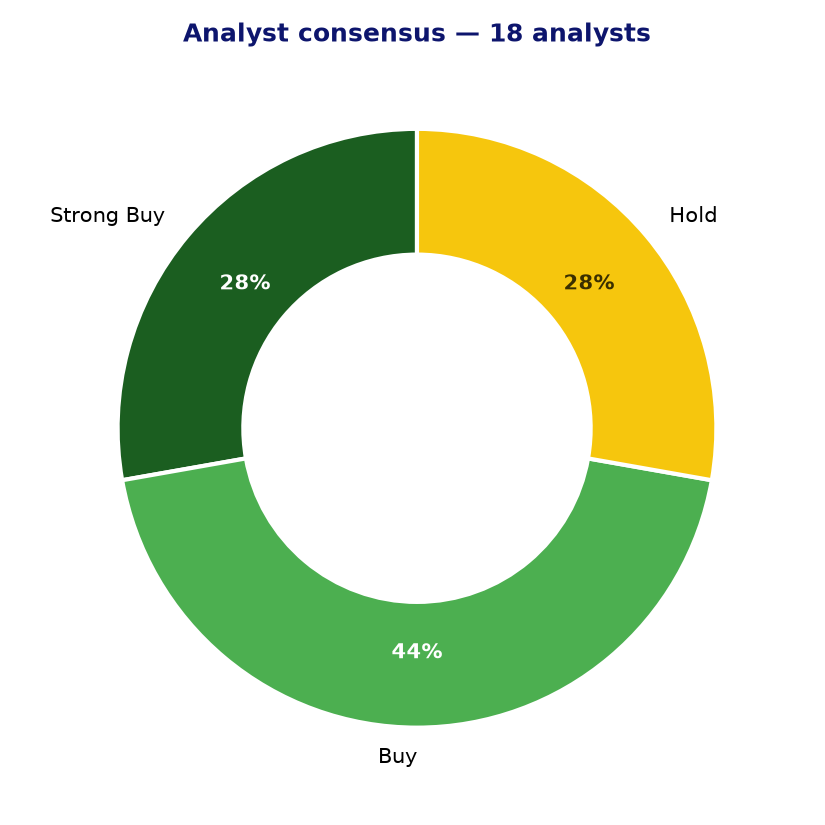
- Analyst sentiment is broadly constructive: of 18 covering analysts, 13 rate the stock a buy or strong buy, with none currently carrying a sell rating.
- The average price target of $36.21 implies approximately 11% upside from the current price of $32.59, with the most optimistic target reaching $42.00.
- A 24-month Z-score momentum reading of 2.40 suggests the stock has exhibited meaningful positive price momentum relative to its own history, which can be a supportive technical signal.
- The forward P/E of 12.86 and a PEG ratio of 0.98 suggest the market is not pricing in particularly demanding growth expectations, leaving room for re-rating if earnings delivery continues.
- The consolidation of JDE Peet’s materially expands KDP’s international coffee exposure, diversifying its revenue base and potentially improving long-term earnings quality.
Points of attention and risks
- The trailing P/E of 32.92 is elevated relative to the sector, and while the forward P/E is more reasonable, the gap reflects significant expected earnings growth that must materialise to justify current valuations.
- Reported EPS growth of -0.74% on a trailing basis is a point of caution, underscoring that headline earnings momentum has not yet been compelling outside of the recent beat.
- The JDE Peet’s consolidation, while strategically interesting, introduces integration complexity, potential goodwill and amortisation charges, and makes year-on-year comparisons less straightforward for at least the next several quarters.
- The consumer defensive beverage space faces ongoing cost pressures from input materials and logistics, as well as competitive intensity across both the soft drink and at-home coffee categories.
- The wide range between the lowest ($29.00) and highest ($42.00) analyst price targets reflects meaningful uncertainty about the company’s near-term earnings trajectory following the structural change in its consolidation perimeter.
Analyst consensus and price targets
Conclusion
Keurig Dr Pepper presents a mixed but broadly stable picture: a diversified beverage platform with a solid brand portfolio, a constructive analyst consensus, and a valuation that on a forward basis appears undemanding relative to peers. The integration of JDE Peet’s represents both the most significant near-term opportunity and the most important risk to monitor, given the scale of the change and the execution demands it places on management. Investors with a longer time horizon may find the combination of moderate upside potential and a forward valuation close to fair value worth examining further, while keeping close watch on how earnings develop as the consolidation matures.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 02-09-2026. Not investment advice.