
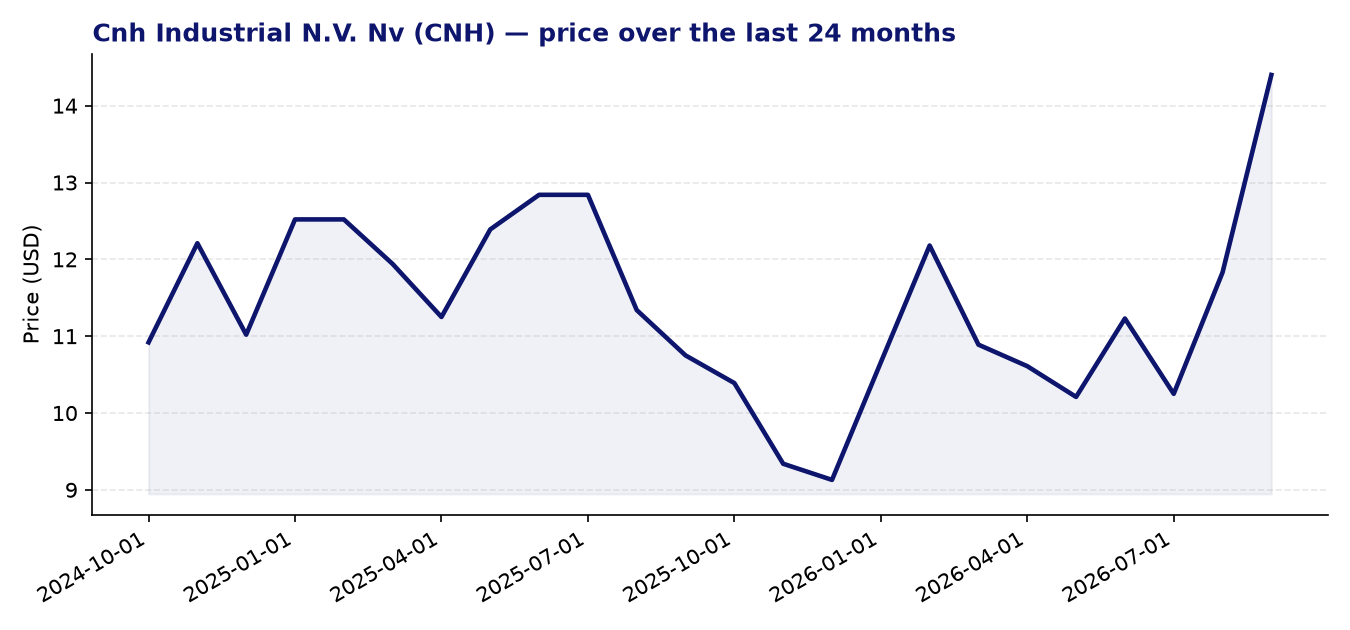
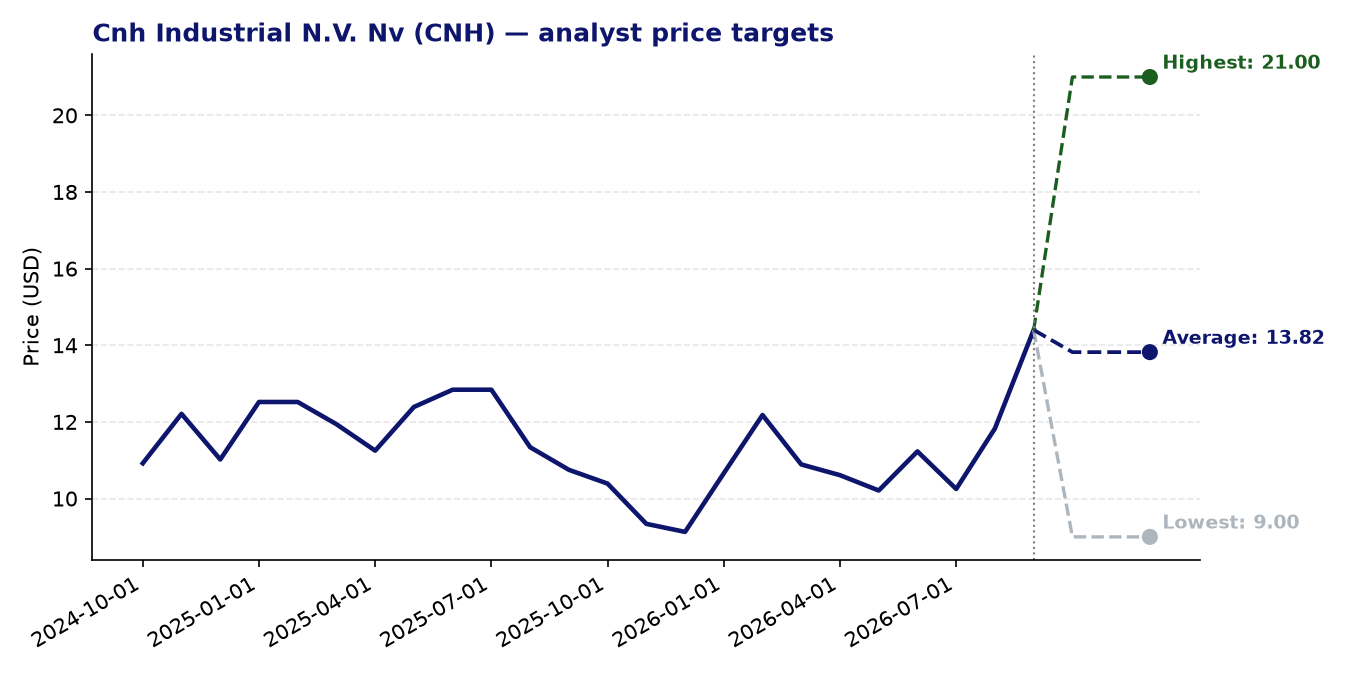
Cnh Industrial N.V. Nv (CNH) — current price: 14.40 USD | average price target: 13.82 USD | potential: -4.0%
About Cnh Industrial N.V. Nv
- CNH Industrial, founded in 1842 and headquartered in Basildon, UK, designs, manufactures, and sells agricultural and construction equipment across North America, Europe, the Middle East, Africa, South America, and Asia Pacific.
- Its Agriculture segment produces tractors, harvesters, sprayers, and precision farming solutions under the Case IH, New Holland, STEYR, and Raven brands.
- The Construction segment offers excavators, wheel loaders, graders, and compact track loaders under the Case Construction, New Holland Construction, and Eurocomach brands.
- A Financial Services segment complements the equipment business by providing retail financing, dealer wholesale funding, and trade receivables factoring under the Banco CNH brand.
Recent news
- CNH’s most recent quarterly earnings call highlighted a cautious operational picture, with management pointing to disciplined production and cost savings even as macroeconomic headwinds—including tariff pressures—weigh on both the Agriculture and Construction end markets.
- Q1 2026 revenues held broadly steady at approximately $3.83 billion, though core operating profitability came under pressure, prompting at least one analyst to reiterate a bearish stance with a notably low price target of $6.
- A separate Q2 2026 earnings update indicated some growth, though margin strain remained a concern, reflecting the difficult pricing and demand environment across CNH’s key segments.
- Analyst attention has been drawn to the stock trading near $11 earlier in the period, well below its current level, underscoring the volatility in market sentiment around the name.
Strengths
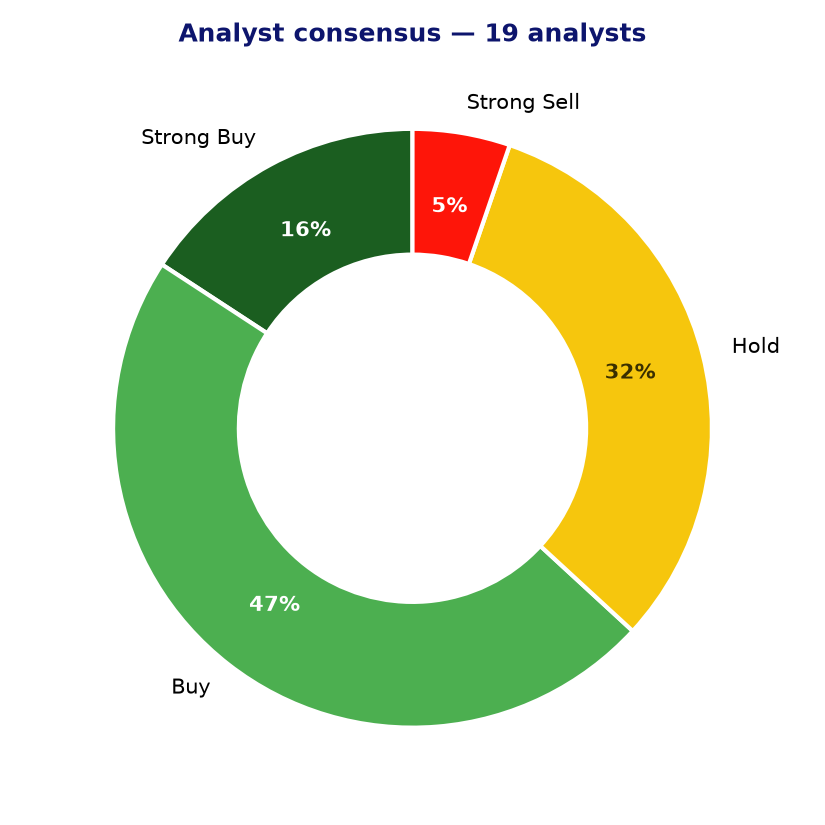
- The analyst community leans constructive overall, with 12 out of 19 analysts rating the stock a buy or strong buy, suggesting confidence in CNH’s medium-term recovery potential.
- A PEG ratio of 0.39 indicates that, relative to its expected earnings growth, the stock is not expensively priced on a growth-adjusted basis—potentially attractive for value-oriented investors.
- The forward P/E of approximately 21x is considerably more reasonable than the trailing P/E, implying the market anticipates a meaningful earnings recovery over the next twelve months.
- Z-score price momentum of 2.38 over a 24-month window suggests the stock has shown meaningful relative strength compared to its historical trend, which can be a supportive technical signal.
- CNH’s broad geographic diversification and multi-brand portfolio provide some resilience against region-specific demand downturns in either agriculture or construction.
Points of attention and risks
- The consensus average price target of $13.82 sits roughly 4% below the current price of $14.40, meaning the analyst community in aggregate does not see near-term upside from current levels.
- Trailing EPS growth is negative (-0.35), and the elevated trailing P/E of 57.6x reflects genuine current earnings weakness rather than a mispricing—investors are paying a premium while profitability is under pressure.
- Both the Agriculture and Construction segments face persistent end-market headwinds, including softening demand cycles, inventory normalisation, and cost pressures from tariffs that management acknowledged in recent guidance.
- The wide spread between the lowest ($9) and highest ($21) analyst price targets points to significant disagreement about CNH’s fundamental outlook, reflecting genuine uncertainty about earnings trajectory.
- The company operates in capital-intensive, cyclical industries where downturns can be prolonged; a financial services arm adds credit exposure that could amplify losses if equipment demand weakens materially.
Analyst consensus and price targets
Conclusion
CNH Industrial presents a mixed picture: a largely buy-rated stock with an attractive PEG ratio and recovering forward earnings estimates, set against a backdrop of genuine near-term earnings weakness, macro headwinds from tariffs, and a consensus price target that implies the shares are currently fairly to slightly fully valued. The gap between the trailing and forward earnings multiples is the key variable to watch—if management can deliver the profitability recovery the market is pricing in, the investment case strengthens considerably. Investors with a patient, cycle-aware outlook may find the risk-reward worth monitoring, though the lack of near-term consensus upside and elevated earnings uncertainty warrant careful position sizing.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 07-09-2026. Not investment advice.