
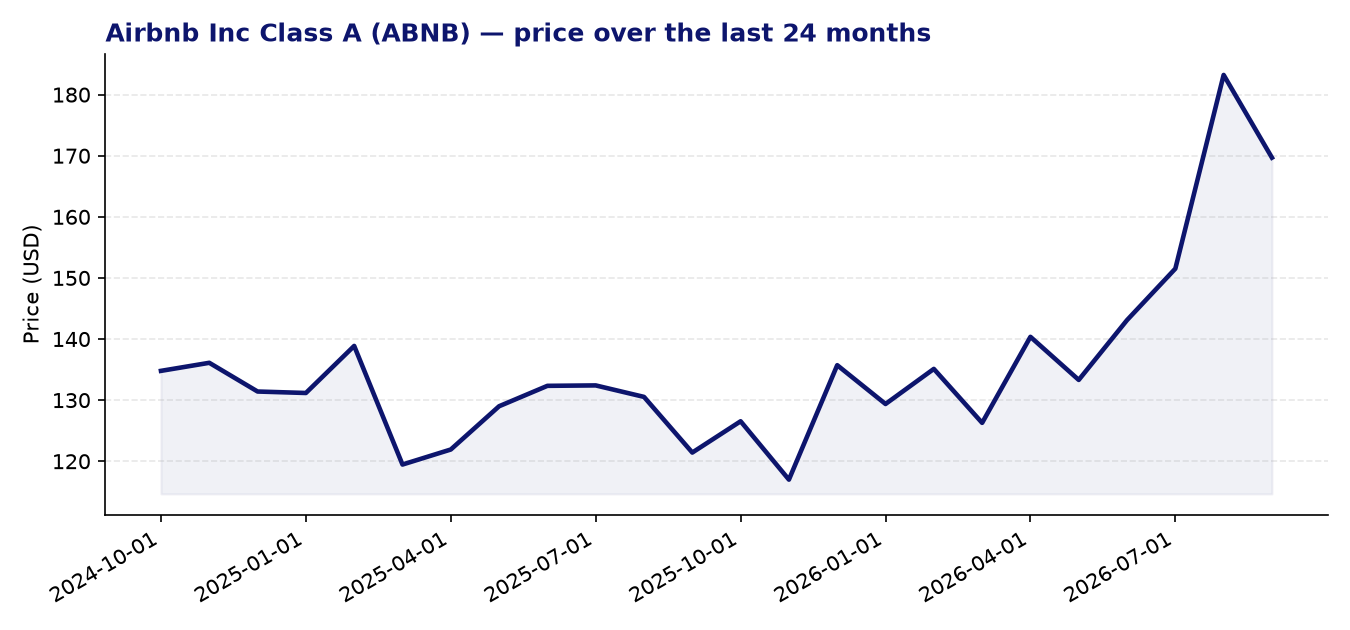
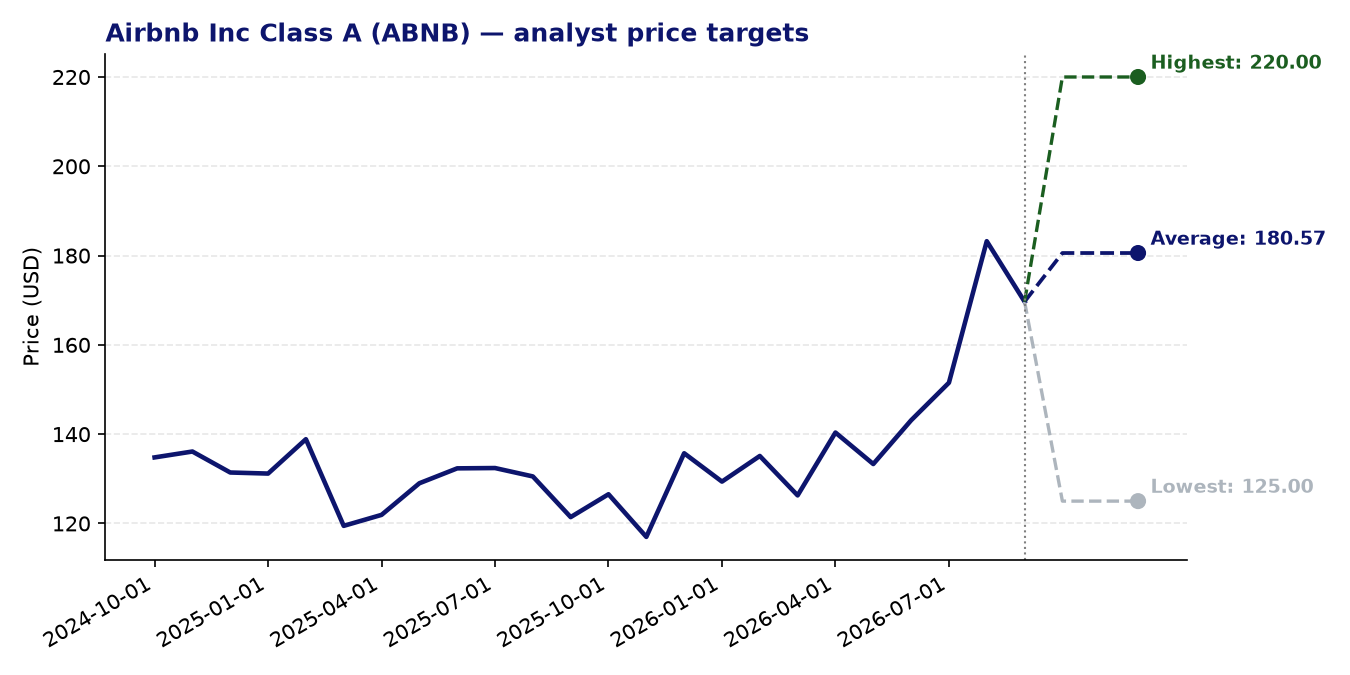
Airbnb Inc Class A (ABNB) — current price: 169.68 USD | average price target: 180.57 USD | potential: +6.4%
About Airbnb Inc Class A
- Airbnb operates a global online marketplace connecting hosts who offer short-term accommodation and experiences with guests seeking to book them, accessible via web and mobile.
- Founded in San Francisco in 2007, the platform serves both leisure and business travellers across a broad international footprint.
- Revenue is generated primarily through service fees charged to both hosts and guests on each completed booking.
- Beyond accommodation, the platform offers ‘Experiences’ — activity-based bookings led by local hosts — broadening its scope beyond pure lodging.
Recent news
- Airbnb reported Q2 2026 results that exceeded analyst expectations, with revenue rising 17% year-on-year, ahead of the company’s own 14–16% guidance range, and adjusted EBITDA up 21%.
- Earnings per share of $1.37 (adjusted) came in well above the consensus estimate of $1.20, and represented meaningful growth compared with $1.03 in the same quarter a year earlier.
- Management raised full-year revenue growth guidance to at least mid-teens, up from the previous low-to-mid-teens range, citing robust demand across all regions and accelerating room-night growth.
- The company’s AI-powered customer support assistant now resolves more than 40% of support queries without human intervention, contributing to a reported 10% reduction in cost per booking.
Strengths
- The Q2 2026 earnings beat and guidance upgrade triggered a sharp re-rating, with shares briefly reaching a fresh 52-week high near $184.70 and a strong post-earnings advance of roughly 10%.
- Momentum is firmly positive: a 24-month Z-score of 2.33 indicates the stock has been a consistent outperformer relative to its own history.
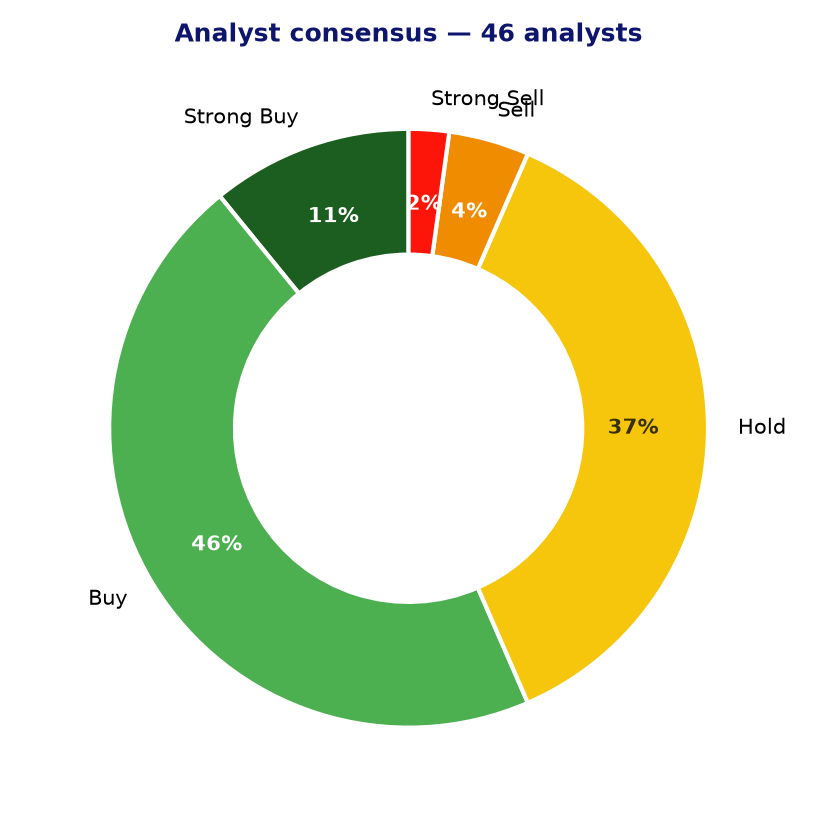
- The analyst community leans constructive, with 26 out of 46 analysts rating the stock a buy or strong buy and a consensus price target of $180.57, implying modest further upside from current levels.
- Accelerating room-night growth (10% in Q2 versus 9% in Q1) and strengthening demand across all geographies suggest the platform is sustaining rather than exhausting its growth trajectory.
- AI-driven cost efficiencies are beginning to flow through to margins, with cost-per-booking declining 10%, which supports EBITDA expansion even as the company invests in innovation.
Points of attention and risks
- At a trailing P/E of 38.7 and a PEG ratio of 1.73, the shares are not inexpensive; any disappointment in future growth or margins could weigh meaningfully on the valuation.
- The forward P/E of 27.6 is more palatable but still prices in continued execution; the wide range of analyst price targets ($125 to $220) reflects genuine uncertainty about where fair value lies.
- Airbnb operates in consumer cyclical travel services, making it sensitive to economic slowdowns, shifts in consumer spending, or any deterioration in discretionary income.
- Regulatory risk remains a structural overhang: short-term rental restrictions are tightening in several major cities and tourist destinations globally, which could constrain supply growth in key markets.
- With 17 hold ratings and 3 sell or strong sell ratings among 46 analysts, a meaningful portion of the market views the stock as fairly valued or stretched at current levels.
Analyst consensus and price targets
Conclusion
Airbnb’s Q2 2026 results were genuinely impressive, combining revenue growth well above guidance, expanding margins, and a raised full-year outlook — all of which reflect a business in good operational health. The platform’s scale, brand recognition, and emerging AI-driven cost advantages provide a credible foundation for further growth. That said, the valuation already reflects a degree of optimism, regulatory headwinds in key markets are a persistent risk, and the analyst community is far from uniformly enthusiastic. Investors considering ABNB will want to weigh the quality of recent momentum against a price that leaves limited room for execution shortfalls.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 09-09-2026. Not investment advice.