
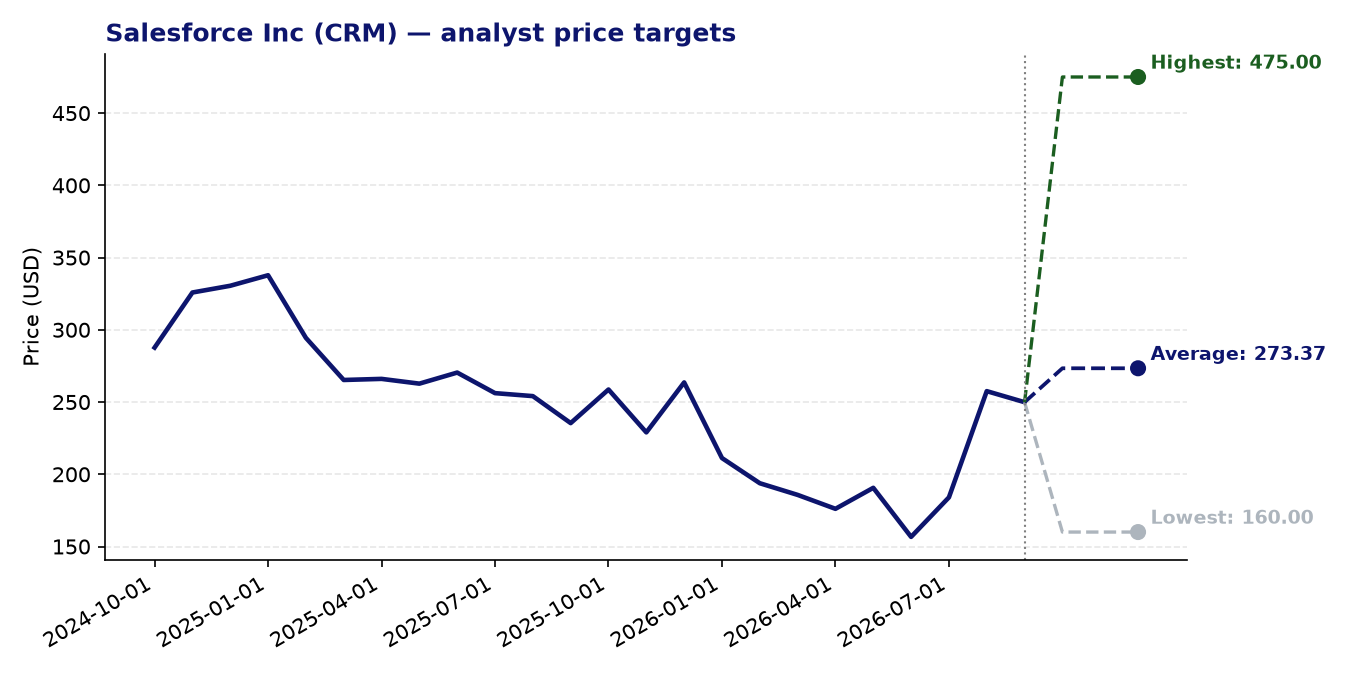
Salesforce Inc (CRM) — current price: 249.90 USD | average price target: 273.37 USD | potential: +9.4%
About Salesforce Inc
- Salesforce is a leading provider of cloud-based customer relationship management (CRM) software, serving businesses across the United States, Europe, and the Asia Pacific.
- Its flagship Agentforce platform allows enterprises to build, deploy, and manage autonomous AI agents that work alongside human teams across sales, service, and IT functions.
- The company also offers Slack, a real-time collaboration and workflow tool, and Data 360, a unified data engine designed to make business data actionable for both humans and AI agents.
- Salesforce serves a broad range of industries including financial services, healthcare, manufacturing, and government, and provides tailored solutions for small and medium-sized businesses through Salesforce Starter.
- The acquisition of Informatica adds AI-powered data management capabilities, strengthening Salesforce’s position in hybrid and multi-cloud data governance.
Recent news
- Salesforce reported strong fiscal Q2 FY2027 results, with revenue growing 11% year-on-year and subscription revenue up 12%, prompting management to raise full-year guidance.
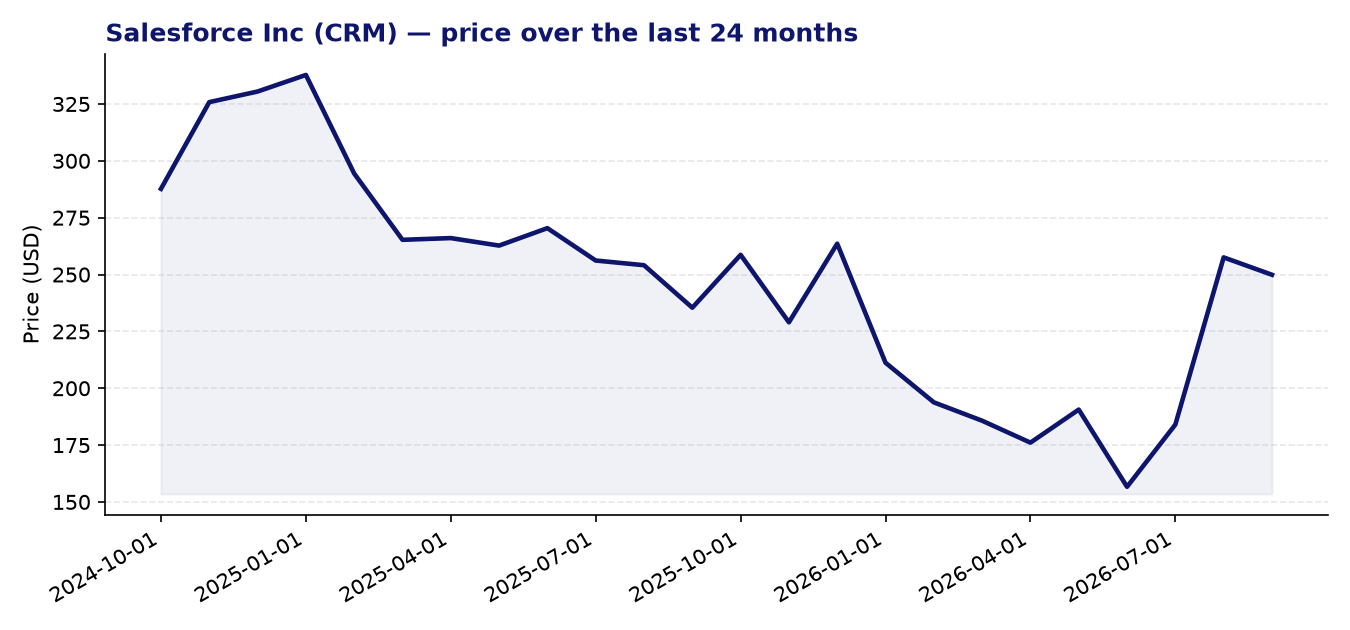
- The earnings release triggered a sharp single-day share price rise of over 20%, recovering much of the ground lost during a difficult stretch in which the stock had fallen around 24% from its prior high.
- Analysts are increasingly focused on AI credit consumption by Agentforce customers, with growing usage seen as a structural driver of future revenue acceleration.
- Ahead of earnings, Citi analyst Tyler Radke lifted his price target on the stock while maintaining a Neutral rating, citing incremental improvements in Agentforce deployment based on channel checks.
Strengths
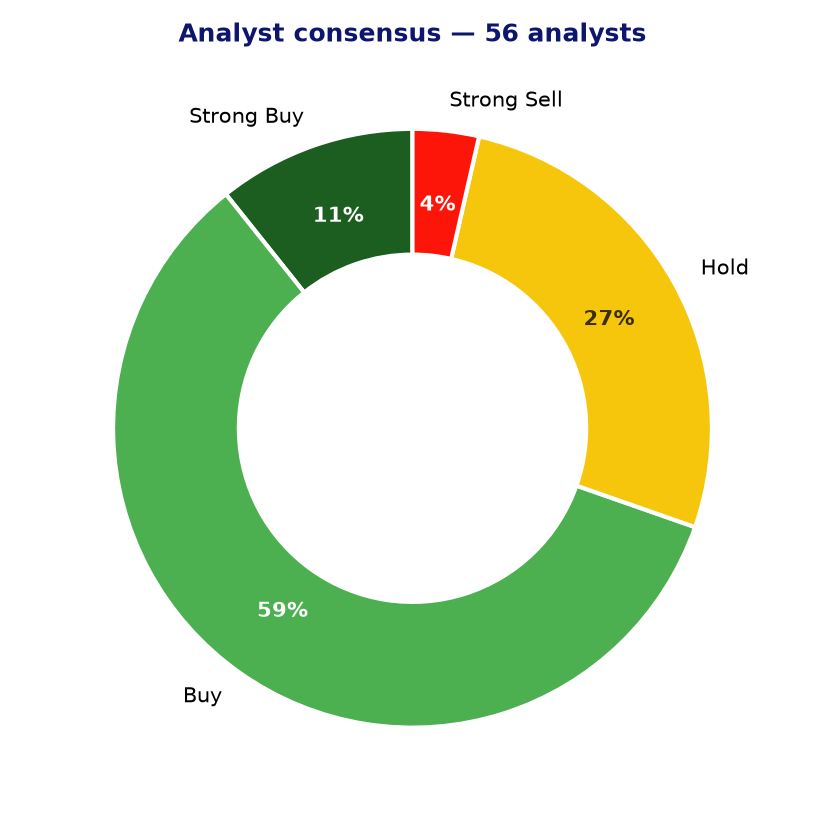
- The analyst community is broadly constructive, with 39 out of 56 covering analysts rating the stock a Buy or Strong Buy, and the consensus price target implying approximately 9.4% upside from current levels.
- Q2 FY2027 results were ahead of expectations, with double-digit revenue and subscription growth alongside raised full-year guidance, suggesting the business is executing well.
- A 24-month Z-score momentum reading of 2.19 indicates that the stock is displaying meaningful positive price momentum relative to its recent history.
- The forward P/E of 15.6x and PEG ratio of 1.05 suggest the market is not yet pricing in aggressive growth expectations, leaving room for valuation re-rating if Agentforce adoption accelerates.
- Increasing AI credit usage among existing customers points to a deepening monetisation opportunity within the installed base, without the need to win new accounts.
Points of attention and risks
- Despite the post-earnings bounce, the stock remains some distance below its peak and has had a difficult year overall, reflecting lingering uncertainty about the pace of enterprise AI adoption.
- The lowest analyst price target of $160 against a current price of ~$250 highlights meaningful disagreement among analysts, suggesting the bull case is far from universally accepted.
- EPS growth of 0.87 (below 1) raises a flag on near-term earnings momentum, and the transition to an AI-agent model introduces execution risk if monetisation takes longer than anticipated.
- Competition in enterprise software and AI tooling is intensifying, with rivals including Microsoft, ServiceNow, and Oracle all investing heavily in comparable agentic and CRM capabilities.
- Salesforce’s revenue growth, while solid, remains in the low double digits — not exceptional by the standards typically required to justify a premium technology multiple over the long term.
Analyst consensus and price targets
Conclusion
Salesforce enters a potentially important new chapter with its Agentforce platform beginning to generate measurable customer engagement, and the Q2 FY2027 results have gone some way to quieting concerns about the company’s growth trajectory. The valuation looks reasonable given the forward earnings multiple and PEG ratio, and broad analyst support adds some comfort. That said, execution risk around AI monetisation, a competitive landscape that is growing more crowded, and modest near-term EPS momentum mean investors will want to monitor how quickly Agentforce adoption translates into sustained revenue acceleration before drawing firm conclusions.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 09-09-2026. Not investment advice.