
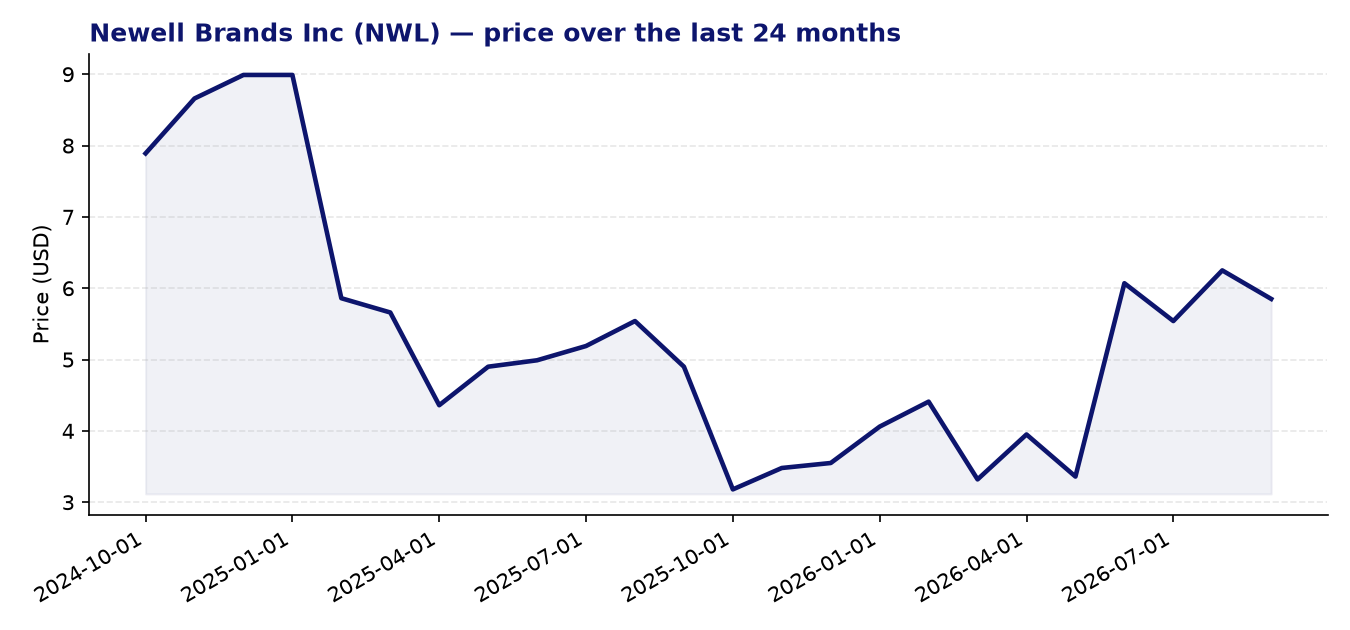
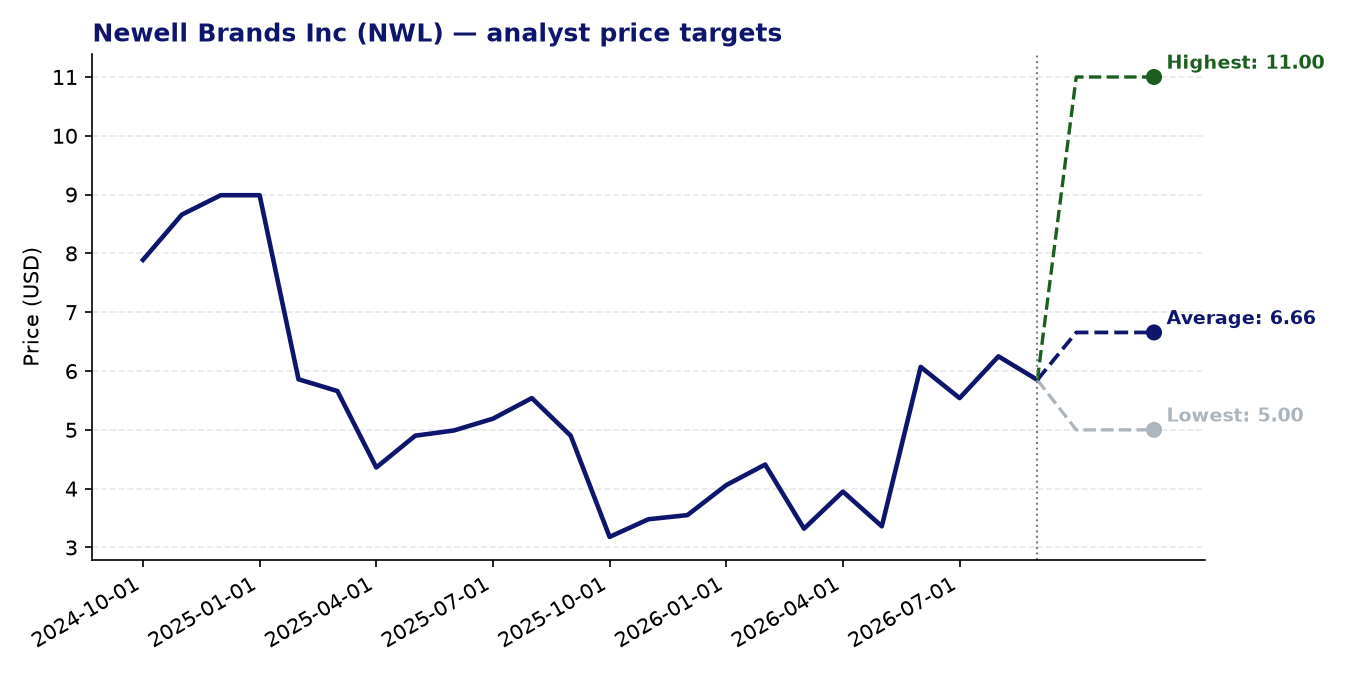
Newell Brands Inc (NWL) — current price: 5.85 USD | average price target: 6.66 USD | potential: +13.8%
About Newell Brands Inc
- Newell Brands is a diversified consumer goods company founded in 1903 and headquartered in Atlanta, Georgia, with operations spanning design, manufacture, sourcing, and distribution of products worldwide.
- The company operates three segments: Home and Commercial Solutions (kitchen appliances, food storage, home fragrance), Learning and Development (writing instruments, baby gear), and Outdoor and Recreation (camping, beverageware, technical apparel).
- Its brand portfolio includes well-known names such as Yankee Candle, Sharpie, Graco, Coleman, Rubbermaid, Mr. Coffee, and Marmot, among many others.
- Products are sold through a broad range of channels including mass merchandisers, warehouse clubs, e-commerce retailers, specialty stores, and direct-to-consumer platforms.
Recent news
- Recent commentary suggests that potential tariff refunds could provide a meaningful tailwind to Newell Brands’ near-term sales, with some analysts viewing the stock as undervalued relative to this catalyst.
- Multiple screeners and analyst tools have flagged NWL as a notable momentum stock over the past several months, pointing to strong short-term price appreciation even as longer-term holders remain underwater.
- Several value-focused analyses have highlighted NWL as a compelling candidate for value investors, citing its depressed valuation multiples relative to peers and the broader consumer sector.
Strengths
- The forward P/E of 8.52 and a PEG ratio of 0.97 suggest the stock is attractively valued relative to its near-term earnings growth, particularly for investors with a value-oriented approach.
- The analyst consensus average price target of $6.66 implies approximately 13.8% upside from the current price of $5.85, with the most bullish target reaching $11.00.
- A 24-month Z-score momentum reading of 2.11 indicates meaningful positive price momentum, which has historically been associated with continued near-term outperformance.
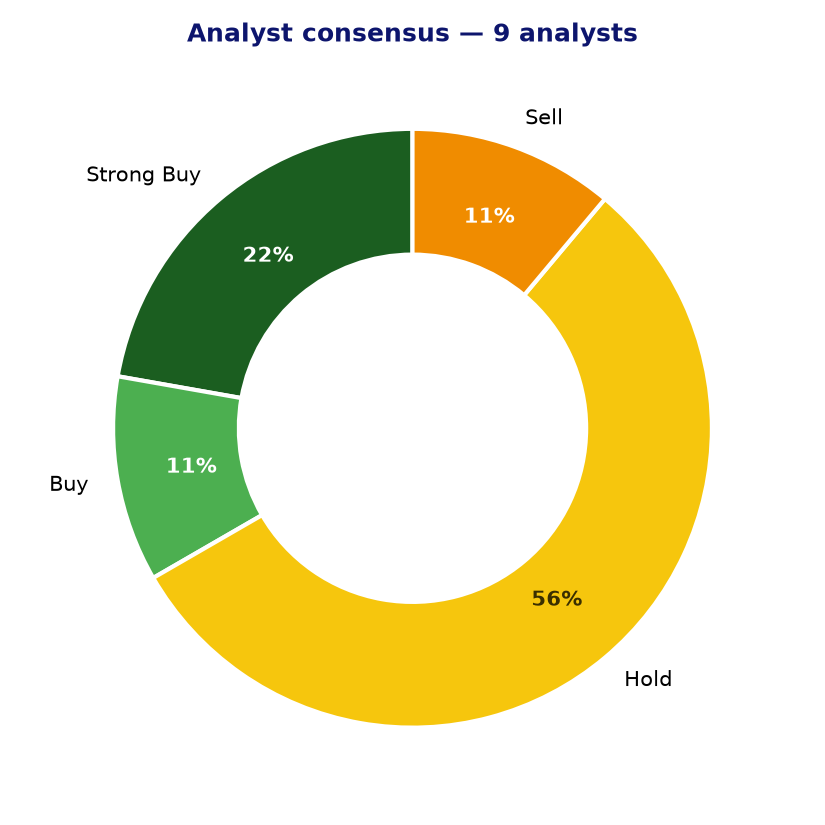
- Of the nine analysts covering the stock, three rate it a buy or strong buy with no strong sell ratings, suggesting a modestly constructive professional sentiment overall.
- The company’s diversified brand portfolio across multiple consumer categories provides some resilience against downturns in any single product segment or retail channel.
Points of attention and risks
- The absence of a trailing P/E ratio, combined with modest EPS growth of just 1.3%, points to ongoing pressure on profitability and limited near-term earnings recovery.
- Five of nine covering analysts maintain a hold rating and one rates it a sell, reflecting a degree of caution about the company’s ability to sustain improvement.
- The wide spread between the lowest ($5.00) and highest ($11.00) analyst price targets signals significant disagreement about the company’s fair value and near-term outlook.
- Newell Brands carries a substantial debt load accumulated through past acquisitions, which constrains financial flexibility and heightens sensitivity to any deterioration in operating cash flow.
- As a consumer goods company with broad exposure to discretionary and semi-discretionary spending, NWL remains vulnerable to shifts in consumer sentiment, input cost inflation, and ongoing tariff-related uncertainty.
Analyst consensus and price targets
Conclusion
Newell Brands presents an interesting case for investors comfortable with turnaround situations: its valuation metrics are undemanding, momentum indicators have recently turned positive, and potential tariff-related tailwinds could support near-term revenue. However, the thin earnings growth, heavy debt burden, and notable analyst disagreement are reminders that the path to sustained recovery is far from straightforward. Investors should weigh the cheap headline valuation carefully against the structural challenges still facing the business.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 14-09-2026. Not investment advice.