
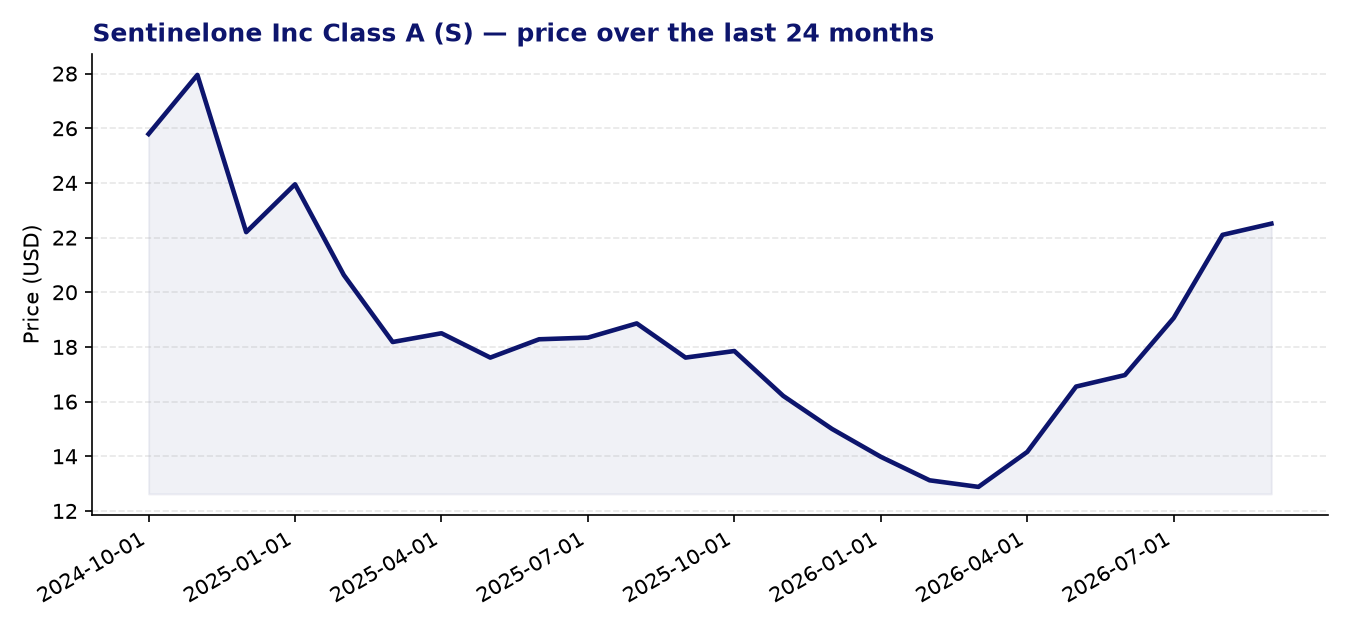
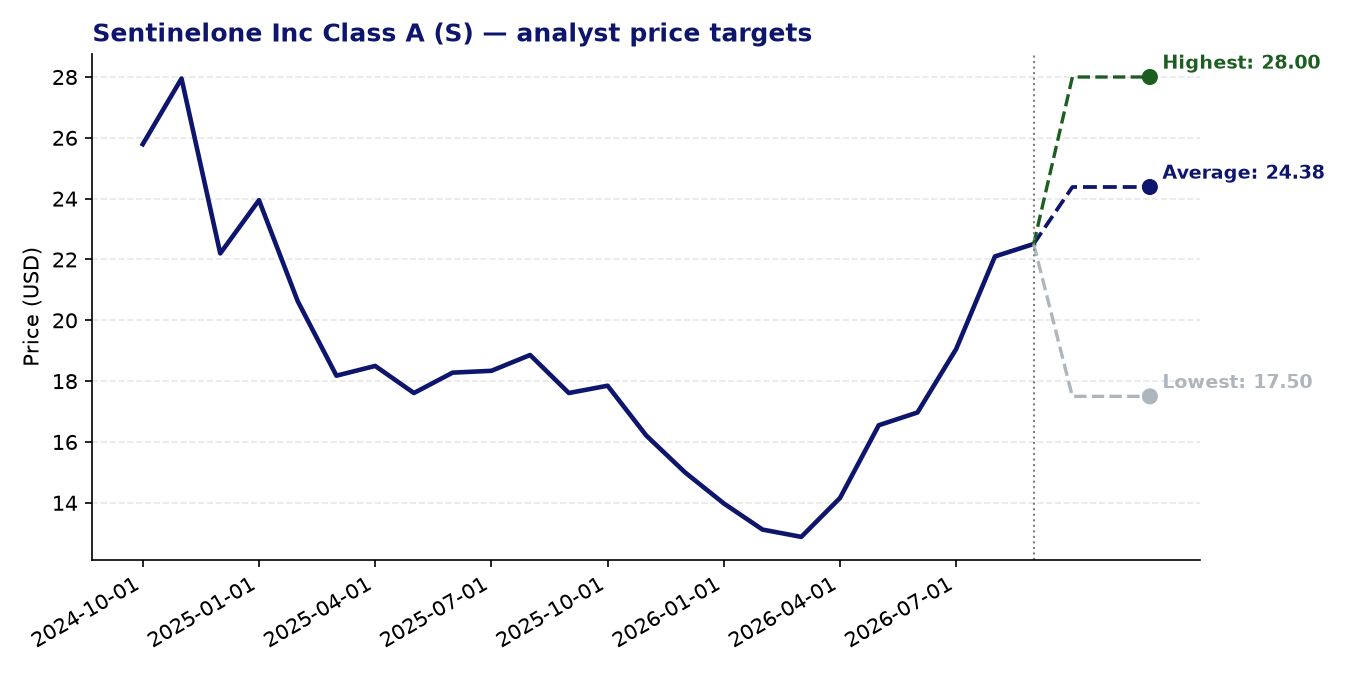
Sentinelone Inc Class A (S) — current price: 22.51 USD | average price target: 24.38 USD | potential: +8.3%
About Sentinelone Inc Class A
- SentinelOne operates an AI-powered cybersecurity platform called Singularity, which provides autonomous threat prevention, detection, and response across endpoints, cloud workloads, and identity credentials.
- The company’s product suite includes endpoint security, cloud security, identity security, exposure management, and a generative AI security agent branded as Purple AI.
- SentinelOne has a collaboration with Amazon Web Services to deliver unified AI governance for customers building on Amazon Bedrock.
- Founded in 2013 and headquartered in Mountain View, California, the company serves customers in the United States and internationally.
Recent news
- SentinelOne’s fiscal Q2 2027 results beat consensus estimates, with revenue growing 21% year-over-year to $292 million and adjusted operating margins expanding by 800 basis points to 10%.
- Annual recurring revenue reached $1.218 billion, representing 22% growth, while adjusted earnings per share of $0.08 exceeded the consensus estimate of $0.07 and doubled the year-ago figure.
- Despite the earnings beat, shares fell approximately 8.5% on the results day, as a reduced full-year profit outlook and slower growth in large customer additions dampened investor sentiment.
- Prior to the earnings release, a ratings downgrade from one research outlet flagged that the stock’s strong year-to-date run had left it trading at a premium valuation, with much of the sector’s positive tailwinds potentially already reflected in the price.
Strengths
- Revenue and earnings both surpassed analyst expectations in the most recent quarter, with ARR growing 22% to over $1.2 billion, demonstrating continued commercial momentum.
- Adjusted operating margins expanded significantly, suggesting the business is making meaningful progress toward profitability even as it continues to invest in growth.
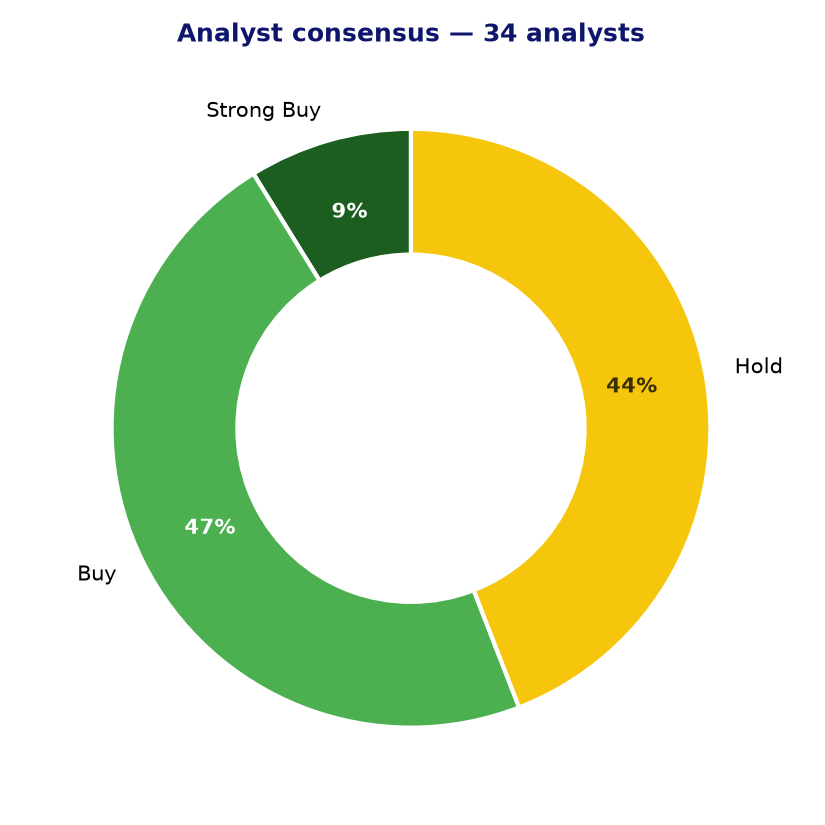
- The analyst community remains broadly constructive: of 34 analysts covering the stock, 19 rate it a buy or strong buy, with no sell ratings, and the average price target implies around 8% upside from the current price.
- The 24-month Z-score momentum reading of 2.57 indicates the stock has shown notably strong relative price performance, suggesting sustained positive market recognition.
- Structural demand for AI-driven cybersecurity solutions continues to grow as organizations face increasingly sophisticated threats, providing a supportive long-term backdrop for SentinelOne’s platform.
Points of attention and risks
- The forward P/E of approximately 49x reflects a premium valuation that leaves limited room for disappointment, and the stock’s 42% year-to-date gain prior to earnings may already have priced in considerable good news.
- The company does not yet report a meaningful trailing P/E or PEG ratio, as earnings on a GAAP basis remain absent, making traditional valuation comparisons more difficult.
- Slowing growth in large enterprise customer additions, highlighted during the most recent earnings call, is a metric worth watching closely, as this segment is typically key to long-term revenue durability.
- Management’s decision to reduce its full-year profit outlook spooked markets despite the headline earnings beat, indicating that near-term profitability expectations may be difficult to sustain at the pace investors had anticipated.
- Competition in the cybersecurity platform space is intense, with larger, better-resourced incumbents such as CrowdStrike and Microsoft continuously expanding their own AI-driven security offerings.
Analyst consensus and price targets
Conclusion
SentinelOne presents a compelling growth story underpinned by genuine product innovation, improving operating leverage, and robust demand for AI-powered cybersecurity. However, the premium valuation, post-rally share price, and a trimmed full-year profit outlook introduce a degree of execution risk that warrants careful consideration. The broadly positive analyst consensus and strong momentum are encouraging, but investors should weigh these against the stock’s sensitivity to any further guidance revisions or signs that large-customer growth is decelerating. This is a company with credible long-term potential that, at current prices, appears to offer a more modest near-term margin of safety.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 19-09-2026. Not investment advice.