
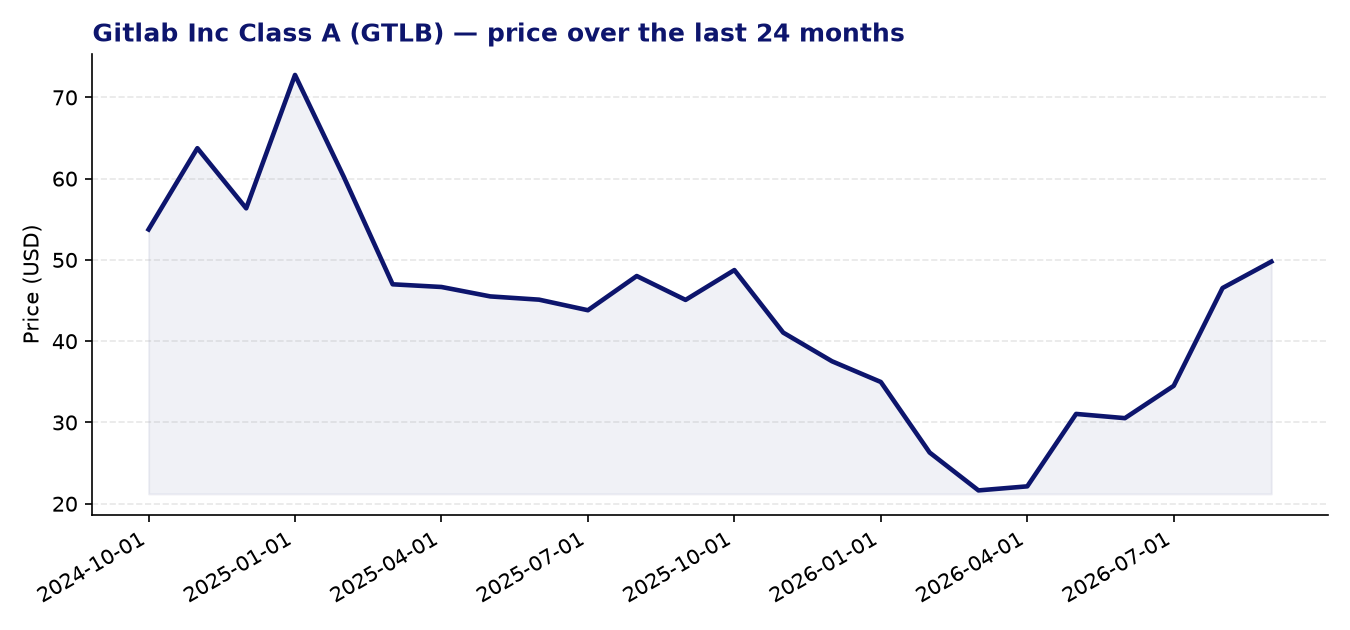
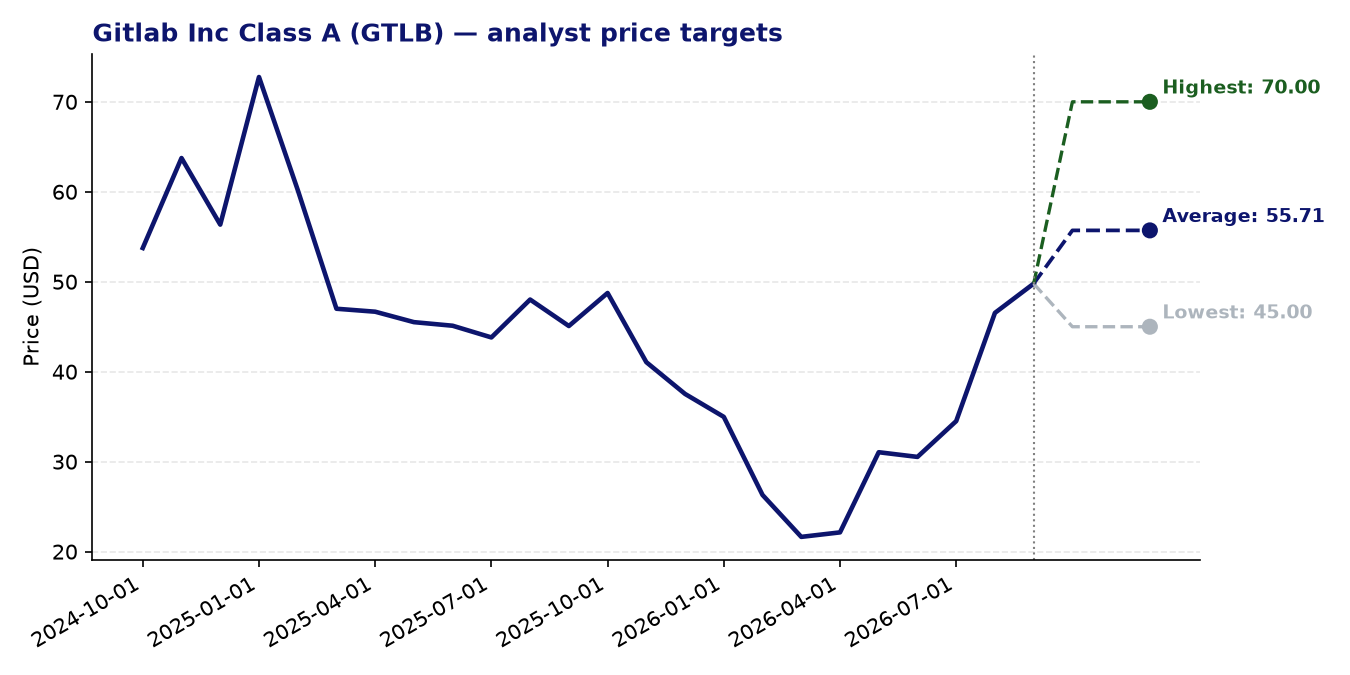
Gitlab Inc Class A (GTLB) — current price: 49.79 USD | average price target: 55.71 USD | potential: +11.9%
About Gitlab Inc Class A
- GitLab operates a unified DevSecOps platform covering the entire software development lifecycle, from project planning and coding through to security scanning, compliance, and deployment.
- Its core product consolidates tools that organisations would otherwise source from multiple vendors, positioning GitLab as a single-application alternative in a fragmented market.
- The company recently launched the GitLab Duo Agent Platform, which layers AI-driven orchestration onto its existing toolset, enabling autonomous task execution across development and security workflows.
- GitLab serves customers in the United States, Europe, and the Asia-Pacific region, with both self-managed and SaaS subscription models, supplemented by professional services and training.
Recent news
- GitLab’s most recent quarterly results beat analyst expectations on both earnings per share and revenue, with the stock responding sharply higher on the day of the announcement.
- The quarter was notably strong on new business: first-order customer additions more than doubled, representing the best new-customer intake in three years, while sales productivity and gross bookings reached record levels.
- Management issued full-year earnings guidance that came in well ahead of the existing analyst consensus, suggesting confidence in near-term profitability momentum.
- Some analysts have flagged that beneath the headline beat, revenue growth has been decelerating for two consecutive quarters, prompting a more cautious read of the results from certain market commentators.
Strengths
- The analyst community’s average price target of $55.71 implies approximately 11.9% upside from the current price of $49.79, with the most optimistic target reaching $70.00.
- A 24-month Z-score momentum reading of 2.95 indicates that GTLB’s price trend is meaningfully above its historical average, reflecting sustained positive market interest.
- Record new-customer acquisition and doubling of first-order volumes in the latest quarter point to a healthy top-of-funnel and improving commercial execution.
- The company’s full-year EPS guidance of $0.85–$0.87 substantially exceeds the prior analyst consensus of $0.61, suggesting management has visibility into a meaningful step-up in profitability.
- GitLab’s integrated, single-platform approach and the addition of AI agent capabilities through Duo position it well to capitalise on enterprise demand for consolidating fragmented development toolchains.
Points of attention and risks
- Revenue growth has decelerated in each of the past two quarters, which raises questions about whether the top-line acceleration needed to justify the valuation will materialise.
- With a forward P/E of approximately 48x and no current P/E or PEG ratio calculable, the stock carries a demanding valuation that leaves limited room for operational disappointment.
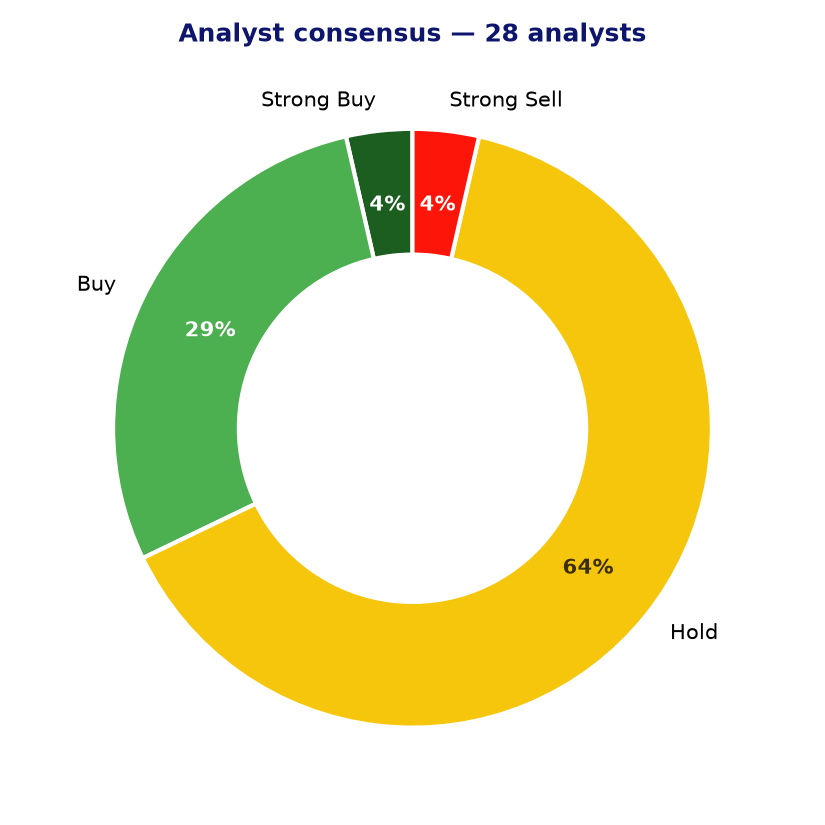
- Analyst sentiment is predominantly neutral, with 18 of 28 analysts rating the stock a hold; only 9 carry a buy or strong buy rating, and one analyst has a strong sell, indicating divided conviction.
- The lowest price target of $45.00 sits below the current share price, a reminder that a segment of the analyst community sees downside risk at present levels.
- The DevSecOps and software infrastructure space is increasingly competitive, with large platform vendors and specialist players alike investing heavily in AI-assisted development tools that could pressure GitLab’s differentiation over time.
Analyst consensus and price targets
Conclusion
GitLab presents a compelling long-term story anchored in platform consolidation and AI-enhanced developer tooling, and its recent quarter demonstrated genuine commercial momentum in new customer acquisition and profitability guidance. However, the decelerating revenue growth trend sits somewhat uneasily alongside a forward earnings multiple approaching 48x, and the broadly neutral analyst consensus suggests that much of the near-term optimism may already be reflected in the current price. Investors may find it worthwhile to monitor whether the new-customer pipeline translates into sustained top-line reacceleration before drawing firmer conclusions about the risk-reward balance.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 22-09-2026. Not investment advice.