
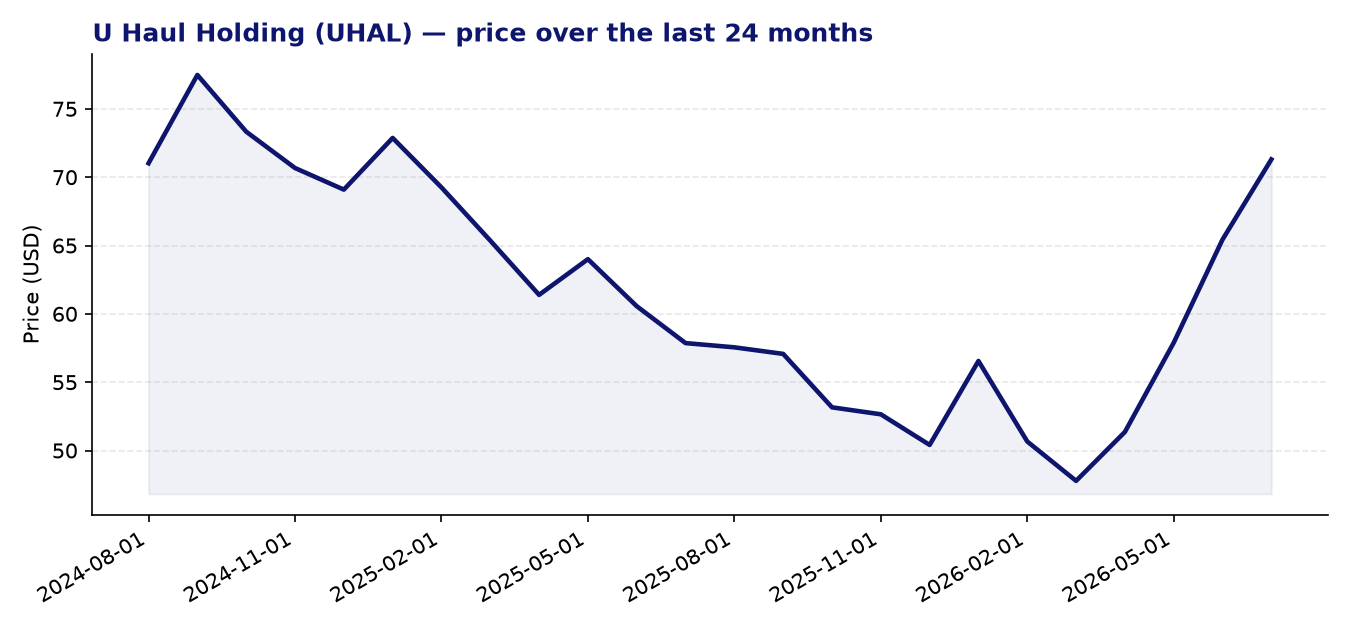
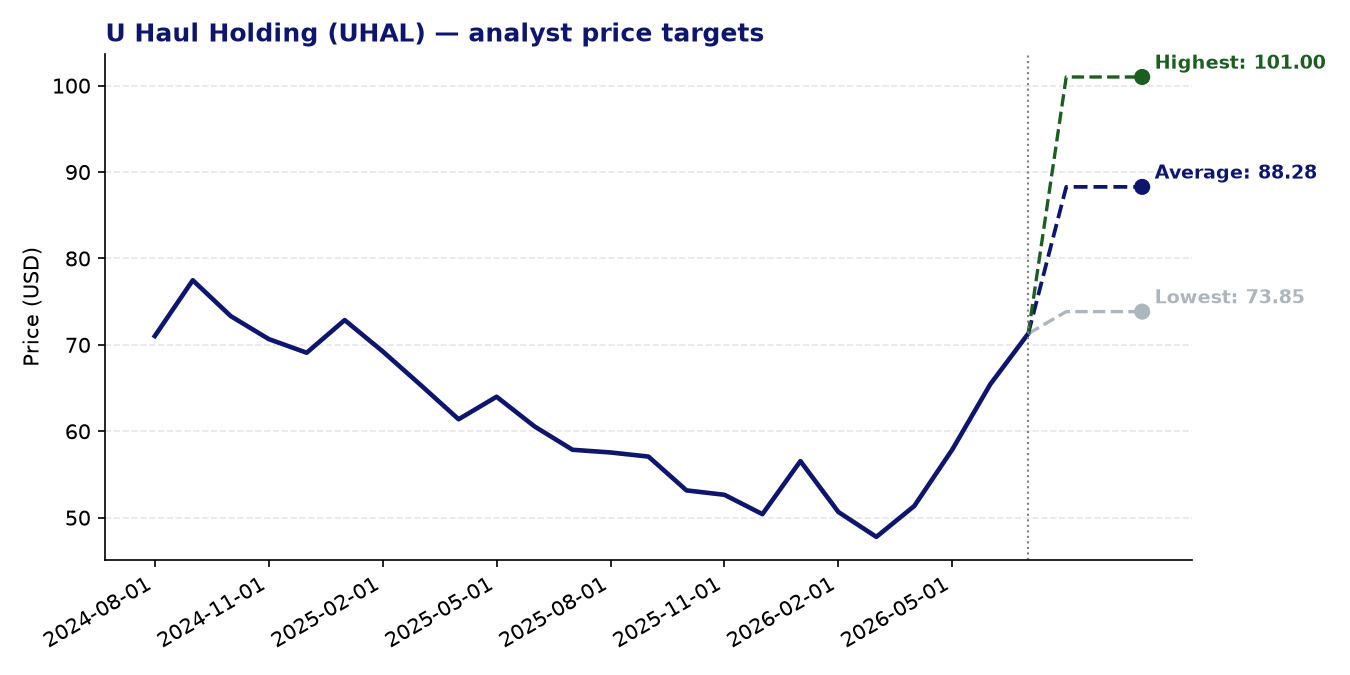
U Haul Holding (UHAL) — current price: 71.30 USD | average price target: 88.28 USD | potential: +23.8%
About U Haul Holding
- U-Haul Holding Company, founded in 1945 and headquartered in Reno, Nevada, is North America’s leading do-it-yourself moving and storage operator, serving both household and commercial customers across the United States and Canada.
- Its core Moving and Storage segment rents trucks, trailers, portable U-Box units, and self-storage spaces through a network of managed retail stores and thousands of independent dealers.
- The company also sells moving supplies, towing accessories, and propane, and operates uhaul.com as an online marketplace connecting customers to independent moving-help providers and self-storage affiliates.
- Two additional business segments — Property and Casualty Insurance and Life Insurance — broaden revenues through protection packages, cargo coverage, Medicare supplement plans, and annuity products targeted at the senior market.
Recent news
- U-Haul reported full-year fiscal 2026 net earnings of approximately $83 million, a steep decline from the roughly $367 million posted in the prior fiscal year, reflecting a significant compression in profitability.
- The company recorded two consecutive quarters of negative non-GAAP EPS, and revenue growth has been nearly flat, raising questions about the pace of any near-term earnings recovery.
- Despite the earnings weakness, U-Haul appears on some analyst screens as a stock with meaningful price-target upside, suggesting at least a portion of the market views the downturn as cyclical rather than structural.
Strengths
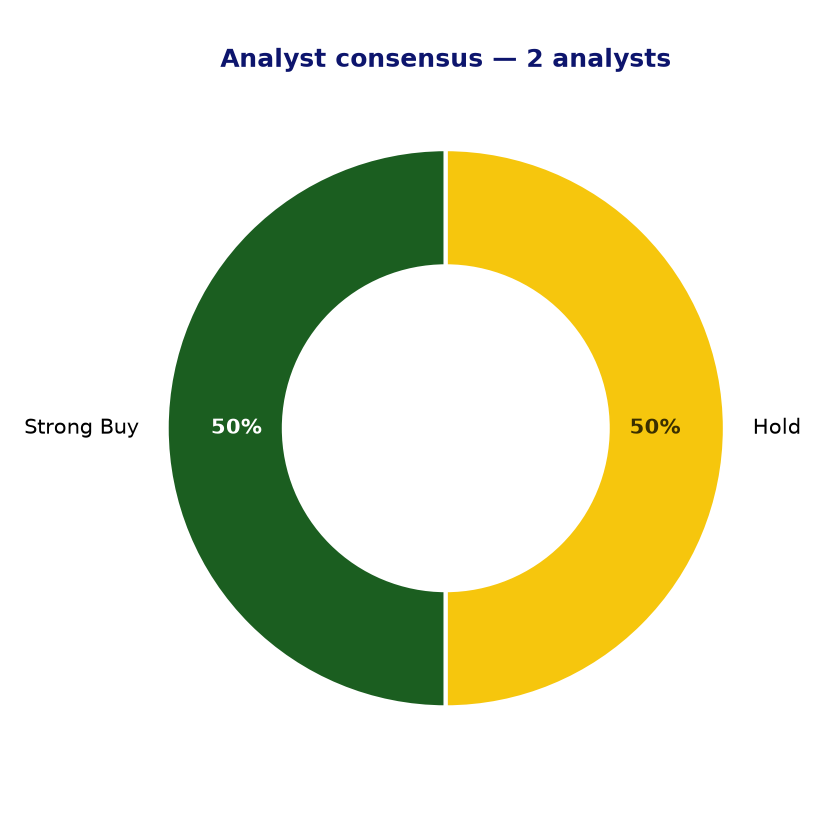
- The average analyst price target of $88.28 implies approximately 23.8% upside from the current price of $71.30, and the sole strong-buy rating suggests at least some conviction among covering analysts.
- A 24-month Z-score momentum reading of 2.56 indicates that the stock’s price momentum is statistically elevated relative to its own history, which can be a constructive technical signal.
- U-Haul’s brand recognition and its vast, difficult-to-replicate network of trucks, trailers, dealers, and storage facilities represent durable competitive advantages that are not easily challenged by new entrants.
- The forward P/E of 33.6x — considerably lower than the trailing P/E — implies that analysts expect a meaningful earnings recovery, and if achieved, the current share price would represent a more reasonable valuation entry point.
- Diversification across moving equipment rental, self-storage, and two insurance segments provides some revenue stability even when any single line faces cyclical headwinds.
Points of attention and risks
- The trailing P/E of approximately 297x reflects the severity of the current earnings collapse and makes the stock look very expensive on reported earnings; investors are essentially paying for a recovery that has yet to materialise.
- Full-year net income dropped by roughly 77% year-on-year to $83 million, and two consecutive quarters of negative non-GAAP EPS signal that near-term profitability remains under meaningful pressure.
- Revenue growth is effectively flat, pointing to limited top-line momentum at a time when earnings need to recover — the combination leaves little margin for error if the macro or housing environment deteriorates further.
- Analyst coverage is very thin at just two analysts, which limits the reliability of consensus estimates and price targets; a single rating change could materially shift the apparent consensus picture.
- A PEG ratio of 2.35 suggests the stock is not obviously cheap even relative to its expected growth rate, and with EPS growth currently reported as negligible, the growth assumptions underpinning that figure carry execution risk.
Analyst consensus and price targets
Conclusion
U-Haul Holding possesses genuine long-term strengths — a dominant brand, an extensive North American network, and business-segment diversification — that distinguish it from smaller competitors. However, the dramatic decline in fiscal 2026 earnings, flat revenue growth, and a stretched trailing valuation mean the investment case rests heavily on a recovery in profitability that is not yet visible in the reported numbers. The limited analyst coverage adds an extra layer of uncertainty around consensus estimates, and prospective investors would do well to monitor upcoming quarterly results closely for early signs that the earnings trajectory is genuinely turning before drawing firm conclusions about the stock’s risk-reward balance.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 20-07-2026. Not investment advice.