
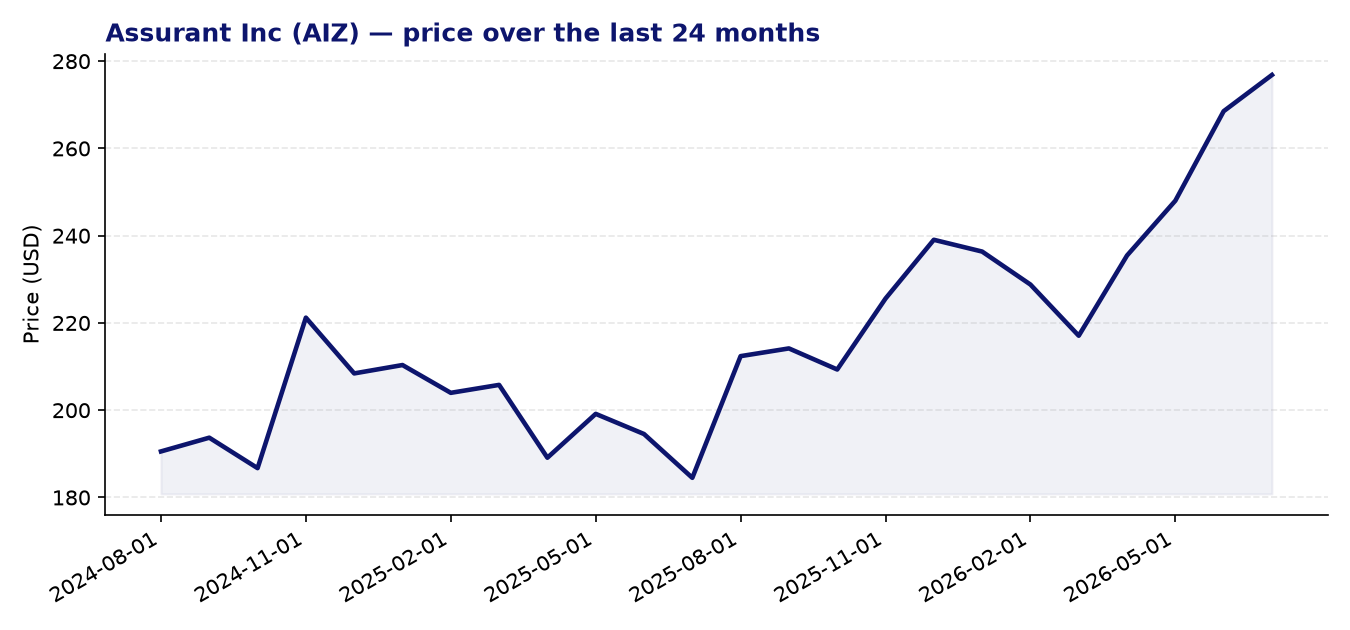
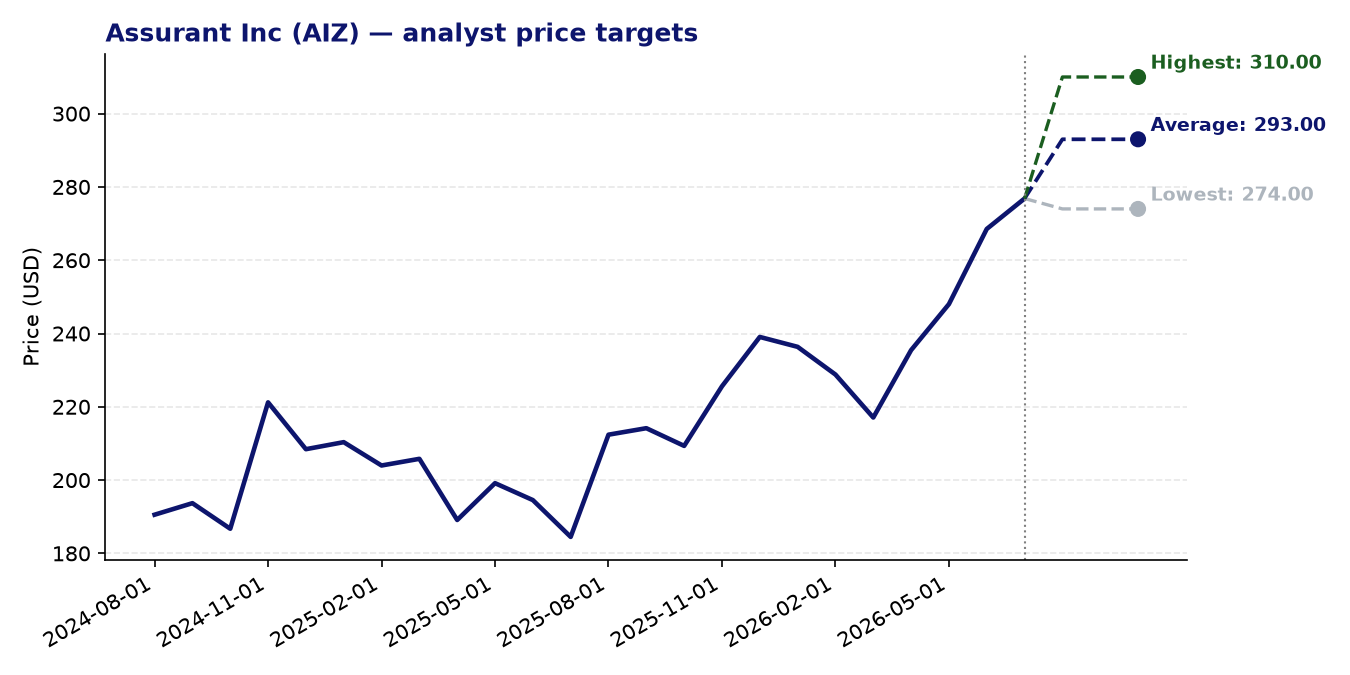
Assurant Inc (AIZ) — current price: 276.84 USD | average price target: 293.00 USD | potential: +5.8%
About Assurant Inc
- Assurant is a specialty insurance and protection services company founded in 1892 and headquartered in Atlanta, Georgia, serving customers across North America, Latin America, Europe, and Asia Pacific.
- Its Global Lifestyle segment covers mobile device protection, extended service contracts for consumer electronics and appliances, vehicle protection, and commercial equipment insurance.
- Its Global Housing segment focuses on lender-placed homeowners insurance, manufactured housing, flood insurance, and renters insurance products.
- With a market capitalisation of approximately $13 billion, Assurant occupies a distinctive niche within the broader property and casualty insurance landscape.
Recent news
- Truist Financial’s analyst Mark Hughes reaffirmed a Buy rating on Assurant in late June 2026, setting a price target of $310, suggesting meaningful upside from recent trading levels.
- The stock has been trading close to its 52-week high, prompting discussion among market observers about whether the recent price strength reflects durable fundamentals or near-term caution.
- Assurant attracted renewed valuation scrutiny from financial media following a solid share price run, with commentary focusing on whether current levels are supported by the company’s growth outlook.
- AIZ has been noted as outperforming the broader financial sector over recent months, drawing comparisons with peers in the property and casualty insurance space.
Strengths
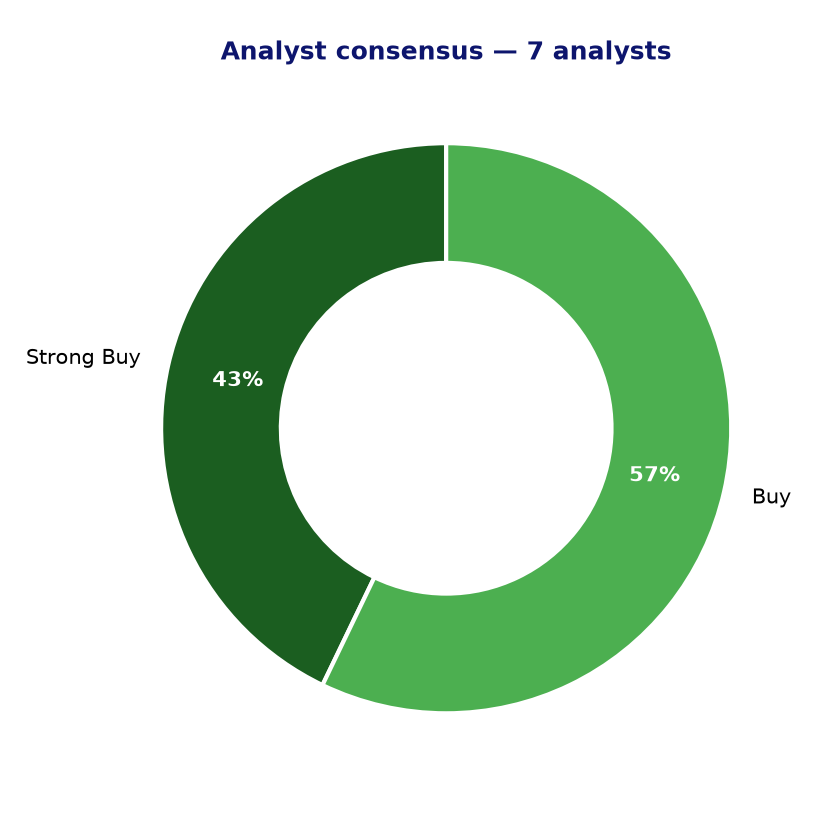
- Analyst sentiment is notably constructive: all seven covering analysts carry a Buy or Strong Buy rating, with zero Hold or Sell ratings, reflecting broad conviction in the investment case.
- The average price target of $293.00 implies approximately 5.8% upside from the current price of $276.84, with the most bullish target (Truist at $310) offering more than 12% potential appreciation.
- A 24-month Z-score momentum reading of 2.56 indicates that Assurant’s share price trend has been meaningfully positive relative to historical norms, a signal that sustained buying interest has underpinned recent gains.
- The forward P/E of 12.3x suggests the market is pricing in earnings growth at a moderate multiple, which may appeal to value-oriented investors within the financial services space.
- Assurant’s diversified business model — spanning connected devices, vehicles, and housing — provides some insulation from sector-specific downturns that might affect a more narrowly focused insurer.
Points of attention and risks
- The PEG ratio of 2.16 indicates that the stock is not obviously cheap relative to its earnings growth rate, and investors paying near the 52-week high should weigh this carefully.
- EPS growth of 0.87% is modest, and if earnings momentum does not accelerate materially, the current valuation may leave limited room for further re-rating.
- With the lowest analyst price target sitting at $274 — below the current share price of $276.84 — there is at least one cautious view on the Street that sees downside risk from current levels.
- Assurant’s lender-placed homeowners insurance business is sensitive to housing market conditions and regulatory scrutiny, both of which can be unpredictable and difficult to model.
- Operating in multiple international markets exposes the company to currency fluctuation and varying regulatory environments, which can add complexity to earnings forecasting.
Analyst consensus and price targets
Conclusion
Assurant presents a coherent investment case built on a diversified specialty insurance model, uniformly positive analyst ratings, and solid price momentum — though the stock’s proximity to its 52-week high and a PEG ratio above 2 warrant measured expectations. The modest near-term EPS growth and a floor analyst target below the current price serve as useful reminders that the easy gains may already be reflected in the price. Investors with a patient, multi-year time horizon may find the business model’s structural diversification appealing, while those considering entry at current levels should weigh the relatively limited consensus upside against the quality of the franchise.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 20-07-2026. Not investment advice.