
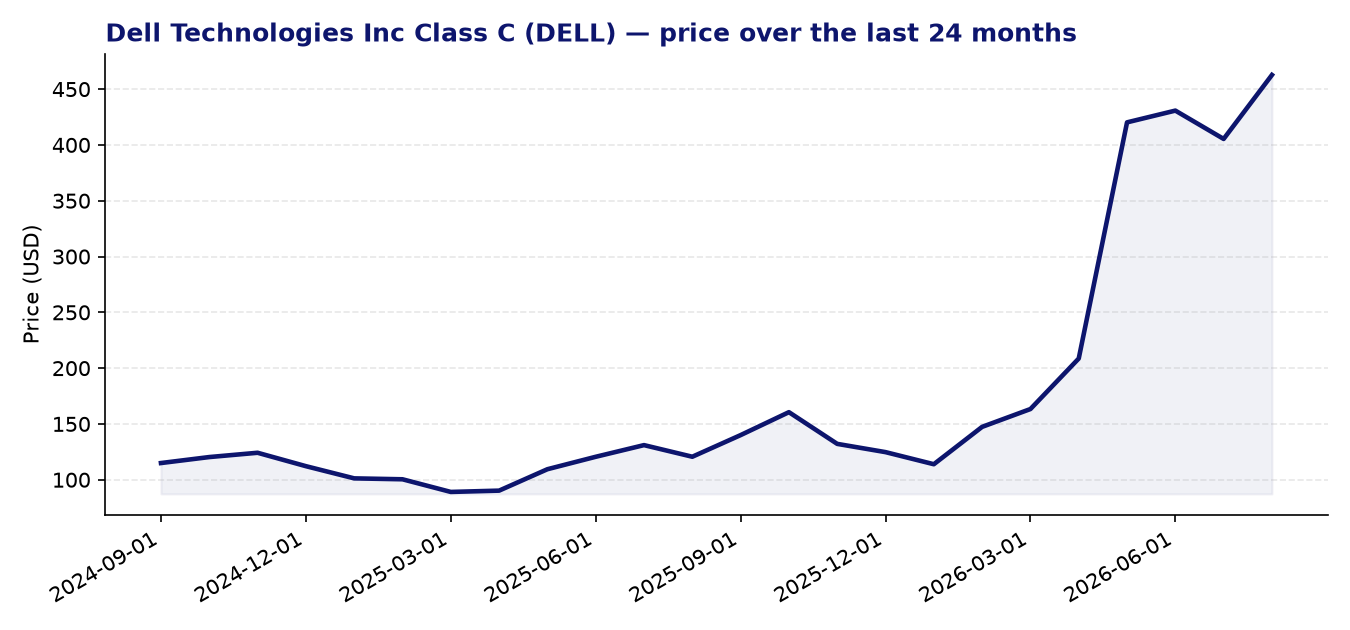
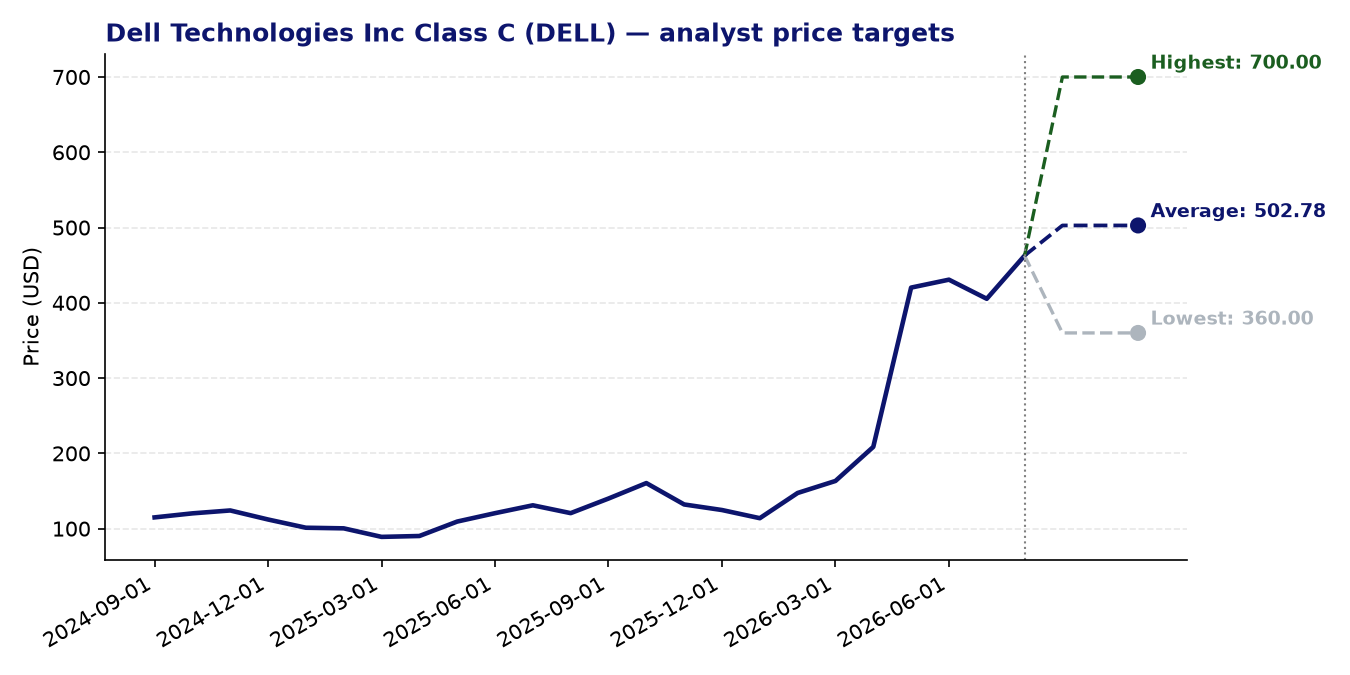
Dell Technologies Inc Class C (DELL) — current price: 462.70 USD | average price target: 502.78 USD | potential: +8.7%
About Dell Technologies Inc Class C
- Dell Technologies designs, manufactures, and sells a broad range of hardware, software, and services across two main segments: Infrastructure Solutions Group (ISG) and Client Solutions Group (CSG).
- The ISG segment covers servers (including AI-optimised), storage solutions, and networking products aimed at helping enterprises modernise their data centre infrastructure.
- The CSG segment supplies notebooks, desktops, workstations, and branded peripherals to consumers, businesses, and institutions worldwide.
- Dell also provides customer financing, leasing, and consumption-based payment solutions, and serves a wide customer base from large enterprises and governments to small businesses and individual consumers.
- The company has a strategic alliance with Rafay Systems focused on developing AI infrastructure solutions, reflecting its growing emphasis on the artificial intelligence market.
Recent news
- Dell reported a remarkable first quarter of fiscal year 2027 on 28 May 2026, with revenue reaching approximately $43.8 billion — an 88% year-over-year increase — and non-GAAP earnings per share of $4.86, well ahead of the $2.90 analyst consensus estimate.
- The company’s AI server business was a standout driver of the quarterly results, signalling that Dell has established a meaningful position in the fast-growing AI infrastructure market.
- Morgan Stanley upgraded Dell from Underweight to Equal-weight in early June 2026, sharply raising its price target to $448 from $170, citing better-than-expected execution and acknowledging that its earlier cautious thesis on memory supply had not played out as anticipated.
- Earlier in February 2026, Citi modestly trimmed its price target to $160 from $165 ahead of earnings while retaining a Buy rating, a revision that was quickly overtaken by the strength of the subsequent quarterly results.
Strengths
- The Q1 FY2027 earnings beat was substantial, with EPS coming in roughly 67% above consensus, demonstrating strong operational execution and demand well in excess of market expectations.
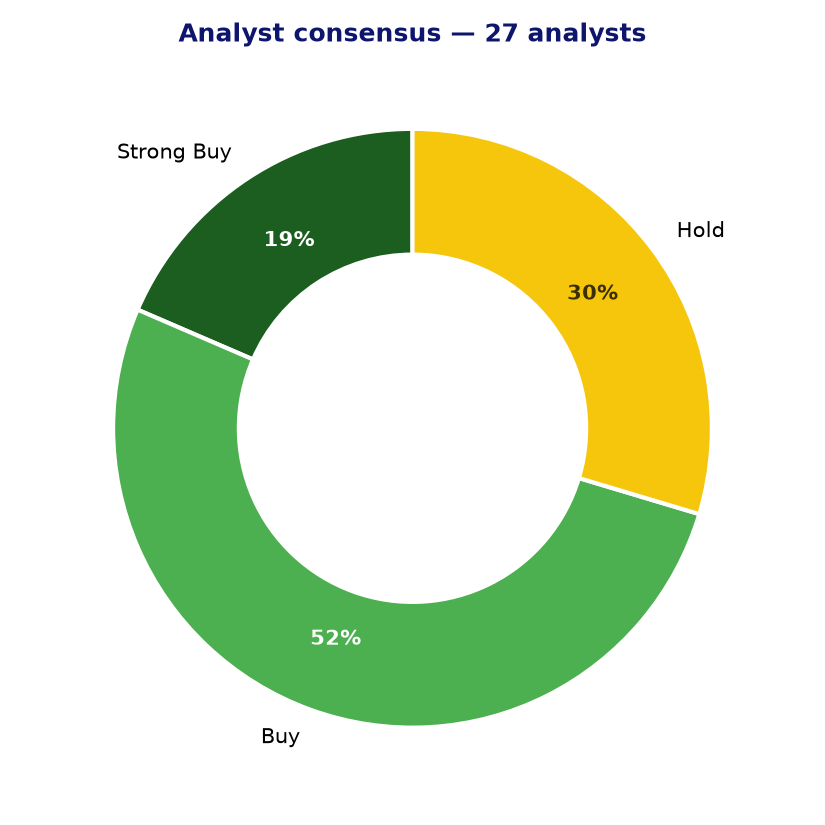
- Analyst sentiment is broadly constructive: of 27 analysts covering the stock, 19 rate it Buy or Strong Buy, with an average price target of $502.78, implying approximately 8.7% upside from the current price.
- The forward P/E of 21.2x is considerably more modest than the trailing P/E of 36.9x, suggesting earnings are expected to grow materially, a view supported by a PEG ratio of just 0.66 — generally considered indicative of reasonable valuation relative to growth.
- A 24-month Z-score momentum reading of 1.89 reflects meaningful positive price momentum, consistent with improving investor recognition of Dell’s AI infrastructure opportunity.
- Dell’s dual-segment structure gives it exposure to both the high-growth AI server and storage market through ISG and the large, cash-generative PC and peripherals market through CSG, providing some revenue diversification.
Points of attention and risks
- The trailing P/E of 36.9x is elevated relative to Dell’s historical valuation and to many hardware peers, meaning the stock already prices in a significant degree of continued earnings improvement.
- The wide gap between the lowest and highest analyst price targets ($360 to $700) reflects genuine uncertainty about how durable the AI server demand cycle will prove to be, and how much of the opportunity Dell can capture over time.
- Dell operates in a highly competitive hardware market with thin margins in its CSG segment; the recent revenue surge is heavily tied to AI server demand, which may be lumpy and subject to shifts in capital spending by large cloud and enterprise customers.
- The Morgan Stanley upgrade, while positive in tone, only moved the stock to Equal-weight, not an outright Buy, suggesting some larger institutional investors remain cautious about the risk/reward at current price levels.
- Dell carries a notable debt load from its leveraged buyout history and subsequent acquisitions; rising interest rates or any slowdown in cash generation could constrain financial flexibility.
Analyst consensus and price targets
Conclusion
Dell Technologies has delivered a striking earnings result that has reset market expectations about its role in the AI infrastructure buildout, and the analyst community has responded with broadly positive revisions. The valuation, while not cheap on a trailing basis, looks more reasonable on forward earnings, and momentum indicators support the recent re-rating. That said, the durability of AI server demand, competitive pricing pressure in hardware, and balance sheet leverage are genuine considerations that investors should weigh alongside the undeniably strong near-term trading momentum.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 06-08-2026. Not investment advice.