
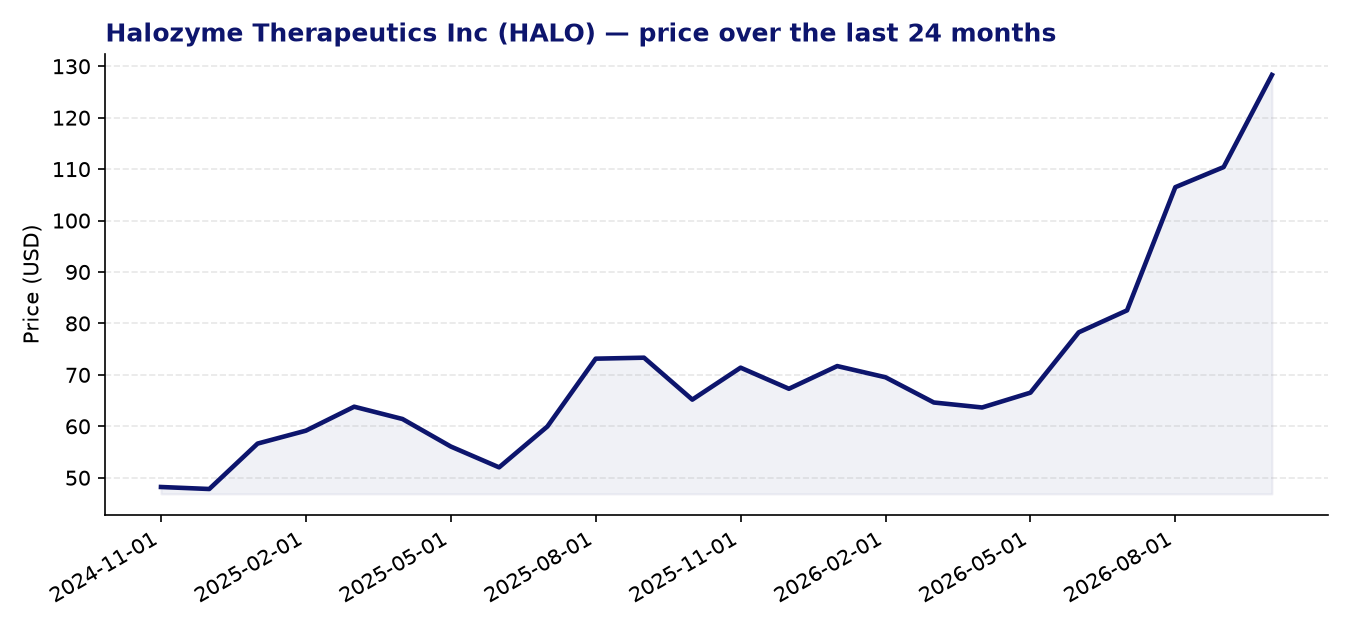
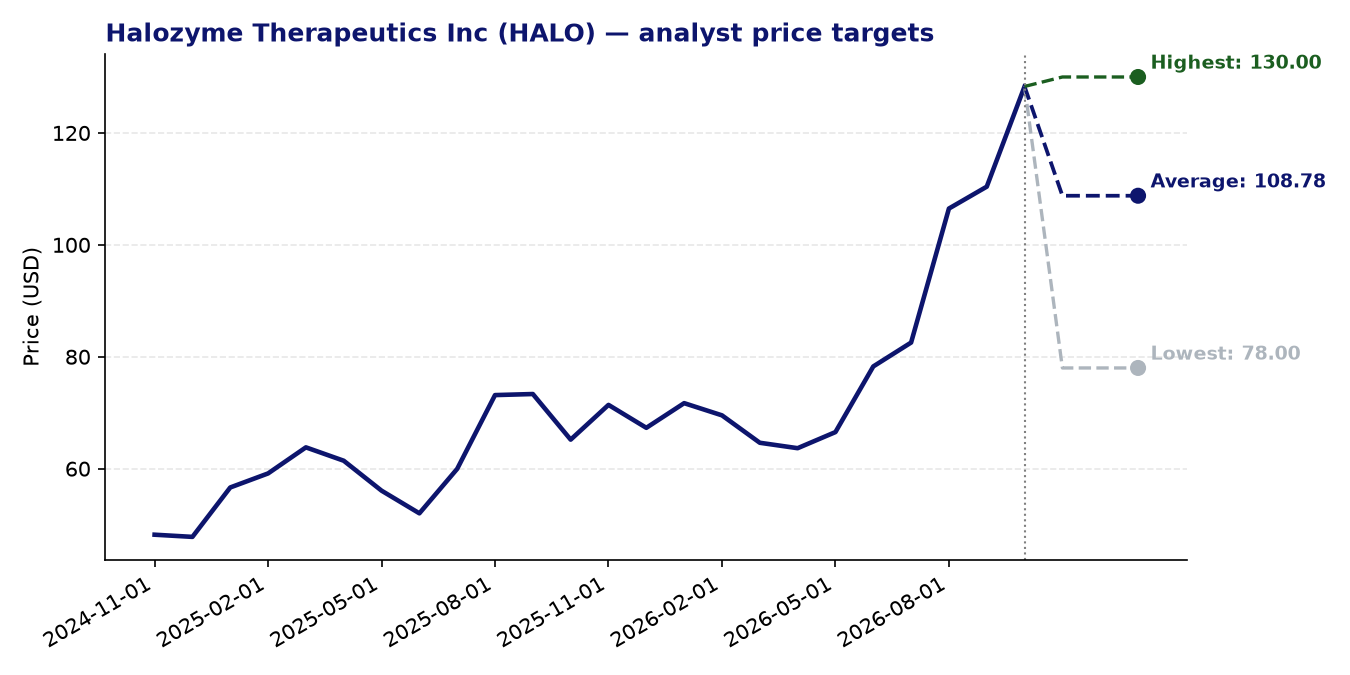
Halozyme Therapeutics Inc (HALO) — current price: 128.31 USD | average price target: 108.78 USD | potential: -15.2%
About Halozyme Therapeutics Inc
- Halozyme Therapeutics is a San Diego-based biopharmaceutical company founded in 1998, focused on its proprietary ENHANZE drug delivery technology, built around the recombinant human hyaluronidase enzyme (rHuPH20).
- ENHANZE enables traditionally intravenous biologics to be administered subcutaneously, offering faster and more convenient delivery for patients and healthcare providers.
- The company generates revenue primarily through royalties and licensing fees from a broad network of major pharmaceutical partners, including Roche, Janssen, AbbVie, Pfizer, Bristol Myers Squibb, and Eli Lilly, among others.
- Partner products using ENHANZE span several high-value therapeutic areas, including oncology (DARZALEX, Phesgo, Tecentriq SC), multiple sclerosis (Ocrevus SC), and severe autoimmune diseases (ARGX-113, ARGX-117).
- Halozyme also markets its own products, including Hylenex recombinant and XYOSTED, a subcutaneous testosterone replacement therapy.
Recent news
- Halozyme’s shares surged more than 18% following a strong second-quarter 2026 earnings report that exceeded market expectations, reflecting continued momentum in its royalty-driven business model.
- Second-quarter 2026 results showed revenue growing 48% year-over-year, driven by the expansion of ENHANZE-based royalties across multiple partner products beyond the flagship DARZALEX SC franchise.
- Analysts and commentators have highlighted that the market may be underestimating the breadth of Halozyme’s second wave of growth, as newer partner drugs begin contributing meaningfully to the royalty stream.
- Recent price action showed an additional 3.3% single-session gain in late September 2026, suggesting continued positive sentiment around the company’s growth profile.
Strengths
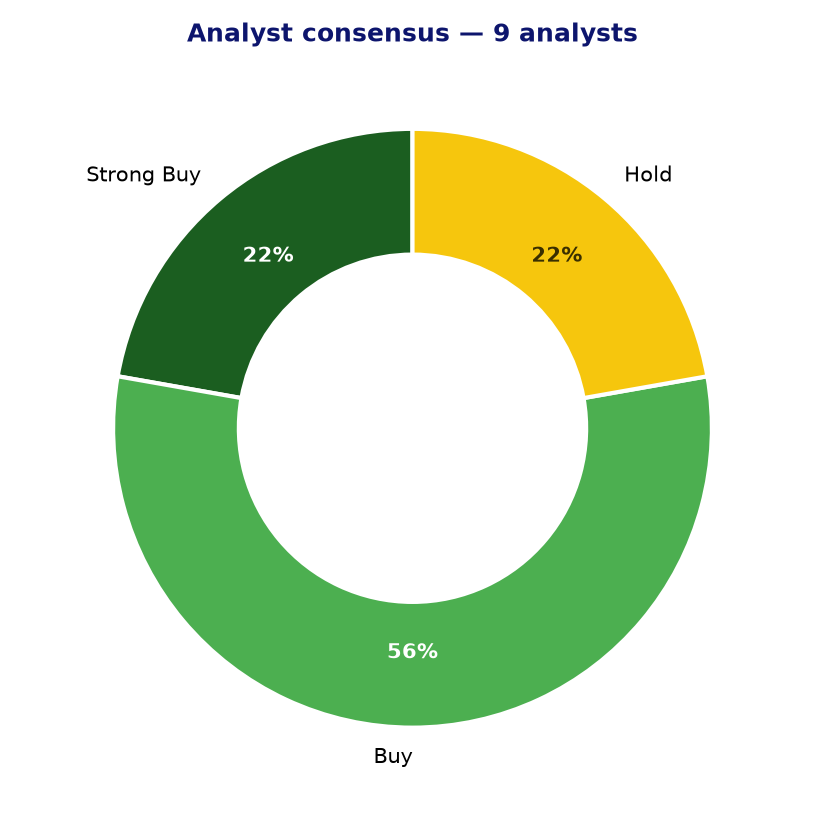
- Analyst sentiment is constructive, with 7 out of 9 covering analysts rating the stock a buy or strong buy, reflecting confidence in the durability of the royalty platform.
- The 24-month momentum Z-score of 3.00 indicates that HALO’s price performance has been significantly above its historical average, a sign of sustained market interest.
- The forward P/E of 12.02 is notably low relative to the trailing P/E of 37.52, suggesting that analysts expect earnings to grow substantially and that near-term profitability is improving rapidly.
- Revenue growth of 48% year-over-year in Q2 2026 demonstrates the scalability of the asset-light royalty model, which requires limited incremental capital as partner drugs generate more sales.
- The diversification of ENHANZE partnerships across many large pharmaceutical companies reduces dependence on any single product, with newer partner assets beginning to contribute meaningfully to the royalty stream.
Points of attention and risks
- At the current price of $128.31, HALO trades above the average analyst price target of $108.78, implying a consensus downside of approximately 15%, which warrants caution for new investors.
- The highest analyst price target stands at $130.00, leaving very limited room above the current price even under the most optimistic scenario covered by analysts.
- The absence of a PEG ratio makes it difficult to precisely assess whether the current valuation adequately accounts for future growth, adding some uncertainty to the earnings-growth story.
- As a royalty-dependent business, Halozyme is exposed to risks outside its direct control, including partner drug performance, generic or biosimilar competition against partner products, and potential changes to licensing agreements.
- While EPS growth of 39% is strong, the trailing P/E of 37.52 still reflects a meaningful valuation premium, and any disappointment in partner drug sales or royalty rates could weigh on the share price.
Analyst consensus and price targets
Conclusion
Halozyme presents a compelling and increasingly diversified royalty platform with strong recent revenue growth and a forward earnings multiple that appears undemanding relative to the trailing figure. However, with the current share price already exceeding the analyst consensus target and sitting near the top of the target range, much of the near-term positive news may already be reflected in the valuation. Investors considering a position may wish to weigh the attractive business model and earnings trajectory against the limited implied upside at current levels, as well as the inherent dependency on the commercial success of partner drugs.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 27-10-2026. Not investment advice.