
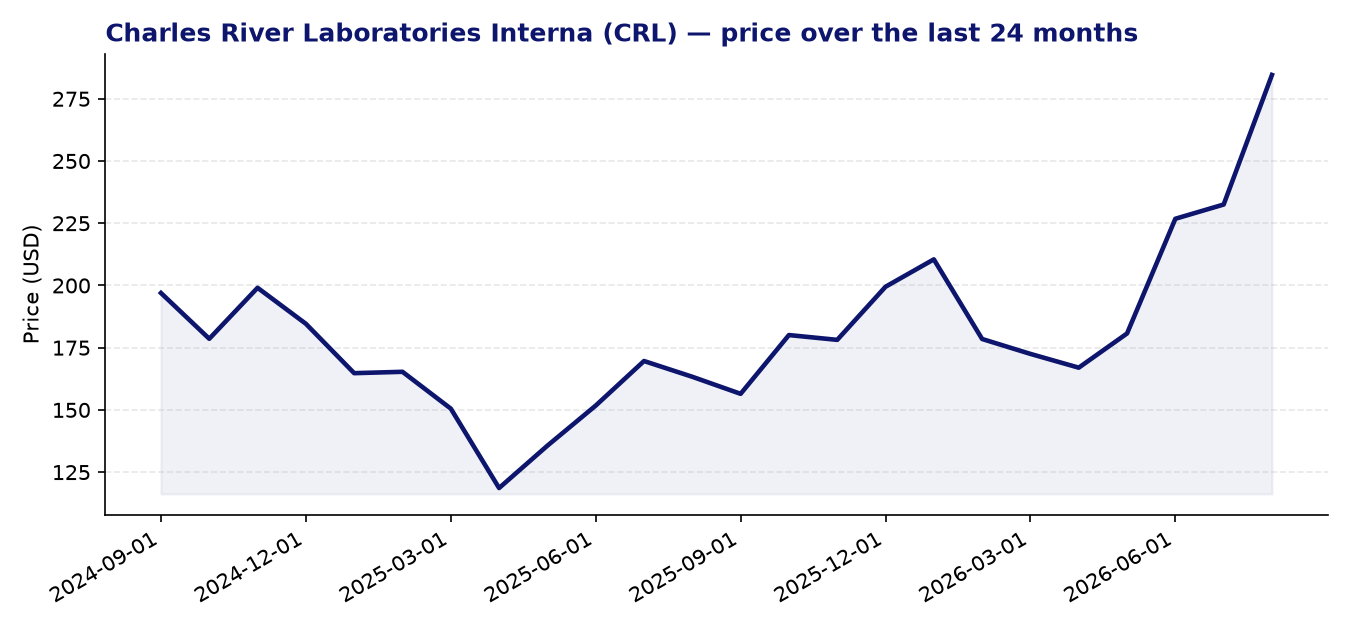
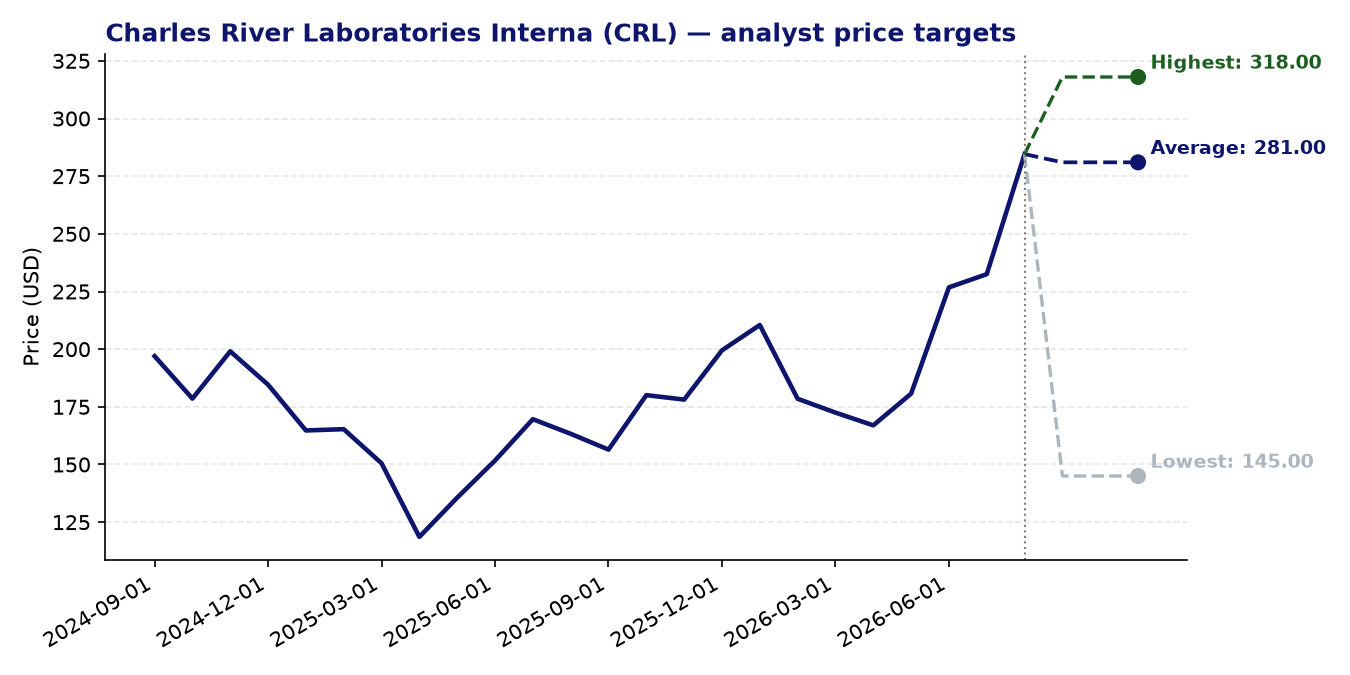
Charles River Laboratories Interna (CRL) — current price: 285.11 USD | average price target: 281.00 USD | potential: -1.4%
About Charles River Laboratories Interna
- Charles River Laboratories, founded in 1947 and headquartered in Wilmington, Massachusetts, is a leading contract research organisation serving pharmaceutical, biotechnology, government, and academic clients worldwide.
- Its Research Models and Services segment breeds and supplies purpose-bred rodents and offers a broad range of services supporting pre-clinical research, including genetically engineered models and cell therapy development.
- The Discovery and Safety Assessment segment delivers in vitro and in vivo drug discovery services alongside comprehensive safety testing — covering toxicology, pharmacology, bioanalysis, and pharmacokinetics.
- The Manufacturing Solutions segment provides quality-control testing for sterile and non-sterile pharmaceuticals, specialised biologics testing, and contract development and manufacturing services.
- The company holds strategic collaborations with the Parker Institute for Cancer Immunotherapy, Children’s Hospital Los Angeles, and the Francis Crick Institute, the latter focused on Antibody-Drug Conjugate discovery and development.
Recent news
- Morgan Stanley upgraded Charles River Laboratories in mid-June, reflecting growing institutional confidence in the company’s outlook; the stock was also highlighted as a top holding by Ariel Investments.
- Ahead of its upcoming earnings release, the company carries a market capitalisation of approximately $10.8 billion, with investor attention focused on trends in pharmaceutical outsourcing demand and margin trajectory.
- A bullish thesis circulating in investment commentary points to CRL’s structural positioning as a preferred outsourcing partner for drug developers, though specific catalysts cited vary across sources.
- No major product launches or material corporate transactions were reported in the period under review beyond the analyst upgrade and pre-earnings commentary.
Strengths
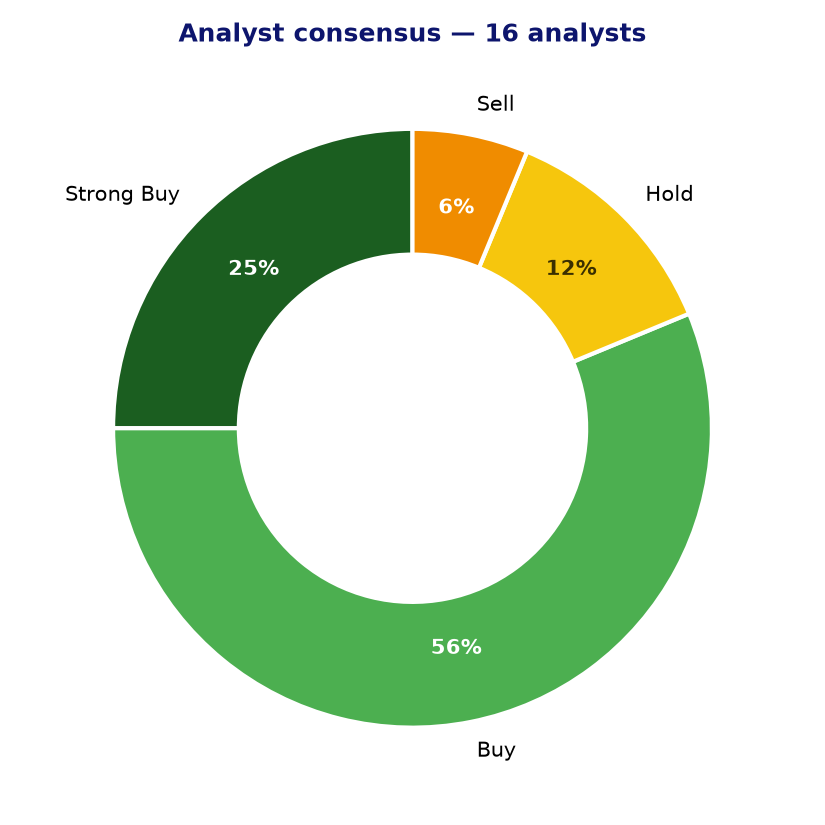
- Analyst sentiment is broadly constructive: 13 of 16 covering analysts rate the stock either buy or strong buy, with no strong sell ratings on record.
- The 24-month Z-score momentum reading of 2.33 indicates that the shares have displayed meaningful positive price momentum relative to historical norms, suggesting sustained market interest.
- The forward P/E of 22.47 appears reasonable for a diversified contract research organisation with recurring client relationships, while the notably low PEG ratio of 0.12 suggests the market may not yet be fully pricing in expected earnings growth.
- Charles River’s diversified, three-segment business model — spanning research models, safety assessment, and manufacturing solutions — provides a degree of revenue stability across different phases of the drug development cycle.
- Strategic alliances with the Francis Crick Institute on ADC drug discovery and with leading oncology institutions position the company in structurally growing areas of biopharmaceutical development.
Points of attention and risks
- The consensus average price target of $281.00 sits approximately 1.4% below the current share price of $285.11, implying that, in aggregate, analysts see little near-term upside from current levels.
- The wide dispersion between the lowest ($145.00) and highest ($318.00) price targets reflects material uncertainty about the company’s earnings trajectory and sector conditions, which warrants attention.
- No trailing P/E or current EPS figure is available, making it harder to assess profitability on a reported basis; investors should monitor whether forward earnings estimates prove achievable.
- The contract research sector faces cyclical pressure when pharmaceutical and biotech clients reduce R&D budgets or consolidate outsourcing relationships, a risk that has been evident across the industry in recent periods.
- Dependence on a relatively small number of large pharmaceutical clients for a significant share of revenues introduces concentration risk, and any slowdown in drug development pipelines could weigh on revenue visibility.
Analyst consensus and price targets
Conclusion
Charles River Laboratories occupies a well-established position in the pharmaceutical outsourcing ecosystem, with a broadly supportive analyst community, positive price momentum, and a valuation that on a forward and PEG basis does not look stretched. That said, the consensus price target implies the current share price already reflects much of the near-term optimism, and the business remains sensitive to fluctuations in pharmaceutical R&D spending and client budget cycles. Investors considering CRL may find the long-term structural case for outsourced drug development services compelling, but should weigh that against the limited consensus upside and the earnings uncertainty reflected in the absence of a trailing P/E figure.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 13-08-2026. Not investment advice.