
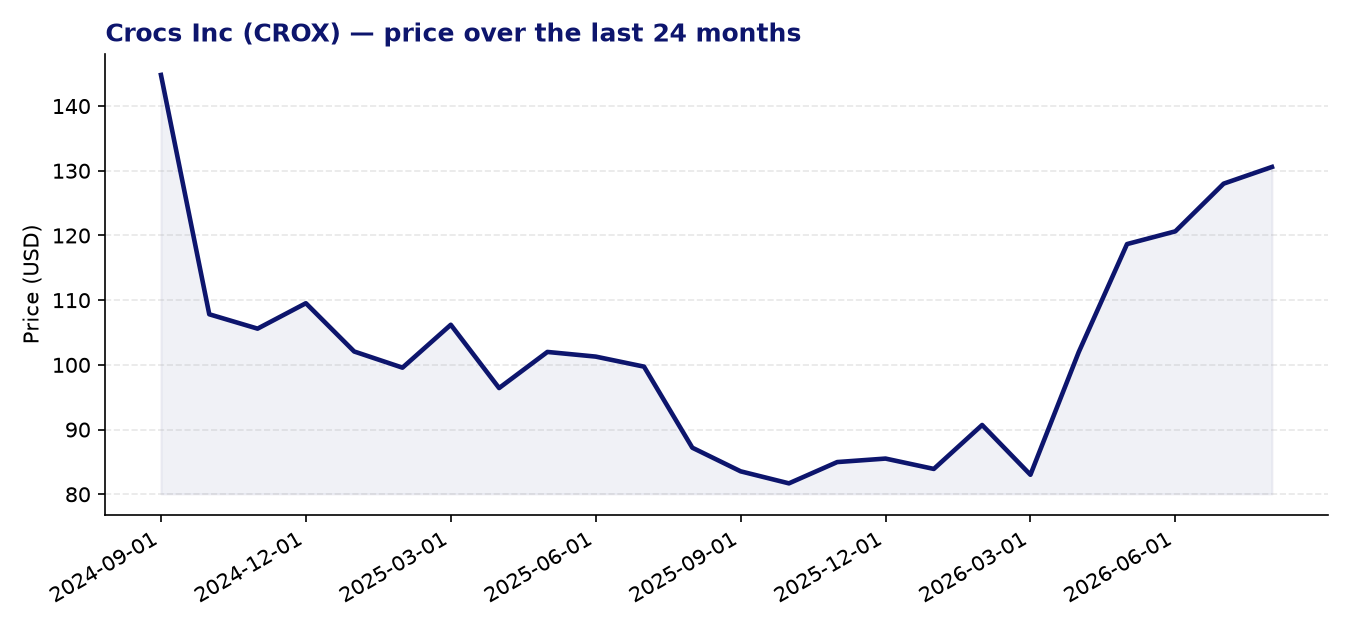
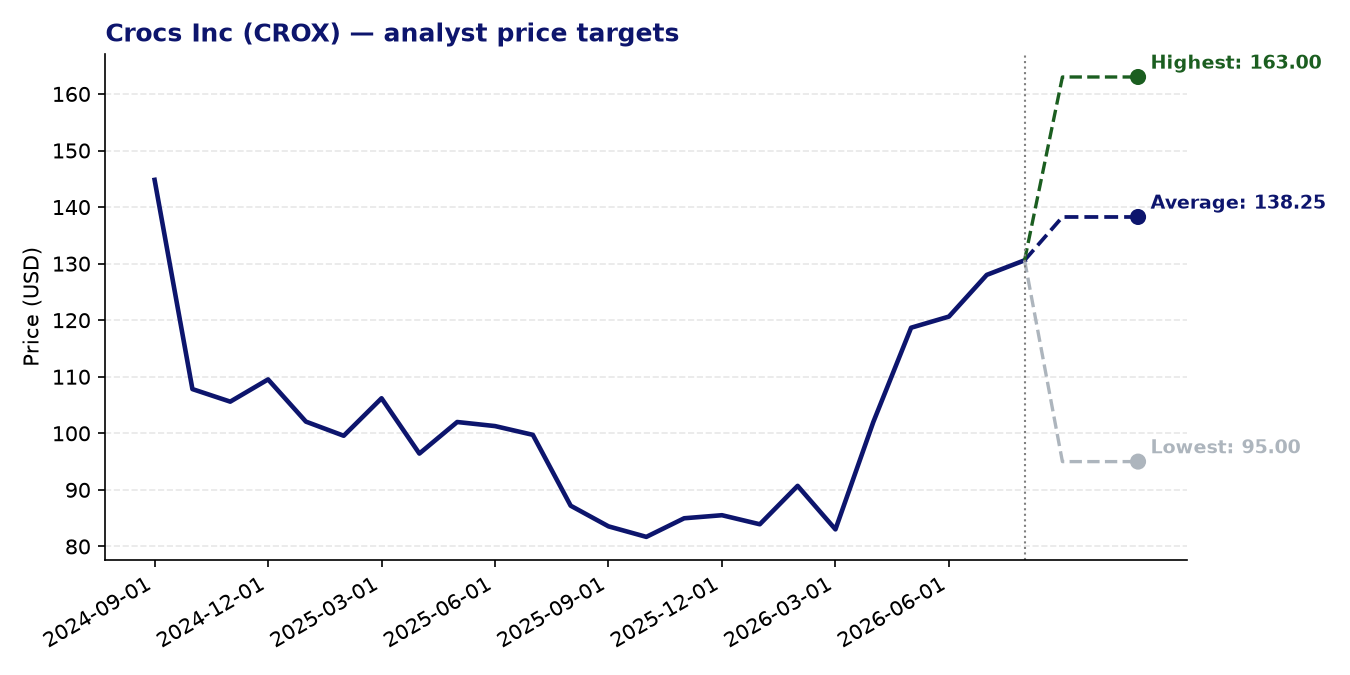
Crocs Inc (CROX) — current price: 130.59 USD | average price target: 138.25 USD | potential: +5.9%
About Crocs Inc
- Crocs, Inc. designs, markets, and sells casual lifestyle footwear and accessories for men, women, and children under its two core brands: Crocs and HEYDUDE.
- The product range spans clogs, sandals, boots, sneakers, slippers, and flip-flops, alongside accessories such as totes, backpacks, socks, and bag charms.
- Distribution is diversified across wholesale partners, owned retail stores, outlet locations, e-commerce platforms, and third-party marketplaces, both in the US and internationally.
- Founded in 1999 and headquartered in Broomfield, Colorado, Crocs has grown from a single clog concept into a multi-brand footwear group with over $1 billion in quarterly brand-level revenue.
Recent news
- Crocs reported Q2 2026 adjusted earnings per share of $4.55, ahead of the consensus estimate of $4.32 and up from $4.23 in the same period a year earlier.
- Total revenues for the quarter reached $1.179 billion, a 2.6% increase year-on-year, with the Crocs brand alone surpassing $1 billion in quarterly sales for the first time.
- Despite the earnings beat, the stock sold off after management issued Q3 profit guidance that fell materially short of analyst expectations, signalling near-term margin or demand pressure.
- Net income for Q2 came in at $204.9 million, or $4.13 per share on a reported (GAAP) basis, while an earnings call was held on 30 July to discuss results in detail.
Strengths
- The Crocs brand achieving more than $1 billion in a single quarter is a meaningful commercial milestone, underscoring the brand’s sustained consumer appeal.
- Adjusted EPS of $4.55 beat consensus estimates by roughly 5%, and represents year-on-year growth, demonstrating ongoing earnings delivery.
- The forward P/E of 8.74 looks undemanding for a branded consumer company, suggesting the market may already be pricing in a degree of slowdown.
- A 24-month Z-score momentum reading of 2.19 indicates the stock has exhibited above-average price momentum relative to its own history, which can attract trend-following interest.
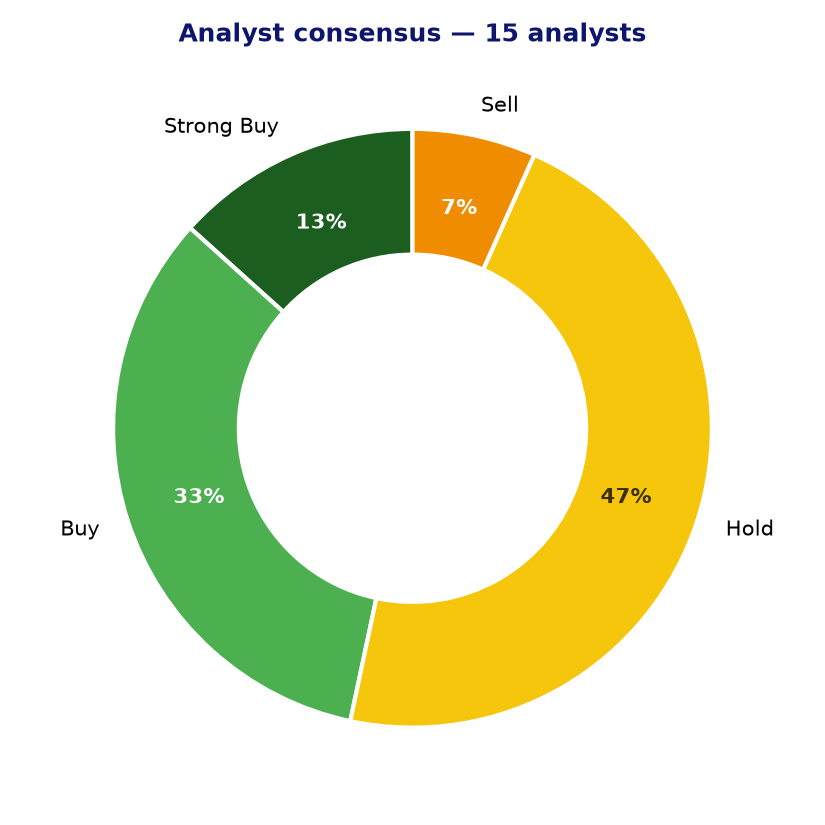
- The analyst consensus leans constructive, with seven of fifteen analysts holding a buy or strong buy rating and an average price target implying roughly 5.9% upside from current levels.
Points of attention and risks
- Q3 profit guidance came in well below market expectations, which was the primary driver of the post-results share price decline and raises questions about near-term earnings visibility.
- Revenue growth of 2.6% in Q2 is modest for a consumer brand, and with no EPS growth figure available, the sustainability of earnings expansion is not straightforward to assess.
- The wide range between the lowest ($95) and highest ($163) analyst price targets reflects significant disagreement about the company’s prospects, a sign of meaningful uncertainty.
- The HEYDUDE brand has faced integration challenges and softer demand since its acquisition, and there is no clear evidence from recent results that this has been fully resolved.
- As a consumer cyclical, Crocs remains exposed to shifts in discretionary spending, changes in fashion trends, and the risk that the brand’s core clog product reaches market saturation.
Analyst consensus and price targets
Conclusion
Crocs enters the second half of 2026 with a record-breaking Crocs brand quarter behind it and a valuation that, on a forward earnings basis, appears modest relative to many branded consumer peers. However, the guidance disappointment for Q3 is a tangible near-term concern, and the combination of low single-digit revenue growth and uncertainty around HEYDUDE means the investment case requires patience rather than momentum. Investors may find the risk-reward reasonable at current levels, but the guidance miss warrants careful monitoring of how execution develops over the coming quarters.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 18-08-2026. Not investment advice.