
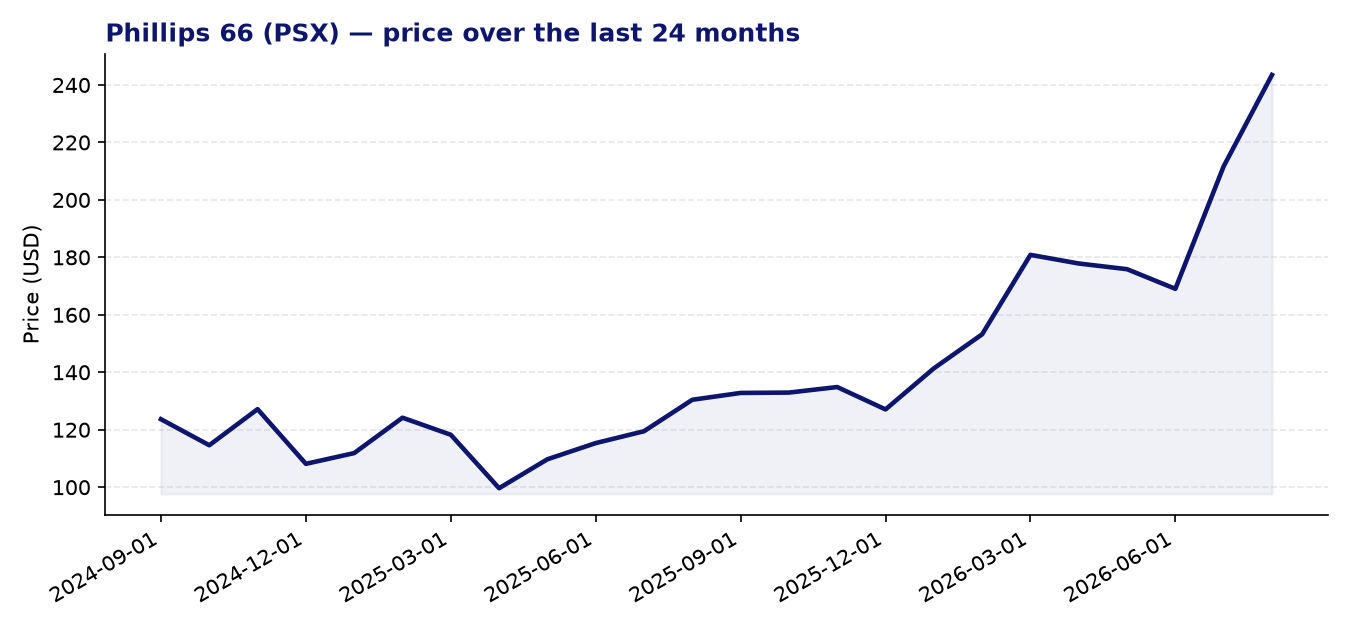
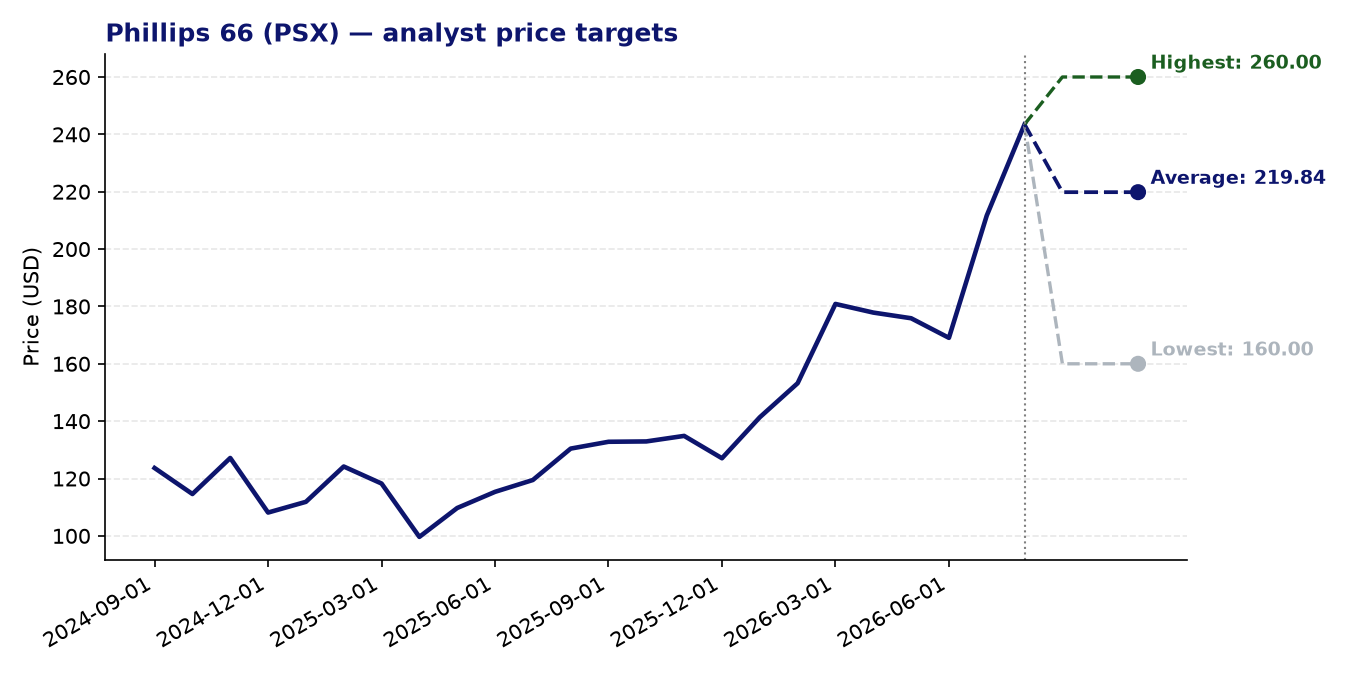
Phillips 66 (PSX) — current price: 243.49 USD | average price target: 219.84 USD | potential: -9.7%
About Phillips 66
- Phillips 66 is a large integrated downstream energy company headquartered in Houston, Texas, with operations spanning the United States, United Kingdom, Germany, and other international markets.
- The company operates across five segments: Midstream, Chemicals, Refining, Marketing & Specialties, and Renewable Fuels, giving it broad exposure across the energy value chain.
- Its refining operations convert crude oil and other feedstocks into gasoline, distillates, and aviation fuels, while its chemicals business produces ethylene, aromatics, and specialty chemicals.
- Phillips 66 is also building a presence in renewable energy through its Renewable Fuels segment, which processes renewable feedstocks into renewable diesel, renewable jet fuel, and sustainable aviation fuel.
- The company markets products under well-known brands including Phillips 66, Conoco, 76, JET, and Kendall, and traces its origins back to 1875.
Recent news
- Zacks Investment Research upgraded Phillips 66 to a Buy rating in late July 2026, citing an upward trend in earnings estimates as the key driver of the improved outlook.
- Ahead of its second-quarter 2026 earnings release, analyst consensus pointed to year-over-year growth in both earnings and revenues, suggesting a degree of confidence in near-term operational momentum.
- Zacks also highlighted Phillips 66 as a long-term growth stock candidate, reflecting positive sentiment around the company’s diversified downstream model.
- Some commentary noted potential headwinds from rising crude oil market tensions, flagging that these could weigh on the stock’s near-term valuation despite its strong five-year performance.
Strengths
- The Zacks upgrade to Buy, grounded in rising earnings estimate revisions, adds credibility to the near-term earnings growth narrative ahead of the Q2 2026 results.
- A forward P/E of 11.58 represents a meaningful discount to the trailing P/E of 13.91, suggesting the market is pricing in earnings improvement over the next twelve months.
- The 24-month Z-score momentum reading of 1.98 indicates that the stock has shown meaningful positive price momentum relative to its historical range, a constructive technical signal.
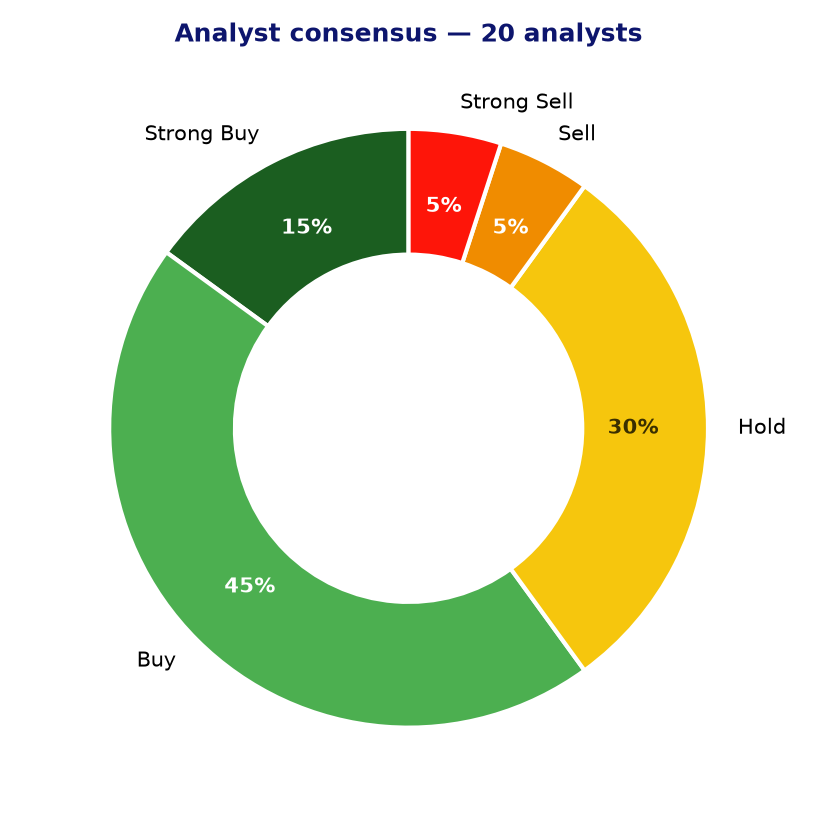
- Analyst sentiment remains broadly constructive, with 12 out of 20 covering analysts at buy or strong buy, reflecting confidence in the company’s diversified downstream model.
- The company’s five-segment structure provides meaningful diversification, with chemicals, midstream, and renewable fuels offering some buffer against pure refining margin volatility.
Points of attention and risks
- At the current price of $243.49, the stock is trading well above the average analyst price target of $219.84, implying a negative consensus upside of approximately 9.7% from current levels.
- With six hold ratings and two sell or strong sell ratings among the 20 covering analysts, a meaningful portion of the analyst community is cautious at current price levels.
- Refining margins are inherently cyclical and sensitive to crude oil price movements; rising geopolitical crude tensions, as noted in recent commentary, could compress margins in the near term.
- A PEG ratio of 1.35 and EPS growth of 3.39% suggest the stock is not obviously cheap relative to its growth profile, limiting the margin of safety for growth-oriented investors.
- The renewable fuels segment, while strategically important, operates in a competitive and policy-dependent environment where regulatory credit values and feedstock costs can shift significantly.
Analyst consensus and price targets
Conclusion
Phillips 66 offers a well-diversified downstream energy business with credible near-term earnings momentum, a reasonable forward valuation, and positive price momentum — qualities that explain the broadly constructive analyst stance. However, with the share price currently sitting roughly 10% above the average analyst price target, investors are being asked to look past near-term consensus fair value, at a time when refining margins face potential pressure from crude market uncertainty. The company’s long-term strategic positioning across midstream, chemicals, and renewables adds resilience, but prospective investors may wish to weigh entry timing carefully given the current premium to consensus targets.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 18-08-2026. Not investment advice.