
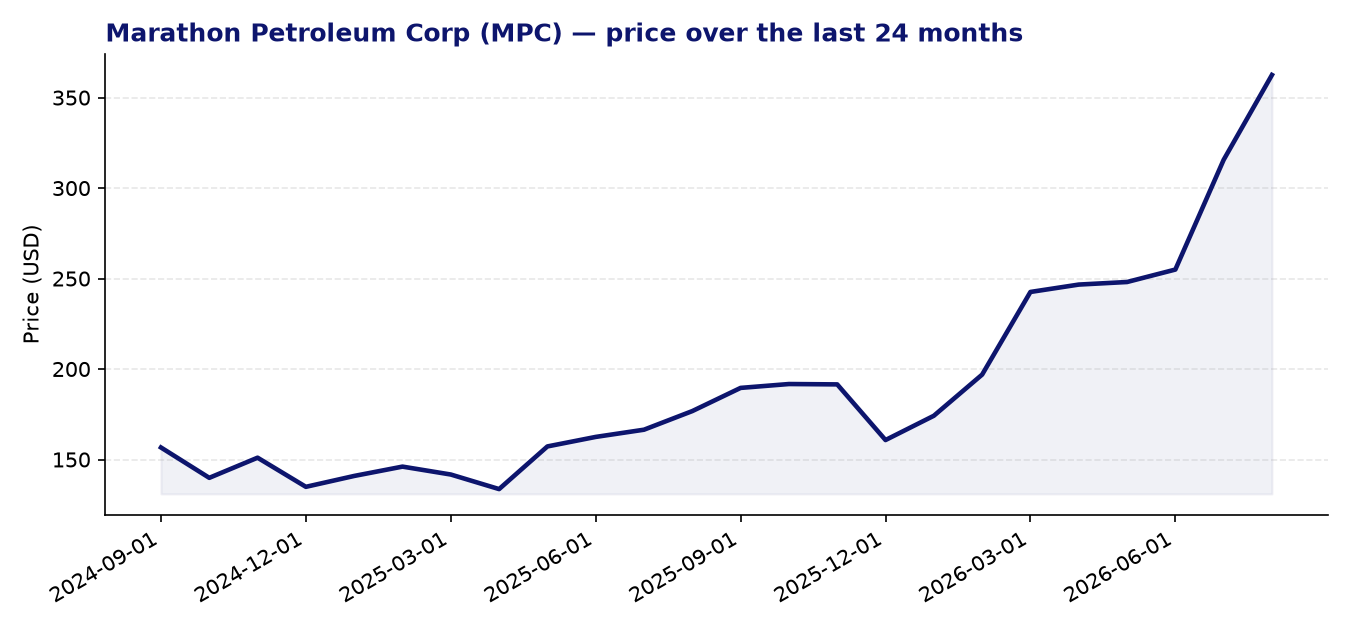
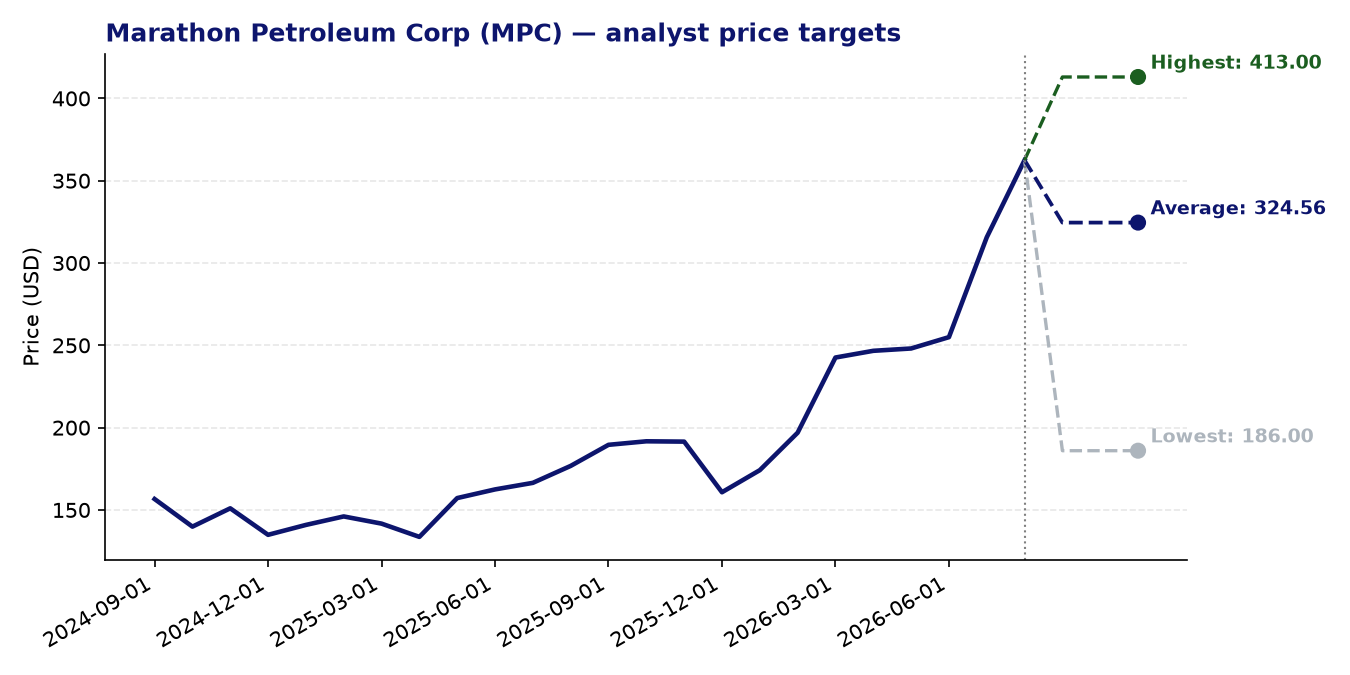
Marathon Petroleum Corp (MPC) — current price: 362.52 USD | average price target: 324.56 USD | potential: -10.5%
About Marathon Petroleum Corp
- Marathon Petroleum Corporation is one of the largest integrated downstream energy companies in the United States, operating the nation’s largest refining system across the Gulf Coast, Mid-Continent, and West Coast regions.
- Its Refining & Marketing segment processes crude oil and other feedstocks into transportation fuels, heavy fuel oil, asphalt, propane, and petrochemicals, distributing them under the Marathon and ARCO brands.
- The Midstream segment manages an extensive network of pipelines, terminals, barges, and processing facilities for crude oil, refined products, natural gas, and natural gas liquids.
- A Renewable Diesel segment processes renewable feedstocks into low-carbon fuel, distributed through the company’s own midstream infrastructure and third-party channels.
- Founded in 1887 and headquartered in Findlay, Ohio, MPC operates at significant scale, with a market capitalisation of approximately $86.7 billion.
Recent news
- Marathon Petroleum reported a strong second-quarter 2026 earnings beat, with adjusted EPS of $17.73 substantially exceeding the analyst consensus estimate of around $13–$14.52, reflecting a sharp year-over-year improvement in profitability.
- Ahead of the Q2 release, Wall Street had anticipated earnings growth of roughly 267% year-on-year, signalling broad analyst expectations of a significant refining margin recovery.
- MPC shares gained ground in late July, outperforming the broader S&P 500 on several sessions, suggesting improving near-term market sentiment toward the stock.
- The stock appeared on Zacks’ most-searched list in July 2026, indicating heightened retail and institutional investor interest heading into the earnings period.
Strengths
- The Q2 2026 earnings beat was substantial, with adjusted EPS of $17.73 well ahead of consensus, pointing to strong refining margins and effective cost management during the period.
- At a trailing P/E of 12.56 and a forward P/E of 11.26, the stock trades at a relatively modest earnings multiple for a company of its scale and operational complexity.
- A Z-score momentum reading of 2.16 over the past 24 months indicates that MPC has shown meaningful positive price momentum relative to its historical norm.
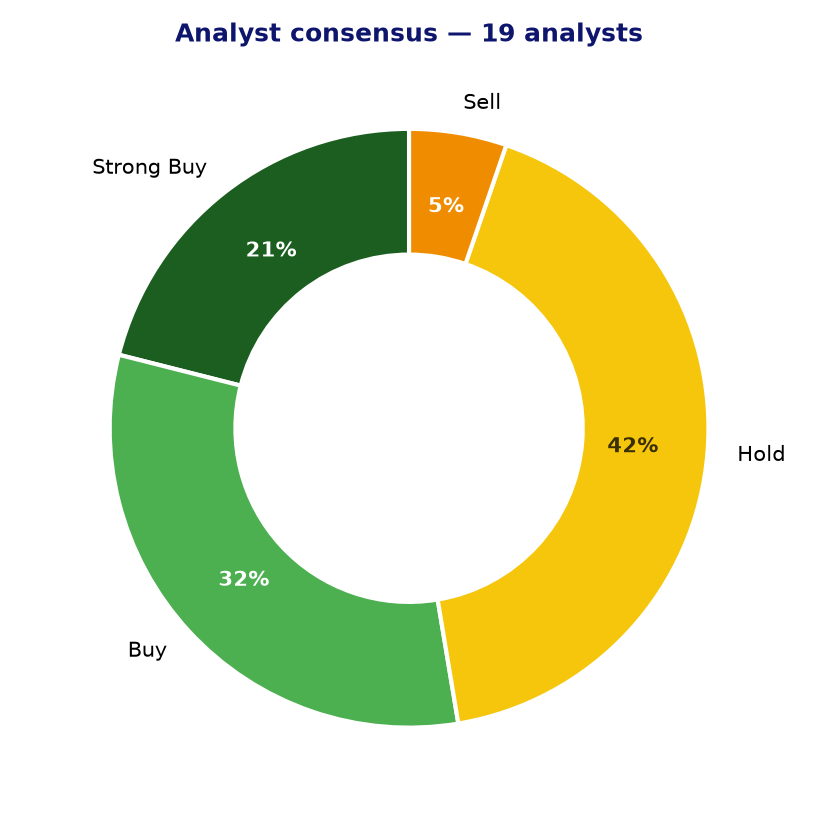
- Ten of nineteen covering analysts rate the stock a Buy or Strong Buy, reflecting a broadly constructive view of the company’s competitive position and earnings capacity.
- MPC’s integrated business model — spanning refining, midstream logistics, and renewable diesel — provides some diversification of revenue streams within the downstream energy value chain.
Points of attention and risks
- The current share price of $362.52 sits roughly 10.5% above the average analyst price target of $324.56, suggesting the market may have already priced in a significant portion of near-term upside.
- The wide dispersion between the lowest ($186.00) and highest ($413.00) analyst price targets reflects genuine uncertainty about earnings sustainability, particularly given the cyclical nature of refining margins.
- A PEG ratio of 1.79, combined with modest underlying EPS growth of 3.23%, raises a question about whether the current valuation is fully supported by the longer-term earnings growth trajectory.
- Eight of nineteen analysts have a Hold rating, indicating a meaningful portion of the coverage universe views the risk-reward as broadly balanced at current price levels.
- As a refiner, MPC’s profitability is highly sensitive to crack spreads, crude oil differentials, and fuel demand — all of which can shift materially and rapidly with macroeconomic or geopolitical developments.
Analyst consensus and price targets
Conclusion
Marathon Petroleum enters the second half of 2026 with strong operational momentum, as evidenced by a notable Q2 earnings beat and a solid refining environment. However, the stock’s current price already exceeds the average analyst consensus target, and the cyclical nature of refining margins means that the conditions underpinning recent outperformance are not guaranteed to persist. Investors may wish to weigh the relatively undemanding forward earnings multiple and positive price momentum against the limited implied upside from current levels and the sector’s inherent earnings volatility.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 24-08-2026. Not investment advice.