
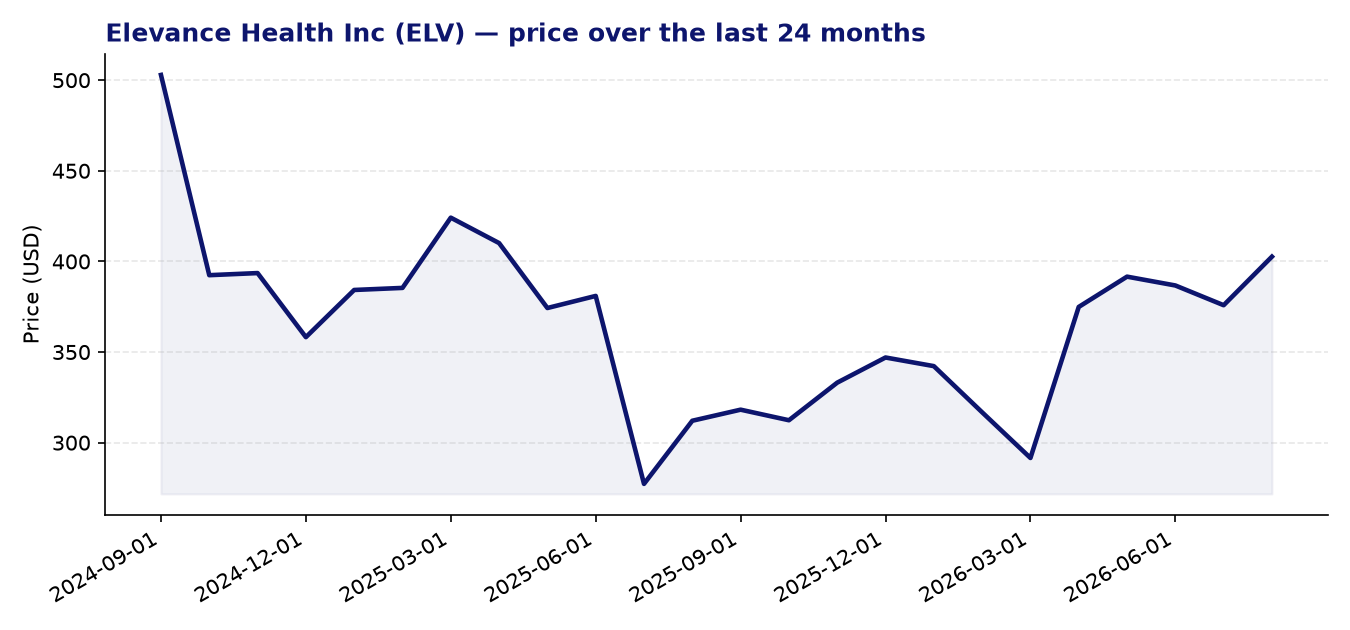
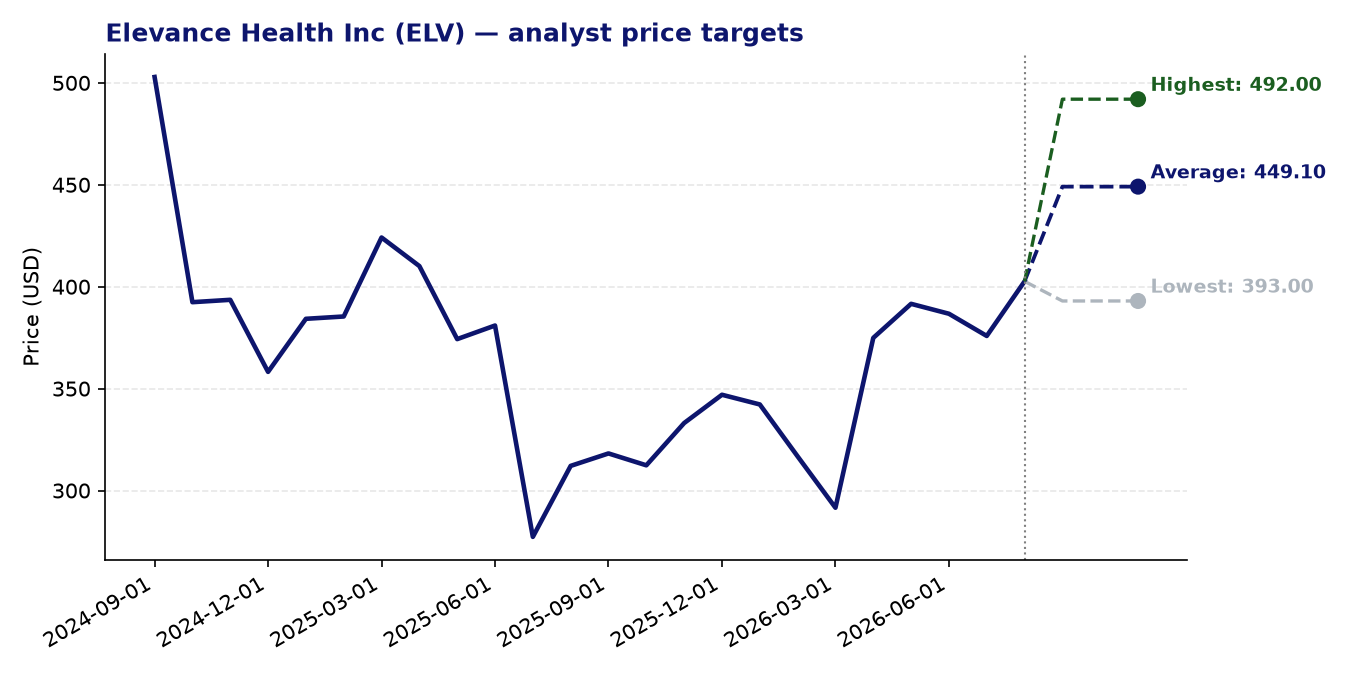
Elevance Health Inc (ELV) — current price: 402.63 USD | average price target: 449.10 USD | potential: +11.5%
About Elevance Health Inc
- Elevance Health is one of the largest US health benefits companies, serving individual, employer group, Medicare, Medicaid, and Federal Employee Program members under the Anthem Blue Cross and Blue Shield, Wellpoint, and Carelon brands.
- The company operates four segments: Health Benefits (its core insurance business), CarelonRx (pharmacy services), Carelon Services (care management and specialty services), and Corporate & Other.
- Through CarelonRx, Elevance provides a broad suite of pharmacy services including home delivery, specialty pharmacy, formulary management, and infusion therapies through ambulatory infusion centers.
- Its Carelon Services arm delivers behavioral health, palliative care, virtual care, and care management solutions, alongside data analytics and payment integrity capabilities via the HealthOS platform.
- Formerly known as Anthem, Inc., the company rebranded as Elevance Health in June 2022, reflecting its strategic expansion beyond traditional insurance into broader health services.
Recent news
- Elevance reported Q2 2026 revenue of approximately $49.8 billion, a modest 0.8% year-on-year increase, though earnings per share declined to $7.45 from $8.84 in the same quarter a year earlier, falling short of prior-year comparisons.
- The quarterly results triggered a notable sell-off in health insurance stocks broadly, as management flagged continued margin pressure within the core Health Benefits segment, raising concerns across the managed care sector.
- Bernstein analyst Lance Wilkes maintained a Buy rating on the stock following the results, setting a price target of $488, suggesting meaningful upside from current levels despite the near-term headwinds.
- Baron Capital’s Health Care Fund highlighted Elevance in its Q2 2026 investor letter, raising the question of whether the company is positioned for a margin recovery — a theme that appears central to the investment debate around the stock.
Strengths
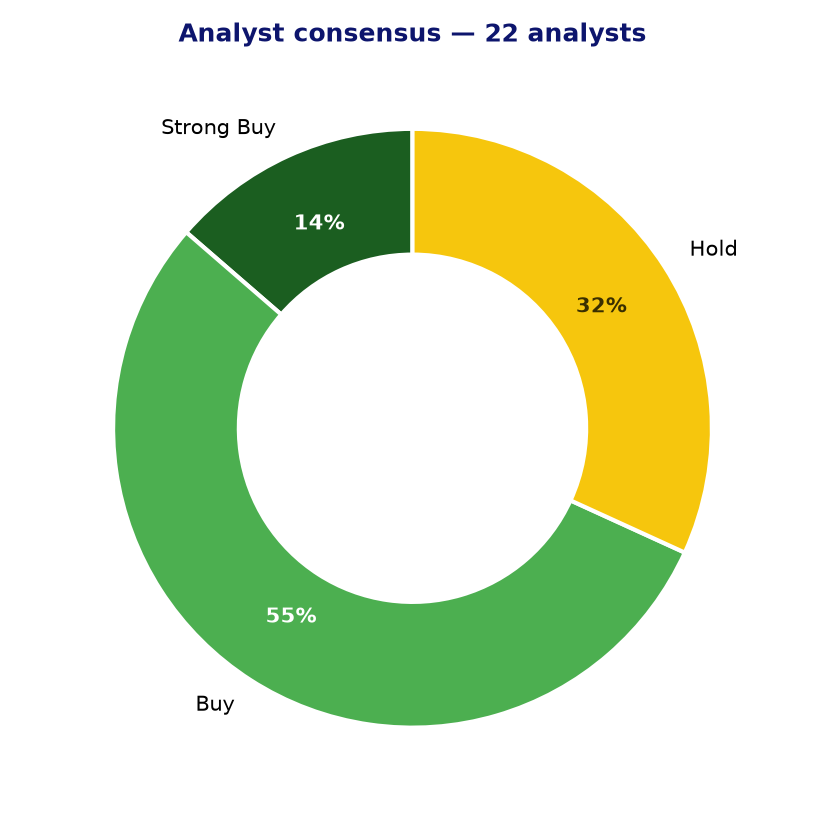
- Analyst sentiment remains broadly constructive: of 22 analysts covering the stock, 15 rate it Buy or Strong Buy, with no sell ratings, and the average price target of $449.10 implies approximately 11.5% upside from the current price of $402.63.
- The 24-month Z-score momentum reading of 2.03 indicates that the stock has shown meaningful relative price strength over the medium term, suggesting underlying investor interest despite recent volatility.
- With a forward P/E of 13.6x, the stock trades at a meaningful discount to its trailing P/E of 17.8x, reflecting market expectations of earnings recovery and potentially offering an attractive entry point if margins stabilise.
- Elevance’s diversified business model — spanning insurance, pharmacy services, and care management — provides multiple revenue streams and reduces dependence on any single segment or product line.
- The company’s scale and established brand presence across Blue Cross and Blue Shield markets provide significant competitive advantages in member retention and contract negotiations with healthcare providers.
Points of attention and risks
- Earnings per share fell materially year-on-year in Q2 2026, from $8.84 to $7.45, and the negative EPS growth figure of -0.16 signals that profitability is currently under pressure rather than expanding.
- Margin compression in the Health Benefits segment is an ongoing concern, and management’s own commentary on the results was cautious enough to drag down share prices across the broader managed care sector.
- The PEG ratio of 1.42, while not extreme, suggests the stock is not obviously cheap relative to near-term growth prospects, particularly given the current earnings trajectory.
- Analyst opinions are notably mixed, and the wide price target range of $393 to $492 reflects genuine uncertainty about the pace and magnitude of any margin recovery.
- Structural headwinds in managed care — including elevated medical cost ratios, Medicaid redetermination pressures, and regulatory uncertainty around Medicare Advantage — represent sector-level risks that are difficult for any individual company to fully insulate against.
Analyst consensus and price targets
Conclusion
Elevance Health presents a picture of a fundamentally large and diversified healthcare business navigating a difficult near-term period of margin compression, with earnings declining year-on-year and the Health Benefits segment under visible pressure. At the same time, the forward valuation looks more reasonable than the trailing multiple suggests, analyst coverage remains majority-positive, and the price target consensus points to moderate upside if the company can demonstrate a credible path to margin recovery. Investors will want to monitor upcoming earnings carefully for evidence that medical cost trends are stabilising before drawing firm conclusions about the durability of any improvement.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 24-08-2026. Not investment advice.