
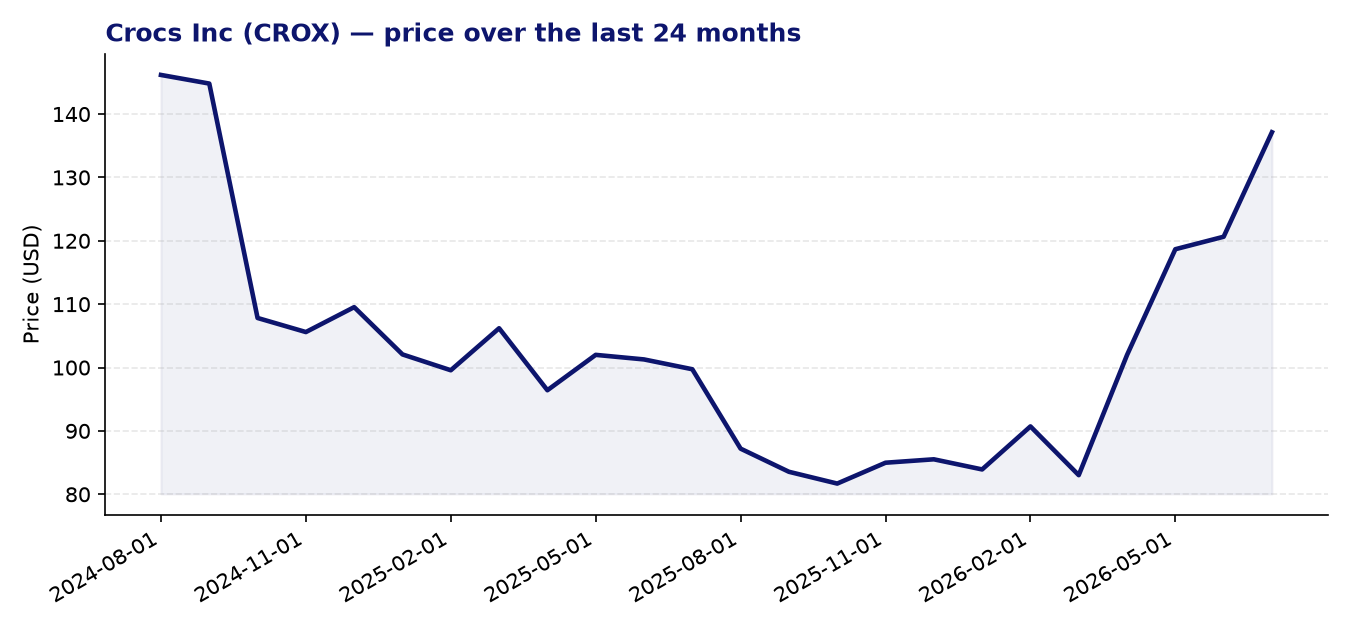
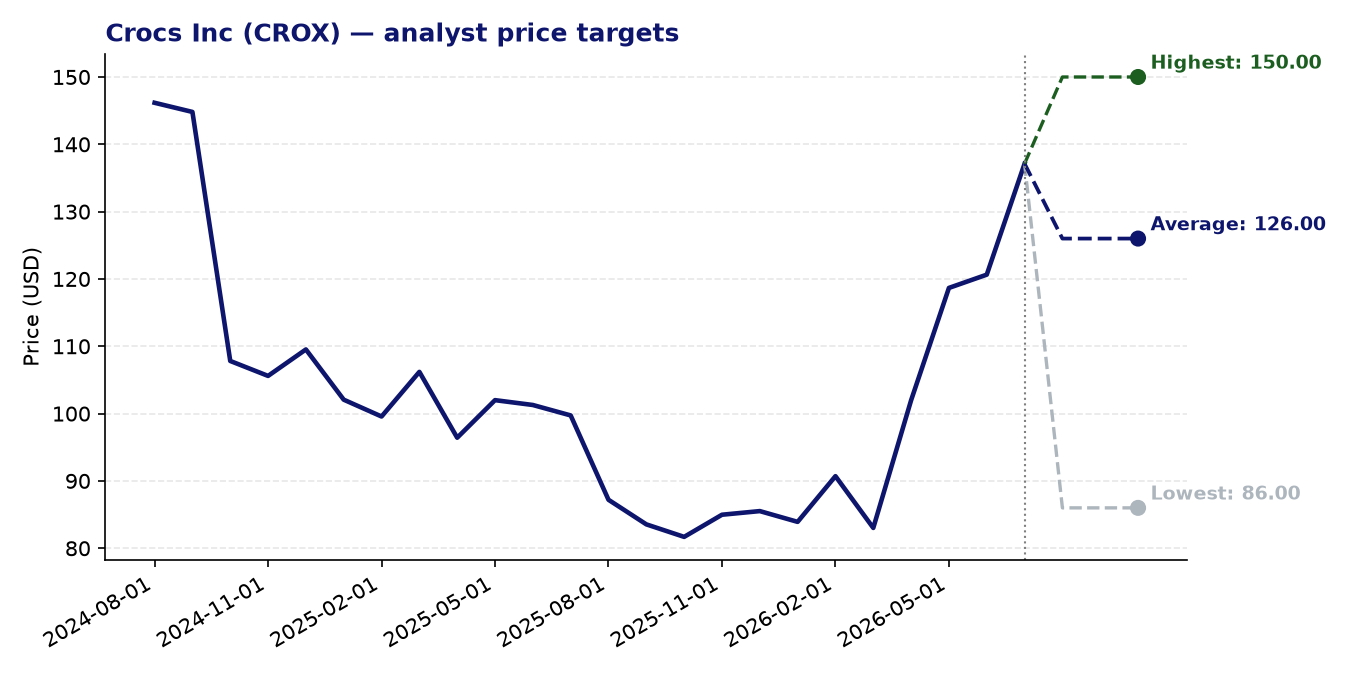
Crocs Inc (CROX) — current price: 137.13 USD | average price target: 126.00 USD | potential: -8.1%
About Crocs Inc
- Crocs, Inc. designs, markets, and sells casual footwear and accessories for men, women, and children under two brands: the flagship Crocs brand and the acquired HEYDUDE brand.
- Its product range spans clogs, sandals, boots, sneakers, slippers, and a growing accessories line including bags, charms, and socks.
- The company distributes globally through wholesale partners, its own retail and outlet stores, e-commerce platforms, and third-party marketplaces.
- Founded in 1999 and headquartered in Broomfield, Colorado, Crocs has grown from a niche clog maker into a multi-brand casual footwear group with significant international reach.
Recent news
- Q1 2026 revenue declined approximately 1.7% year-over-year, though results still came in ahead of analyst expectations, raising questions about the durability of the growth story.
- Analysts recently revised Crocs’ fair value estimate upward to around $126, citing improving prospects for the North America segment and a nascent recovery at the HEYDUDE brand.
- The stock has underperformed the broader market on several recent trading sessions, reflecting investor caution around slowing topline momentum.
- A bullish investment thesis circulating in financial media highlights the company’s strong margins and active share-buyback programme as key supports for the valuation.
Strengths
- The forward P/E of 9.44x is undemanding for a branded consumer company, suggesting the market may already be pricing in a meaningful degree of pessimism.
- The 24-month Z-score momentum reading of 2.68 indicates the stock has shown statistically significant positive price momentum relative to its own history.
- Crocs operates with notably strong profit margins, and the company has been actively returning capital to shareholders through share buybacks, which provides some earnings-per-share support.
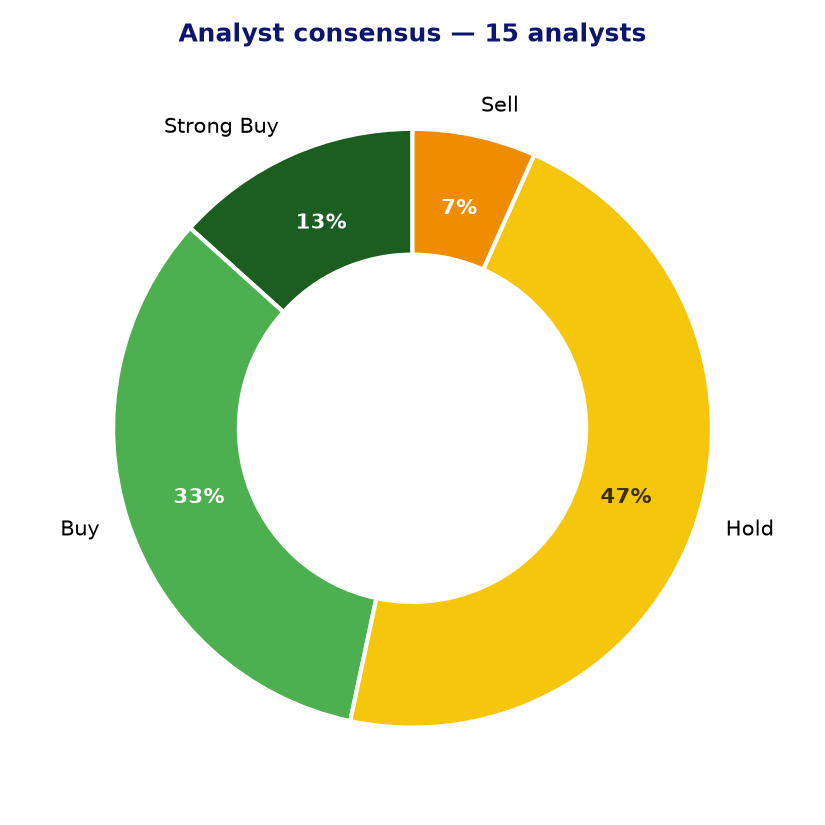
- Analyst sentiment remains broadly constructive: of 15 covering analysts, seven hold buy or strong-buy ratings, and the highest price target stands at $150.
- The HEYDUDE brand, which has faced near-term headwinds, is showing early signs of stabilisation, and a recovery there could provide an additional growth avenue.
Points of attention and risks
- At the current price of $137.13, the stock trades above the average analyst price target of $126.00, implying approximately 8% downside to consensus fair value — an unusual positioning.
- Revenue growth has stalled, with Q1 2026 sales declining year-over-year, and negative EPS growth of -0.14 raises questions about near-term earnings trajectory.
- The PEG ratio of 1.39, combined with contracting earnings, suggests the valuation may not be as straightforward a bargain as the headline forward P/E implies.
- The company remains heavily dependent on the core Crocs clog silhouette; any shift in consumer taste or fashion cycles poses a concentration risk.
- HEYDUDE continues to be a drag on consolidated results, and its recovery timeline remains uncertain, adding execution risk to the investment case.
Analyst consensus and price targets
Conclusion
Crocs presents a mixed picture: a well-known brand with genuine pricing power, solid margins, and an undemanding forward earnings multiple, offset by stalling revenue growth, negative EPS momentum, and a share price that currently sits above the analyst consensus target. The HEYDUDE recovery and ongoing buybacks could provide catalysts, but investors would need to weigh these against the real possibility that growth headwinds persist longer than the market currently anticipates. The stock may suit patient investors comfortable with cyclical consumer exposure, but the near-term risk-reward appears finely balanced at current levels.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 19-07-2026. Not investment advice.