
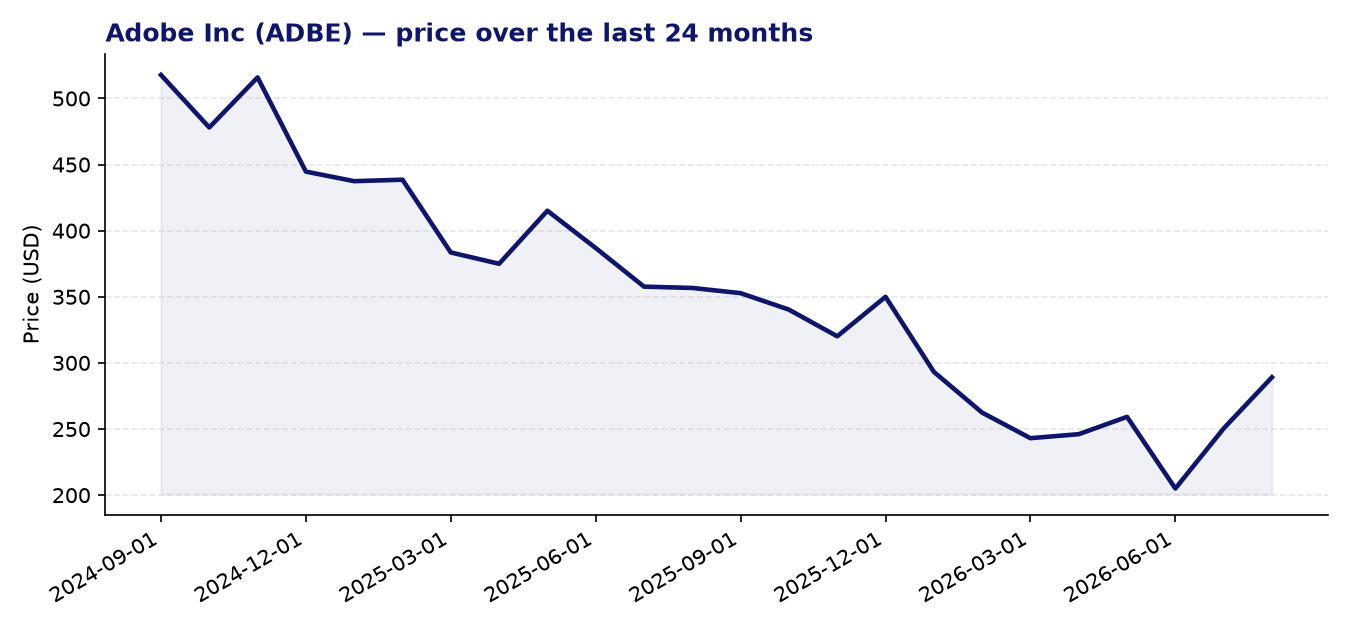
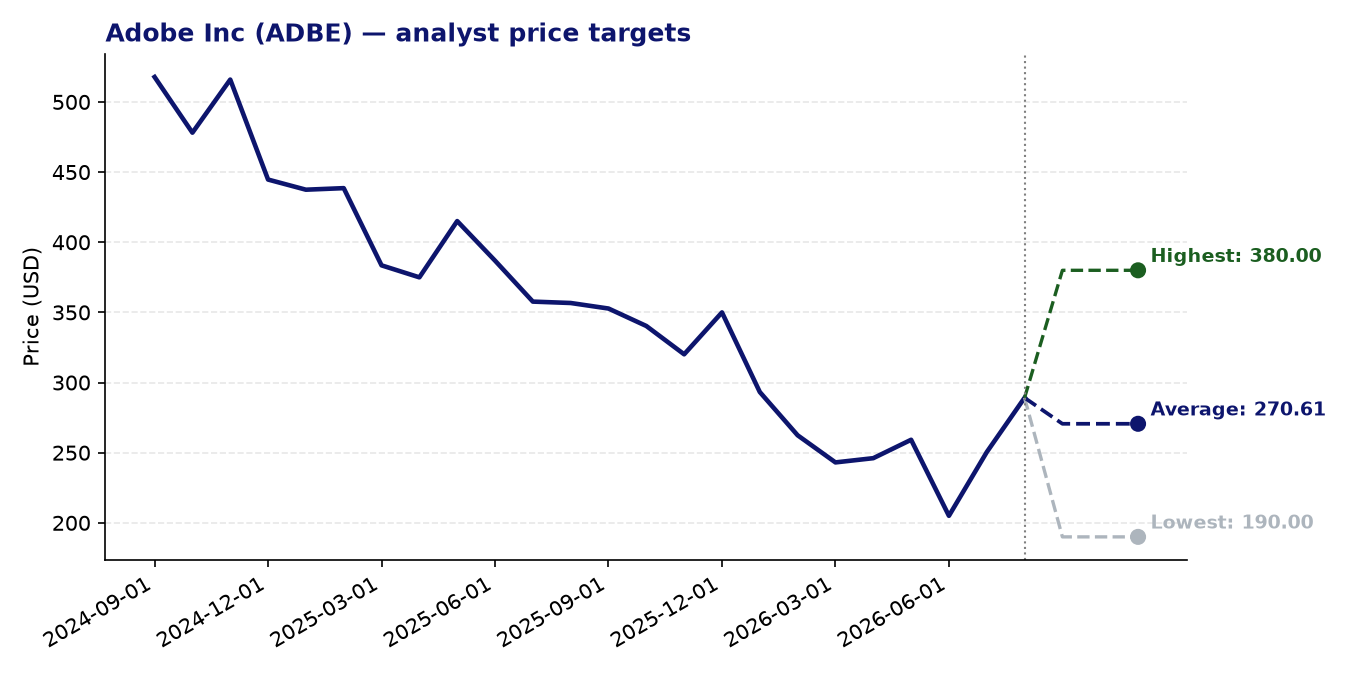
Adobe Inc (ADBE) — current price: 289.15 USD | average price target: 270.61 USD | potential: -6.4%
About Adobe Inc
- Adobe Inc. is a global software company founded in 1982 and headquartered in San Jose, California, serving individuals, enterprises, and creative professionals across more than 100 countries.
- Its Digital Media segment powers content creation and publishing through widely used tools such as Creative Cloud, catering to photographers, video editors, designers, and marketers.
- The Digital Experience segment delivers an integrated platform for analytics, commerce, and customer experience management, targeting brands, agencies, and data-driven enterprises.
- A Publishing and Advertising segment rounds out the portfolio with e-learning, document management, web conferencing, and advertising technology solutions.
- Adobe has a strategic alliance with HUMAIN focused on developing generative AI models and AI-powered applications, positioning it at the frontier of AI-driven creative workflows.
Recent news
- Morgan Stanley downgraded Adobe to ‘underweight’ in late July 2026 and reduced its price target, contributing to a single-session share decline of around 3.5%, reflecting ongoing concern about AI-driven competitive disruption to Adobe’s core creative tools.
- Phillip Securities separately moved its rating to ‘neutral’ in late June 2026, adding to a broader pattern of analyst caution heading into the second half of the year.
- A Seeking Alpha analysis argued that market fears over AI disruption are overdone, pointing to Adobe’s valuation of roughly 10x forward earnings and strong cash generation as evidence that the bear case may already be priced in.
- Investors are watching Adobe’s Q3 2026 earnings report closely, with cloud segment growth seen as a key indicator of whether the company can sustain momentum across its Creative Cloud, Document Cloud, and Experience Cloud businesses.
Strengths
- Valuation metrics appear undemanding relative to Adobe’s quality: a forward P/E of around 10.5x and a PEG ratio of 0.67 suggest the market is pricing in limited growth expectations, which may understate the company’s long-term earnings power.
- The 24-month Z-score momentum reading of 2.32 indicates that the stock has shown meaningful price momentum relative to its own history, a positive technical signal for trend-oriented investors.
- Adobe’s three-cloud structure — Creative, Document, and Experience — gives it diversified, largely recurring subscription revenue, providing relative revenue stability compared with more cyclical software peers.
- The strategic alliance with HUMAIN for generative AI development positions Adobe to integrate AI capabilities directly into its workflows rather than being displaced by them, a potentially significant competitive advantage.
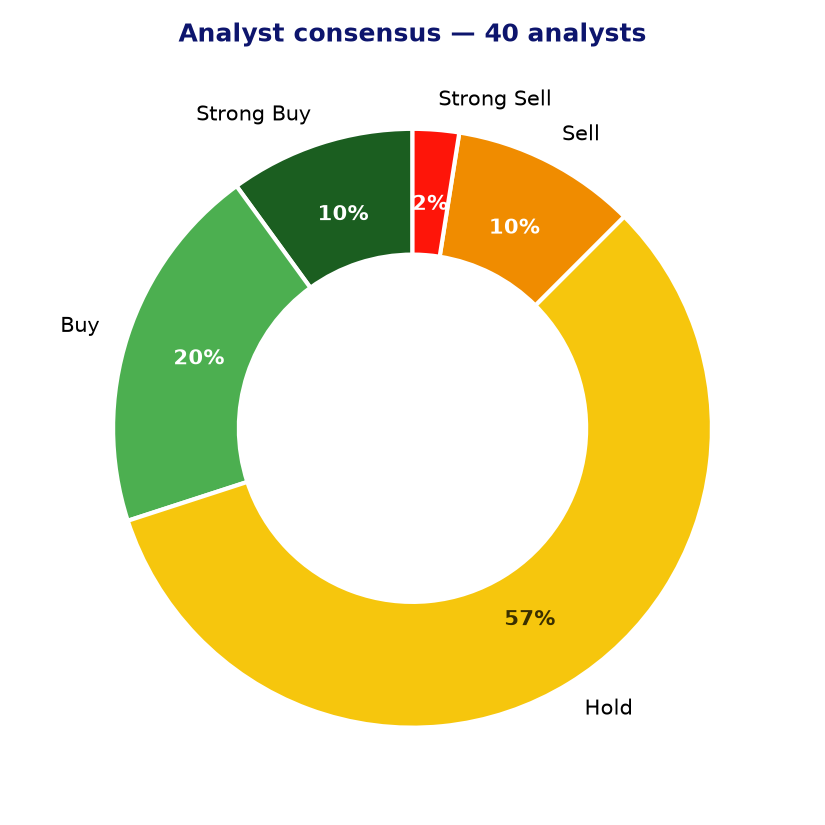
- Among 40 covering analysts, 12 carry buy or strong buy ratings, and the wide price-target range (up to $380) reflects meaningful upside potential in more optimistic scenarios.
Points of attention and risks
- The average analyst price target of $270.61 sits approximately 6.4% below the current share price of $289.15, meaning the consensus view implies the stock is modestly overvalued at current levels.
- The analyst consensus skews cautiously, with 23 hold ratings, 4 sells, and 1 strong sell out of 40 analysts — a distribution that does not reflect broad conviction in near-term outperformance.
- Two notable broker downgrades within a short window (Morgan Stanley to ‘underweight’ and Phillip Securities to ‘neutral’) signal that institutional sentiment has been softening, which can weigh on share price.
- EPS growth of effectively zero in the most recent period raises questions about near-term earnings momentum, even if the forward multiple looks attractive on an absolute basis.
- Competitive risk from AI-native creative tools and platform entrants remains a genuine structural concern, particularly for the Digital Media segment, where barriers to entry may be lower than in the past.
Analyst consensus and price targets
Conclusion
Adobe’s core franchises remain defensible and its valuation, on a forward basis, looks reasonable relative to its cash-generative business model and AI integration efforts. However, the combination of a consensus price target below the current price, a dominant ‘hold’ rating distribution, and two recent broker downgrades suggests that near-term catalysts may be needed to re-rate the stock higher. Investors may find the long-term AI positioning and recurring revenue profile attractive, but the absence of strong near-term earnings momentum and the current level of analyst caution merit careful consideration before adding exposure.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 27-08-2026. Not investment advice.