
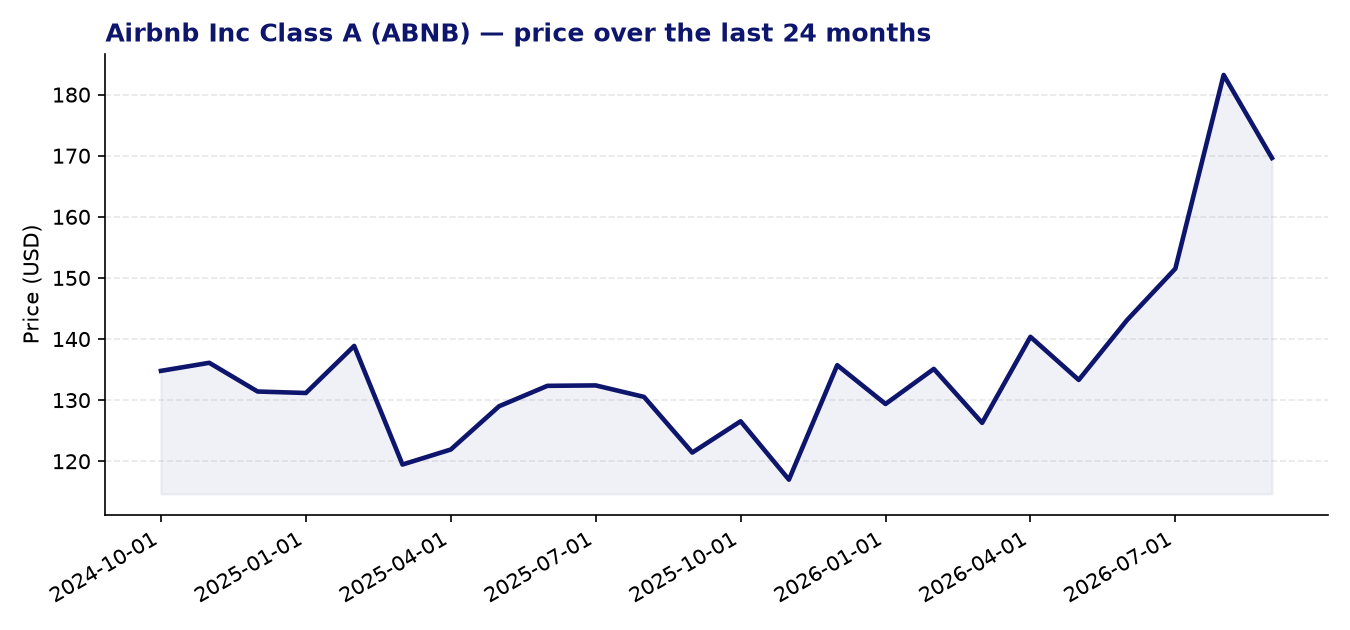
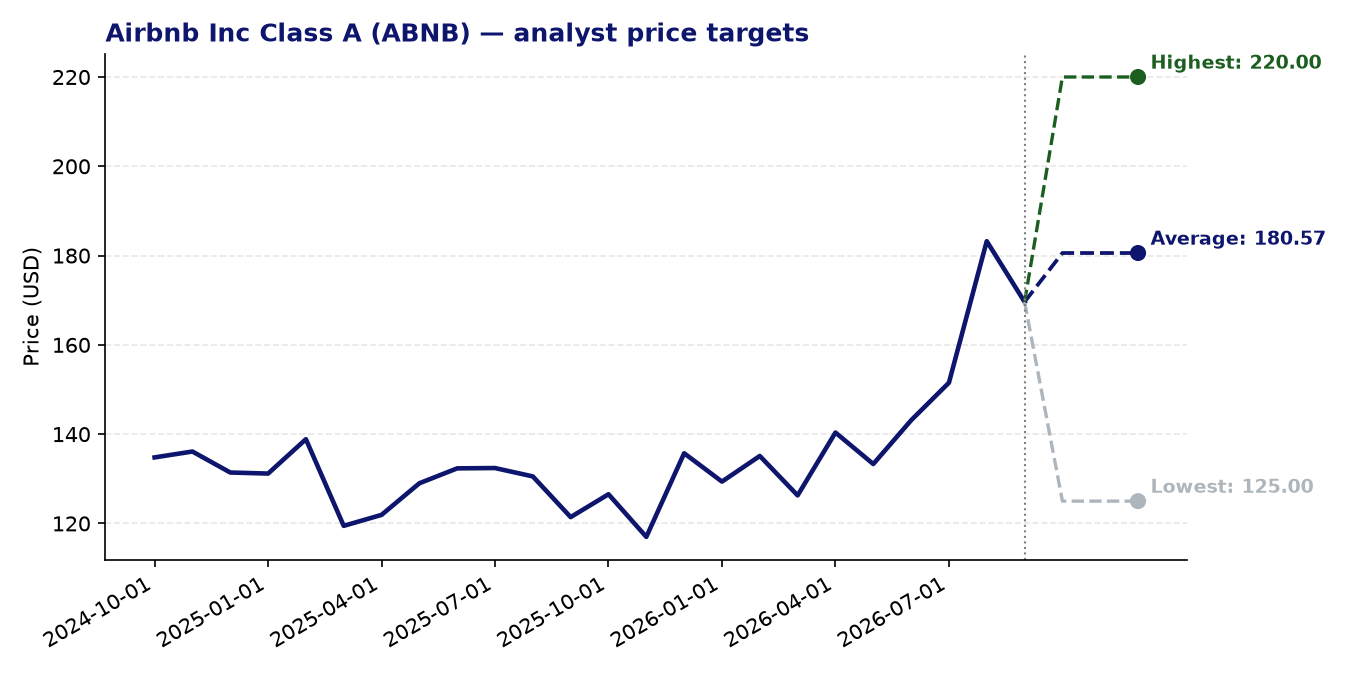
Airbnb Inc Class A (ABNB) — current price: 169.63 USD | average price target: 180.57 USD | potential: +6.5%
About Airbnb Inc Class A
- Airbnb operates a global online marketplace connecting hosts and guests seeking short-term accommodation, unique stays, and local experiences.
- The platform is accessible via web and mobile, enabling hosts to list properties and guests to book everything from spare rooms to entire homes worldwide.
- Founded in San Francisco in 2007, Airbnb has grown from a simple air-mattress rental concept into one of the largest travel platforms in the world.
- The company also offers gift cards and continues to invest in platform features, including AI-powered customer support tools.
Recent news
- Airbnb’s Q2 2026 results meaningfully exceeded expectations, with revenue up 17% year-on-year, ahead of the company’s own 14–16% guidance range, while adjusted EBITDA rose 21% and EPS of $1.37 beat the consensus estimate of $1.20.
- Room night growth accelerated to 10% from 9% in the prior quarter, and management raised full-year revenue growth guidance to at least mid-teens, from the prior low-to-mid-teens outlook.
- Shares hit a fresh 52-week high of $184.70 in the days following the earnings release, reflecting a strong post-results advance of around 10% before some subsequent consolidation.
- BMO Capital raised its price target on Airbnb to $165 from $146 in early October, citing confidence in the company’s trajectory, though the stock has since traded above that revised target.
Strengths
- Q2 2026 earnings demonstrated clear operational momentum, with revenue growth accelerating beyond guidance and adjusted EBITDA expanding at an even faster pace, suggesting improving operating leverage.
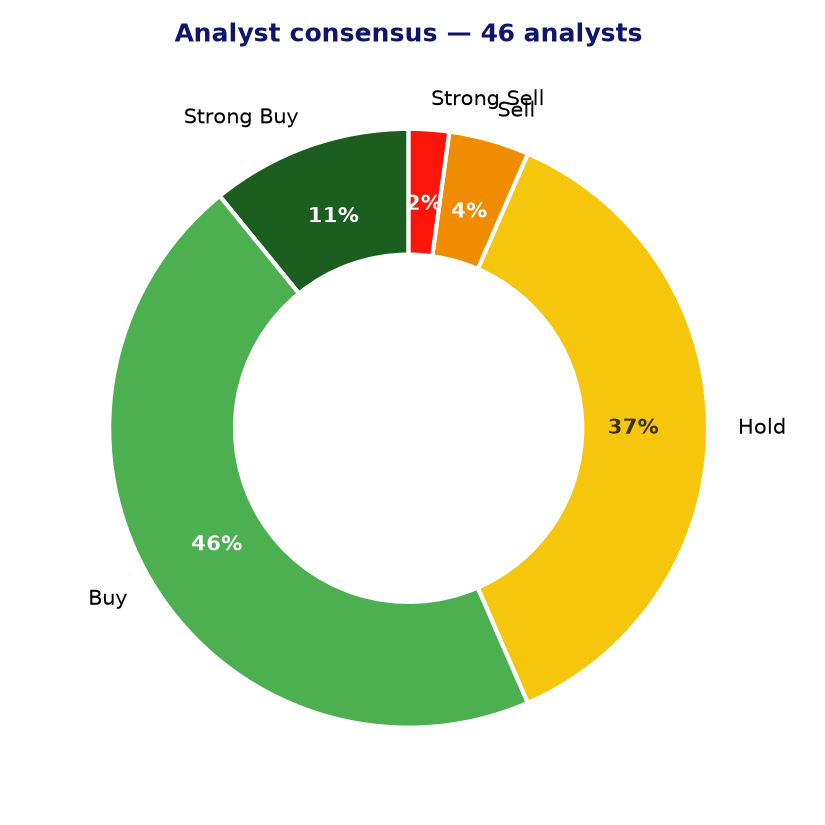
- The analyst community remains broadly constructive: of 46 analysts, 26 carry a buy or strong buy rating, with an average price target of $180.57, implying approximately 6.5% upside from the current price of $169.63.
- A 24-month Z-score momentum reading of 2.33 indicates that the stock has exhibited meaningfully positive price momentum relative to its own history, which can reflect sustained investor confidence.
- Airbnb’s AI-assisted customer support now resolves more than 40% of queries without human intervention, reportedly reducing cost-per-booking by around 10% — a tangible efficiency gain that could support margins over time.
- The forward P/E of 27.58 represents a notable discount to the trailing P/E of 39.82, suggesting that earnings growth is expected to close the valuation gap relatively quickly if guidance is met.
Points of attention and risks
- At a trailing P/E of nearly 40 and a PEG ratio of 1.73, the stock is not inexpensive, leaving limited room for disappointment if growth expectations are not met consistently.
- The analyst price target range is unusually wide — from $125 to $220 — reflecting meaningful disagreement about the company’s fair value and the difficulty of forecasting its growth trajectory with confidence.
- Airbnb operates in the consumer cyclical sector, making its revenues sensitive to macroeconomic conditions, shifts in discretionary spending, and broader travel demand, all of which can deteriorate rapidly in a downturn.
- The company has missed earnings per share estimates in three of the four quarters prior to Q2 2026, according to pre-results commentary, raising questions about the consistency and predictability of its financial performance.
- Regulatory risk remains an ongoing concern, as municipalities worldwide continue to introduce or tighten restrictions on short-term rentals, which could constrain supply growth in key urban markets.
Analyst consensus and price targets
Conclusion
Airbnb’s Q2 2026 results and raised full-year guidance represent a genuine step forward, with accelerating top-line growth, expanding EBITDA, and early evidence that AI-driven efficiency gains are feeding through to the cost base. The broad analyst consensus leans positive, and momentum indicators support the recent share price strength. That said, the valuation remains elevated on a trailing basis, the wide dispersion of price targets signals uncertainty, and exposure to regulatory headwinds and consumer cyclicality are risks that investors should weigh carefully before forming a view on the stock.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 10-09-2026. Not investment advice.