
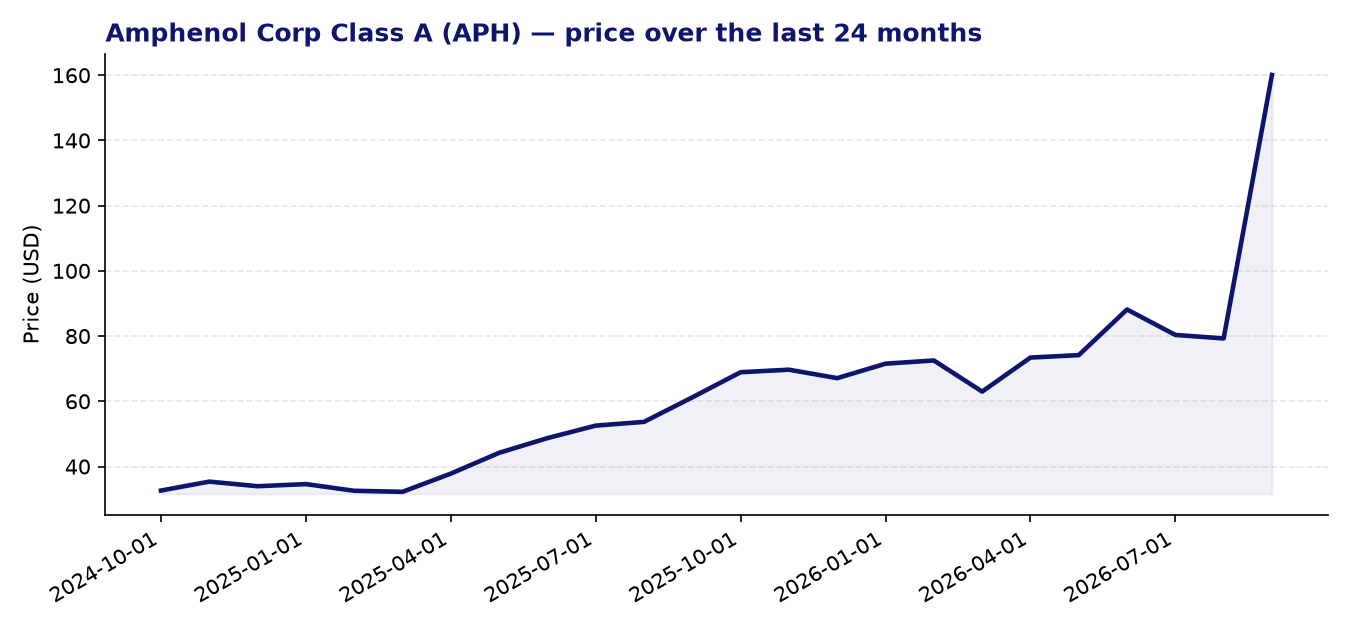
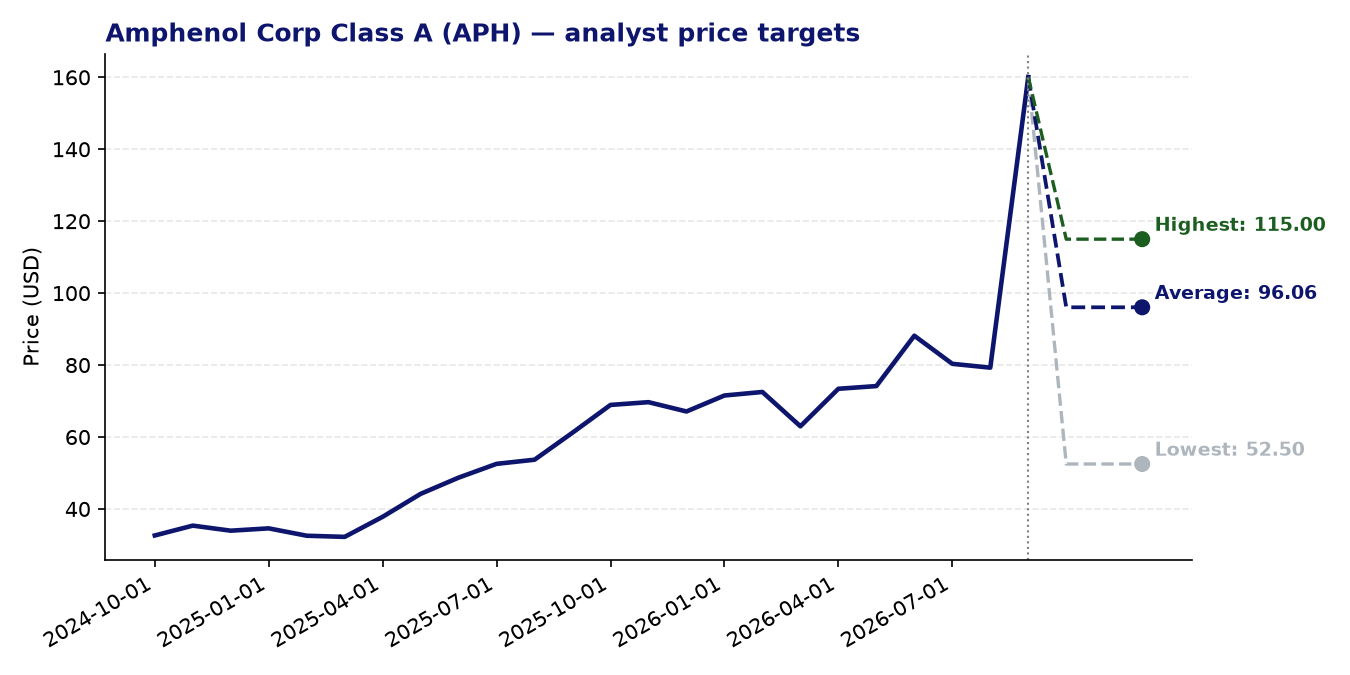
Amphenol Corp Class A (APH) — current price: 160.08 USD | average price target: 96.06 USD | potential: -40.0%
About Amphenol Corp Class A
- Amphenol Corporation, founded in 1932 and headquartered in Wallingford, Connecticut, designs, manufactures, and markets electrical, electronic, and fiber optic connectors for customers across the US, China, and global markets.
- The company operates through three segments: Communications Solutions, Harsh Environment Solutions, and Interconnect and Sensor Systems.
- Its product portfolio spans high-speed and radio frequency connectors, power distribution systems, cable assemblies, printed circuit boards, antennas, and sensor-based products.
- Amphenol serves a broad range of end markets including automotive, defense, commercial aerospace, data communications, mobile devices, and industrial applications.
- Products are sold through a direct sales force, independent representatives, and electronics distributors to OEMs, electronic manufacturing services companies, and major service providers worldwide.
Recent news
- In June 2026, Amphenol announced a two-for-one stock split alongside an update to its financial outlook, signaling management confidence in the company’s near-term trajectory.
- The stock split will double the number of shares outstanding while halving the share price proportionally, which may improve liquidity and broaden the stock’s accessibility to a wider range of investors.
- No other material company-specific news was identified in the recent period beyond the split announcement and outlook update.
Strengths
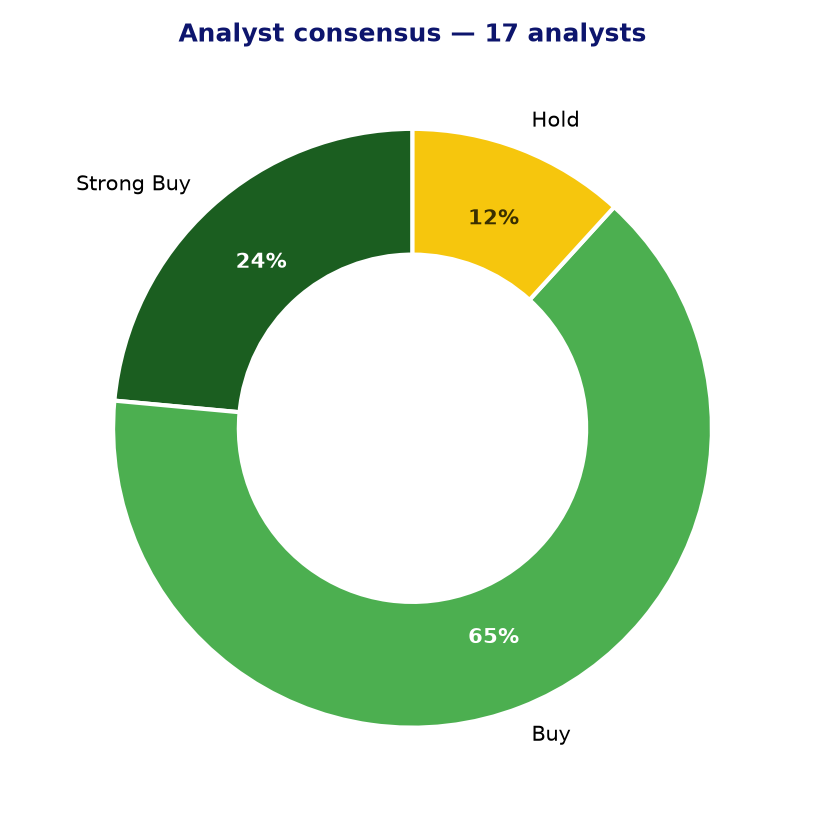
- Analyst sentiment is broadly constructive, with 15 out of 17 covering analysts rating the stock a buy or strong buy, reflecting wide confidence in Amphenol’s business model and growth prospects.
- The PEG ratio of 0.92 is below 1.0, which suggests that despite a headline P/E of 81.67, the market may not be fully accounting for the company’s expected earnings growth when assessed on a growth-adjusted basis.
- A 24-month Z-score momentum reading of 3.01 indicates that the stock has exhibited notably strong price momentum relative to its historical trend, which can be a positive signal for continued investor interest.
- Amphenol’s diversified end-market exposure — spanning defense, automotive, data communications, and AI-linked data infrastructure — provides resilience and multiple independent growth drivers.
- The two-for-one stock split and updated outlook suggest management is operating with a degree of confidence in near-term earnings visibility.
Points of attention and risks
- The current share price of $160.08 sits approximately 40% above the average analyst price target of $96.06, and even the highest individual price target of $115.00 represents a meaningful discount to where the stock currently trades — a significant red flag on valuation.
- The trailing P/E of 81.67 is elevated by most standards for an industrial-leaning technology company, leaving little room for earnings disappointment without a potentially sharp price correction.
- The forward P/E of 49.43, while lower, still implies very high expectations for earnings delivery, making the stock sensitive to any guidance revision or macro-driven demand slowdown.
- EPS growth of 0.62 (as a ratio) suggests that while growth is present, the pace may not fully justify the current premium multiple without sustained execution across all three business segments.
- Sector-specific risks include cyclicality in mobile devices and consumer electronics, potential defense budget pressures, and supply chain disruptions that could affect margins or delivery timelines.
Analyst consensus and price targets
Conclusion
Amphenol is a well-established, diversified connector and interconnect business with strong analyst support, genuine multi-market growth drivers, and solid price momentum. However, the current share price trades at a substantial premium to even the most optimistic analyst price targets, which is an unusual and noteworthy disconnect that warrants careful consideration. Investors who already hold the stock may find comfort in the company’s operational quality and diversified exposure, but those considering initiating a position should weigh the valuation gap carefully against their own assessment of the company’s long-term earnings potential.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 03-09-2026. Not investment advice.