
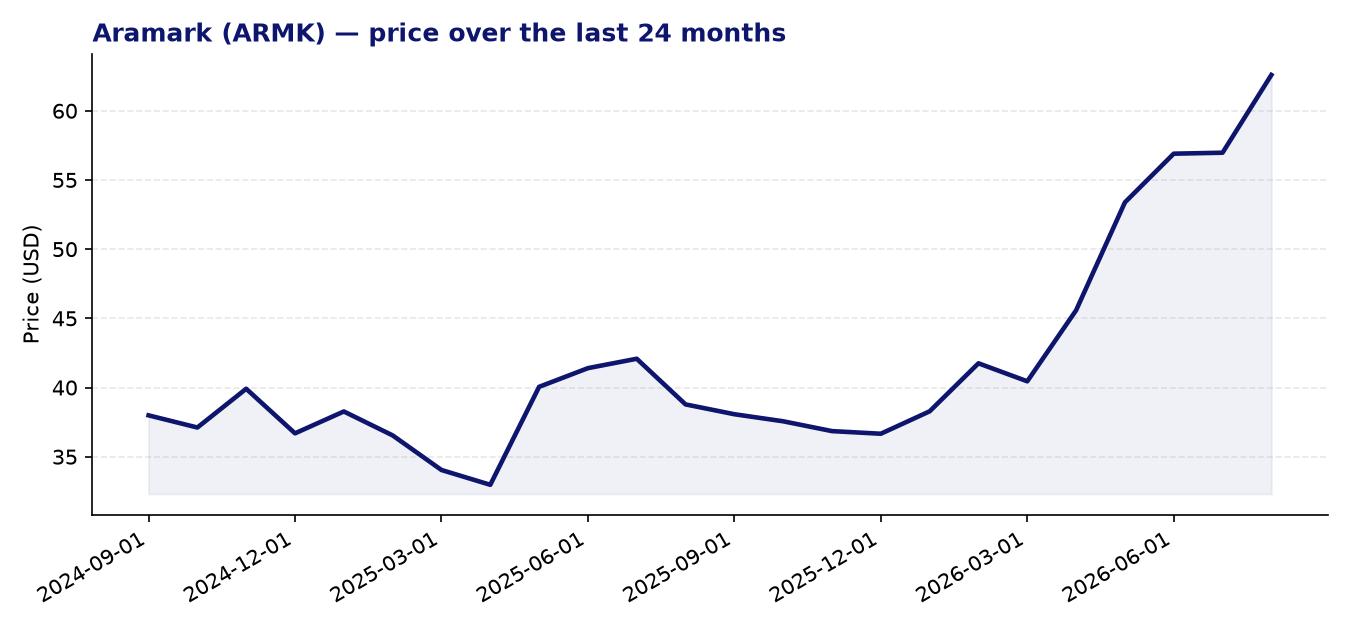
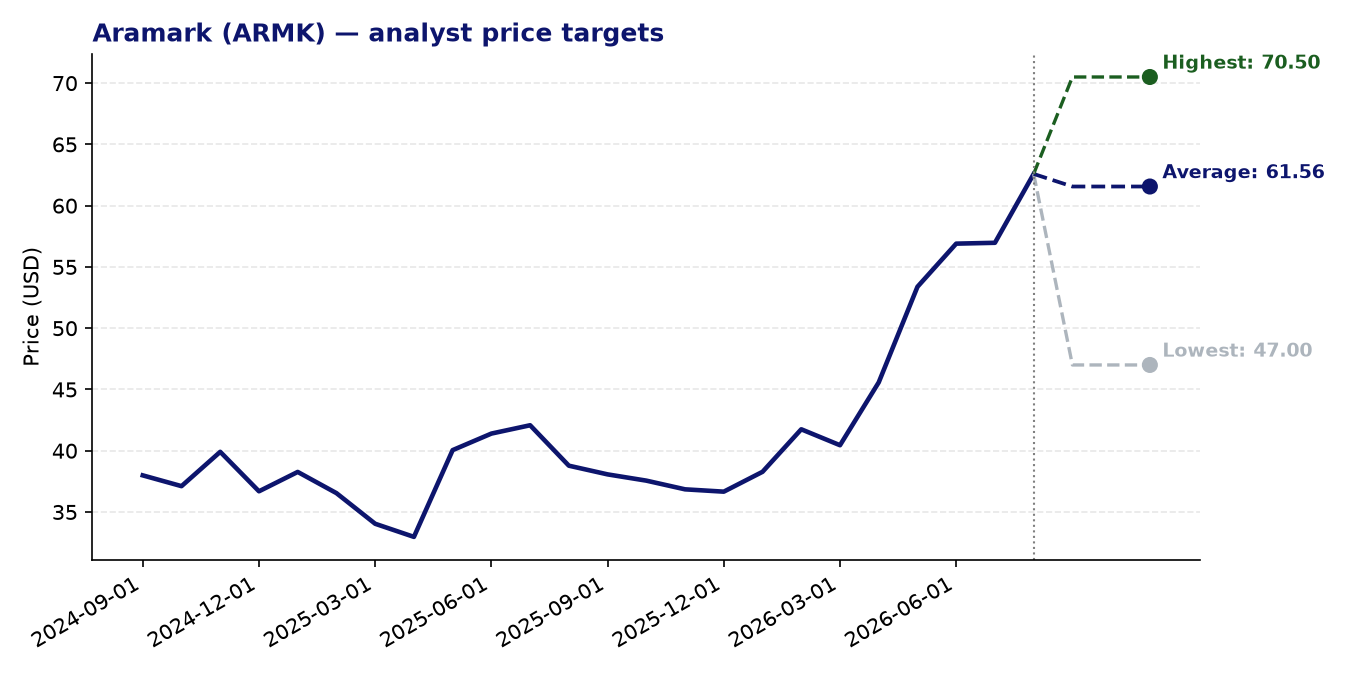
Aramark (ARMK) — current price: 62.59 USD | average price target: 61.56 USD | potential: -1.6%
About Aramark
- Aramark, founded in 1959 and headquartered in Philadelphia, is a large-scale provider of food and facilities management services across the United States and internationally.
- The company serves a broad range of clients including educational institutions, hospitals, corporate offices, sports and entertainment venues, and correctional facilities.
- Its food services encompass dining, catering, food service management, patient nutrition, and convenience retail, while its facilities services include custodial, grounds maintenance, energy management, and capital project oversight.
- Aramark also operates concessions, retail, and lodging services at sports and recreational facilities, and runs commissaries and laundry operations within the corrections segment.
Recent news
- Aramark reported fiscal third-quarter 2026 adjusted earnings of $0.52 per share, comfortably ahead of the consensus estimate of $0.48 and up meaningfully from $0.40 in the same quarter a year earlier.
- Net income for the fiscal third quarter came in at $97.7 million, reflecting continued operational progress across the business.
- Ahead of the Q3 release, analysts had noted that Aramark had already beaten revenue expectations in the prior quarter, setting a positive tone for the latest results.
- Aramark’s stock had gained approximately 51% over a six-month period leading into mid-July 2026, reaching a new 52-week high of $58.30, with fair value questions beginning to surface among commentators as a result.
Strengths
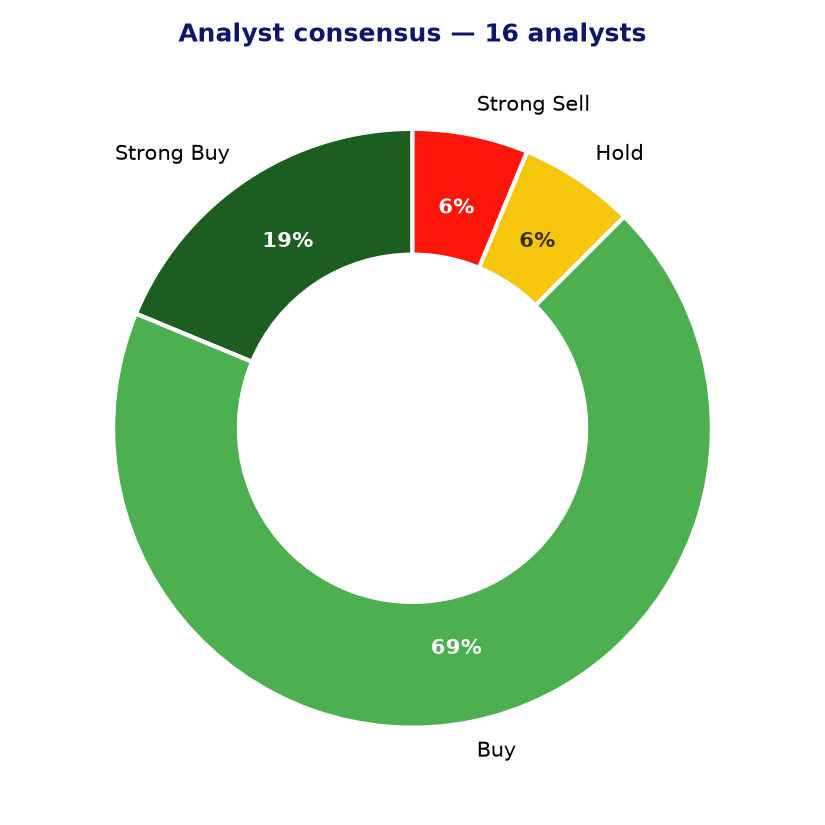
- The analyst community remains broadly constructive, with 14 out of 16 covering analysts holding a buy or strong buy rating, reflecting confidence in Aramark’s medium-term earnings trajectory.
- The PEG ratio of 0.89 suggests that the current valuation may be reasonable relative to expected earnings growth, even though the trailing P/E of 43.77 appears elevated at first glance.
- The forward P/E of 22.46 is considerably more modest than the trailing multiple, indicating that earnings are expected to grow substantially in the near term.
- A 24-month Z-score momentum reading of 2.19 points to sustained positive price momentum, suggesting the stock has exhibited consistent relative strength over the period.
- Strong and consistent earnings beats, including the latest quarter’s outperformance, indicate that management has been effective at delivering against market expectations.
Points of attention and risks
- At the current price of $62.59, the stock is trading approximately 1.6% above the average analyst price target of $61.56, meaning the consensus view implies limited near-term upside at current levels.
- The trailing P/E of 43.77 is high for an industrials and business services company, and any disappointment in earnings growth could weigh on a valuation that is pricing in continued improvement.
- The wide gap between the lowest ($47.00) and highest ($70.50) price targets among analysts highlights genuine uncertainty about the appropriate valuation range for the stock.
- Aramark operates in competitive, contract-driven markets with thin margins; cost inflation in food inputs, labour, and energy remains an ongoing sector-level risk that could pressure profitability.
- One analyst carries a strong sell rating, and the stock’s sharp run-up of over 50% in six months may have pulled forward some of the longer-term return potential, warranting careful attention to entry levels.
Analyst consensus and price targets
Conclusion
Aramark presents a broadly positive operational picture, with consistent earnings beats, a supportive analyst consensus, and a PEG ratio that suggests the growth story is not excessively priced in on a forward basis. However, the stock has already had a strong run and is currently trading marginally above the average analyst price target, which limits the apparent near-term upside and calls for measured expectations. Investors should weigh the company’s durable, diversified service model and improving earnings trajectory against the elevated trailing valuation and the sector’s inherent exposure to cost pressures.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 14-08-2026. Not investment advice.