
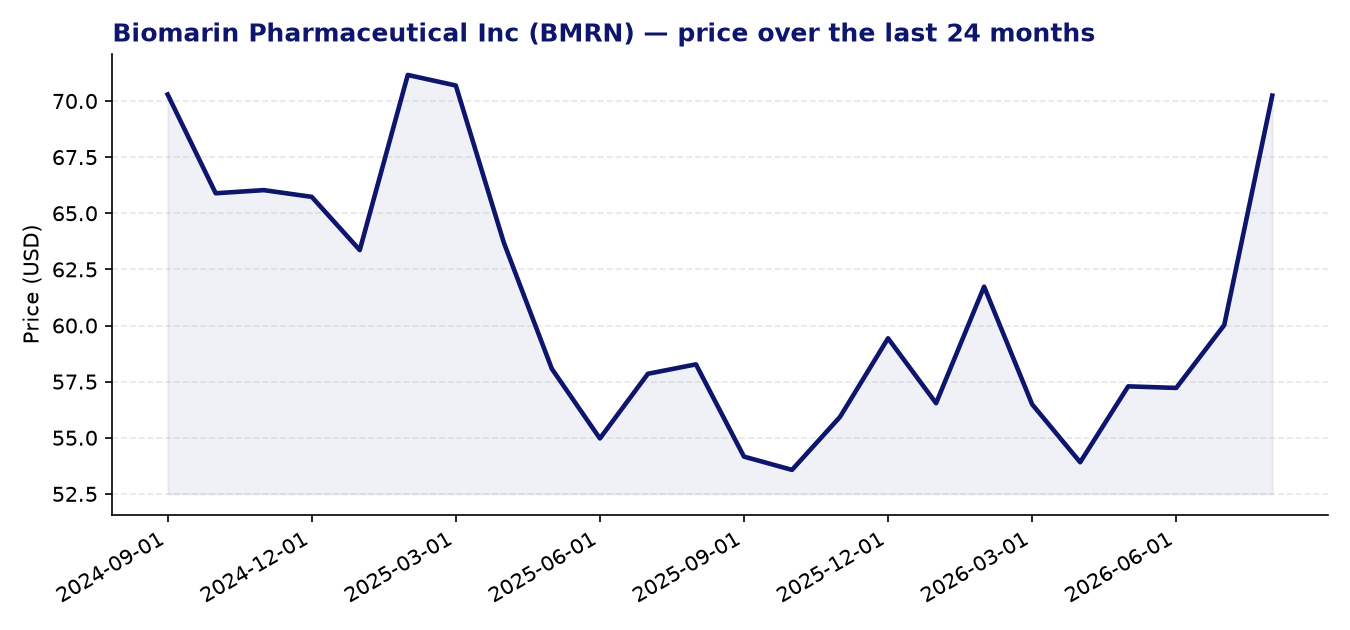
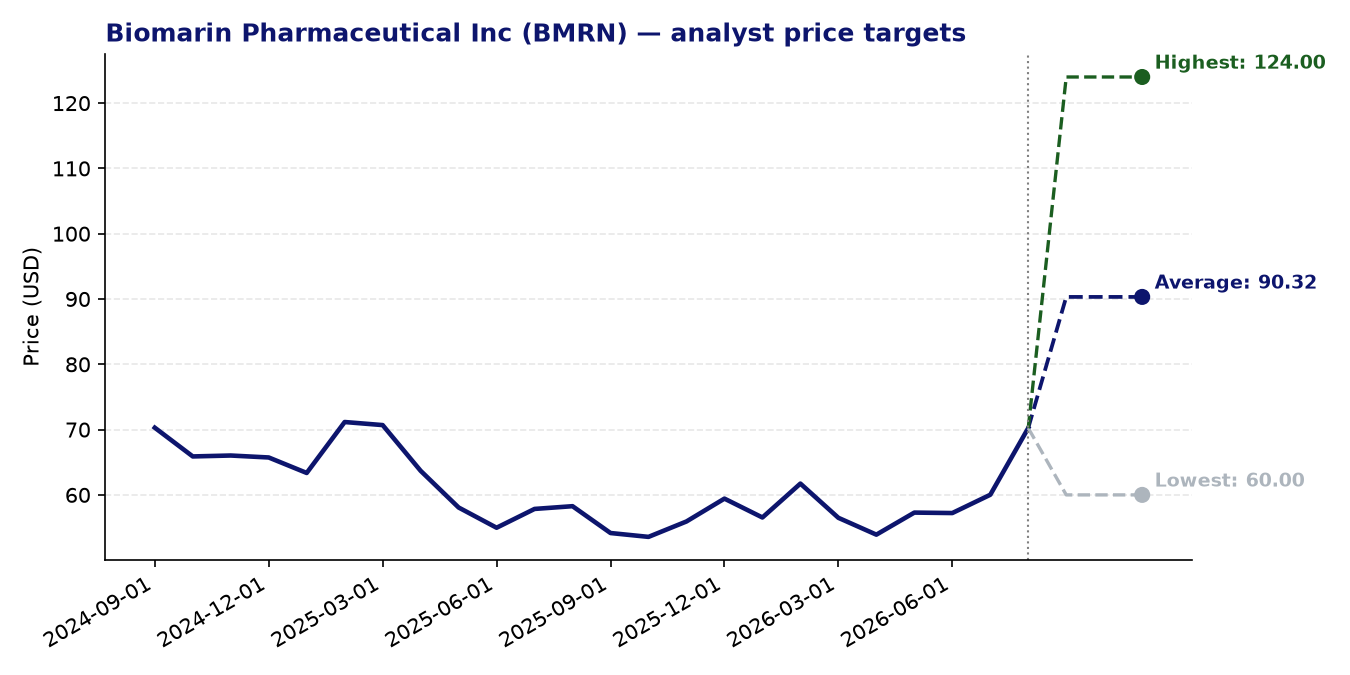
Biomarin Pharmaceutical Inc (BMRN) — current price: 70.24 USD | average price target: 90.32 USD | potential: +28.6%
About Biomarin Pharmaceutical Inc
- BioMarin Pharmaceutical is a US-based biotechnology company focused on developing and commercialising treatments for rare, life-threatening diseases, with a particular emphasis on enzyme replacement therapies and genetic disorders.
- Its commercial portfolio includes VIMIZIM and NAGLAZYME for mucopolysaccharidosis, PALYNZIQ and KUVAN for phenylketonuria, BRINEURA for Batten disease, and VOXZOGO for achondroplasia.
- VOXZOGO, a once-daily CNP analogue, has been a key growth driver, with patient numbers expanding steadily since its launch.
- The company’s pipeline includes BMN 333, a longer-acting CNP analogue targeting multiple growth disorders, and BMN 351, an oligonucleotide therapy for Duchenne muscular dystrophy.
- BioMarin serves specialty pharmacies, hospitals, government agencies, and pharmaceutical wholesalers across the US, Europe, Latin America, the Middle East, and Asia Pacific.
Recent news
- Ahead of its Q2 2026 results, analysts anticipated a year-over-year decline in earnings despite expectations for continued revenue growth, reflecting ongoing cost pressures.
- BioMarin published its second-quarter 2026 financial results in early August, following a first quarter in which revenues reached approximately $766 million, up year-over-year, supported by enzyme therapy growth of around 6% and continued VOXZOGO patient expansion, though a one-off $31 million manufacturing charge weighed on the quarter.
- Jefferies reaffirmed its Buy rating on BioMarin in October 2026, maintaining a price target of $104, signalling continued conviction among at least some sell-side analysts despite near-term earnings headwinds.
Strengths
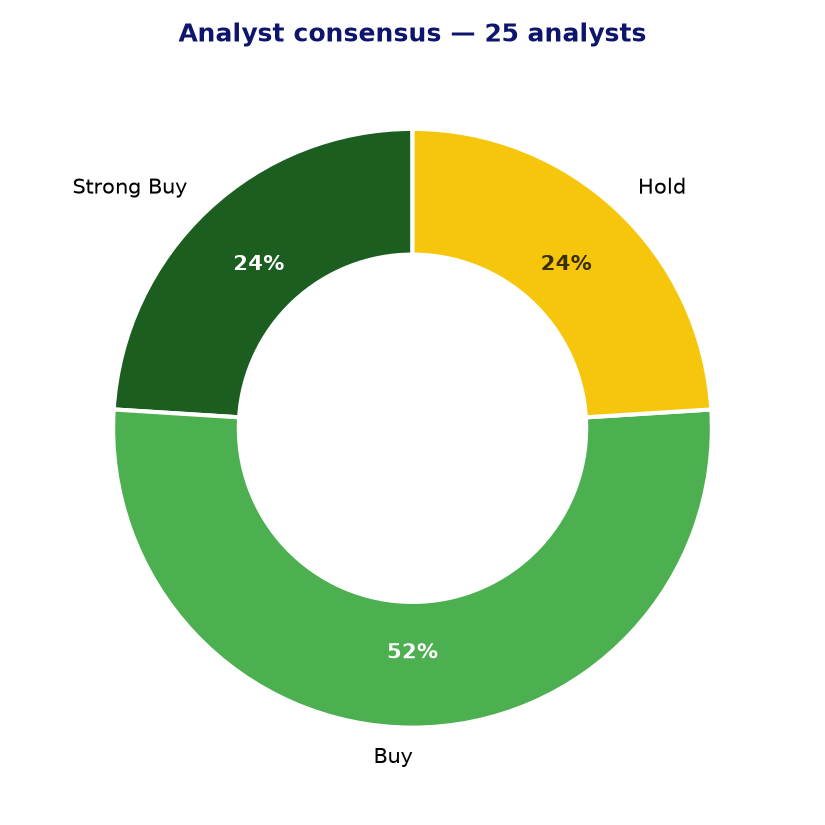
- Analyst sentiment is broadly constructive: 19 of 25 covering analysts rate the stock a Buy or Strong Buy, with an average price target of $90.32, implying roughly 29% upside from the current price of $70.24.
- The forward P/E of 10.6x is notably low for a rare-disease biotech, suggesting the market may be undervaluing the company’s medium-term earnings power relative to near-term noise.
- A PEG ratio of 0.86 indicates that growth expectations are not yet fully reflected in the valuation, which could be attractive if BioMarin executes on its pipeline and commercial targets.
- The 24-month Z-score momentum reading of 2.43 points to meaningful positive price momentum relative to historical norms, which can be a constructive technical signal.
- VOXZOGO continues to expand its patient base, and pipeline assets including BMN 333 and BMN 351 offer potential longer-term growth optionality in underserved disease areas.
Points of attention and risks
- The trailing P/E of 189.84x is very elevated, reflecting how thin current reported earnings are relative to the share price, and leaves little room for operational disappointment.
- EPS growth is currently negative (-0.81), and analysts projected a further year-over-year decline in Q2 2026 earnings, which may dampen near-term sentiment even if revenues are growing.
- A one-off $31 million manufacturing charge in Q1 2026 and order-timing variability illustrate the operational execution risks that can affect quarterly results in specialty biotech businesses.
- The wide spread between the lowest ($60) and highest ($124) analyst price targets reflects significant uncertainty about the company’s trajectory, with some analysts considerably more cautious than the consensus.
- As a rare-disease company, BioMarin is exposed to reimbursement and pricing pressures from government payers globally, as well as the inherent risk of pipeline setbacks in a competitive and highly regulated environment.
Analyst consensus and price targets
Conclusion
BioMarin presents an interesting combination of a deeply discounted forward valuation and broad analyst support, set against the backdrop of near-term earnings pressure and a lofty trailing multiple that underscores how much the investment case depends on future earnings delivery. The commercial portfolio is diversified across multiple rare diseases, and VOXZOGO’s growth trajectory alongside a developing pipeline provides a credible path to improved profitability. However, investors should weigh the current EPS decline, manufacturing execution risks, and the considerable divergence in analyst price targets before drawing conclusions about the risk-reward balance at current levels.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 12-08-2026. Not investment advice.