
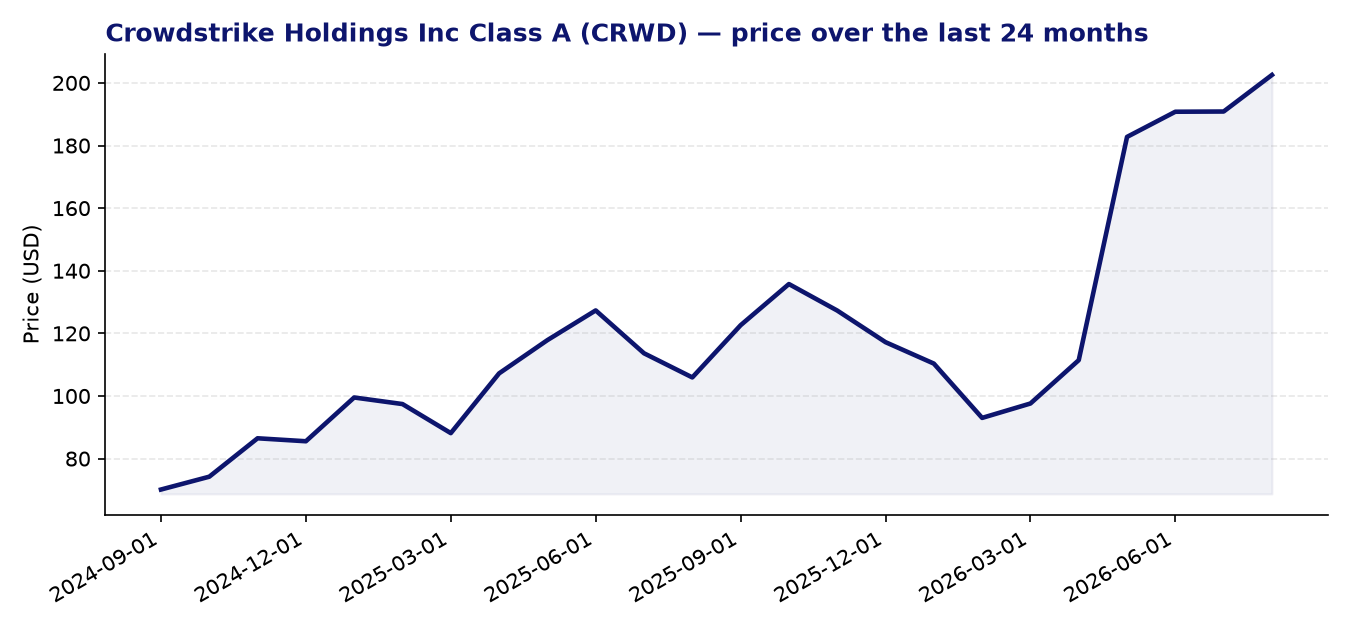
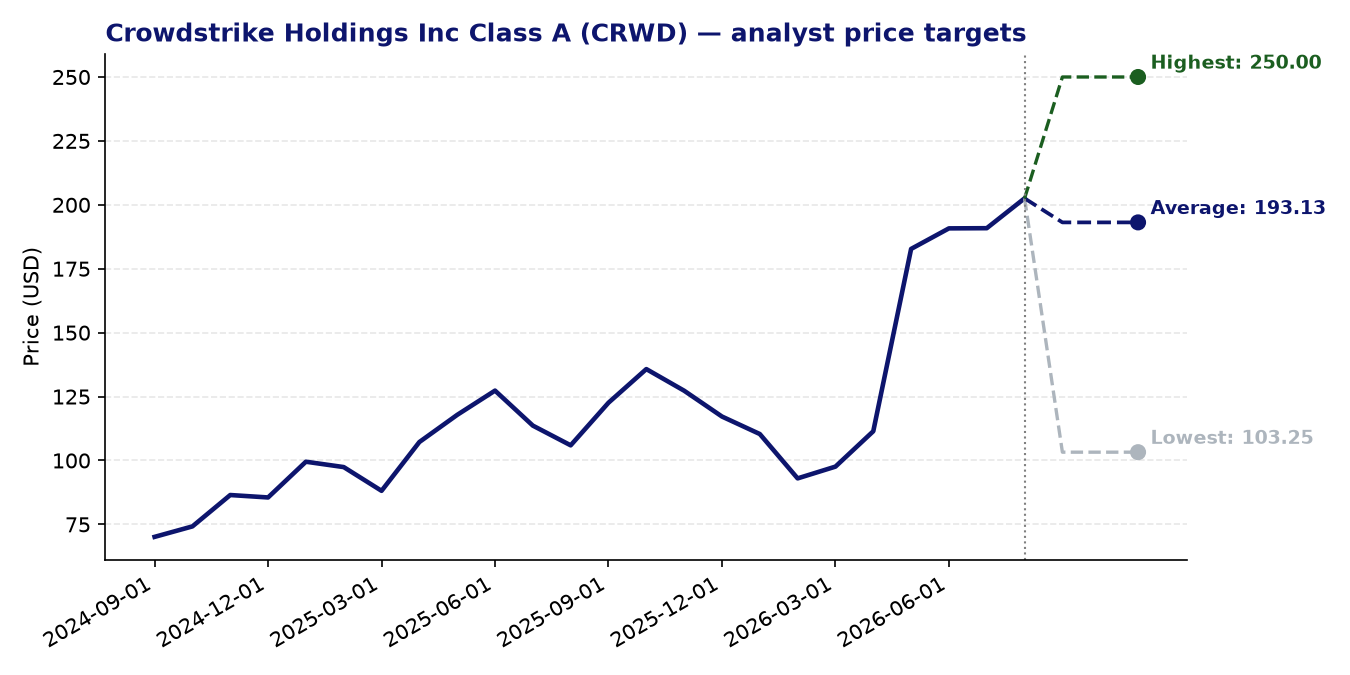
Crowdstrike Holdings Inc Class A (CRWD) — current price: 202.54 USD | average price target: 193.13 USD | potential: -4.6%
About Crowdstrike Holdings Inc Class A
- CrowdStrike provides cloud-native cybersecurity solutions through its Falcon platform, covering endpoint protection, cloud workload security, identity protection, and data security on a SaaS subscription basis.
- The company serves enterprise clients across the United States and internationally, offering a broad suite of services including threat intelligence, AI-powered workflow automation, and security information and event management.
- CrowdStrike has a strategic alliance with Cognizant Technology Solutions to help enterprises secure artificial intelligence systems across their full lifecycle.
- Founded in 2011 and headquartered in Austin, Texas, the company has grown into one of the most recognised names in the cybersecurity software sector.
Recent news
- CrowdStrike shares staged a notable three-day recovery in early August 2026, gaining around 6% on a single day to reach their highest close since mid-July, suggesting renewed investor interest after a period of weakness.
- The stock experienced several sessions of underperformance relative to the broader market in late July 2026, declining on days when major indices were flat to positive.
- First-quarter fiscal 2027 results, reported in early June 2026, showed revenue growth of 26% year-on-year to approximately $1.39 billion, with adjusted operating margins improving by five percentage points to 23.5% and annual recurring revenue reaching $5.51 billion.
- Despite a solid beat-and-raise quarter, the stock fell roughly 10% in the immediate aftermath of those earnings, a reaction analysts attributed to valuation concerns rather than any deterioration in the underlying business.
Strengths
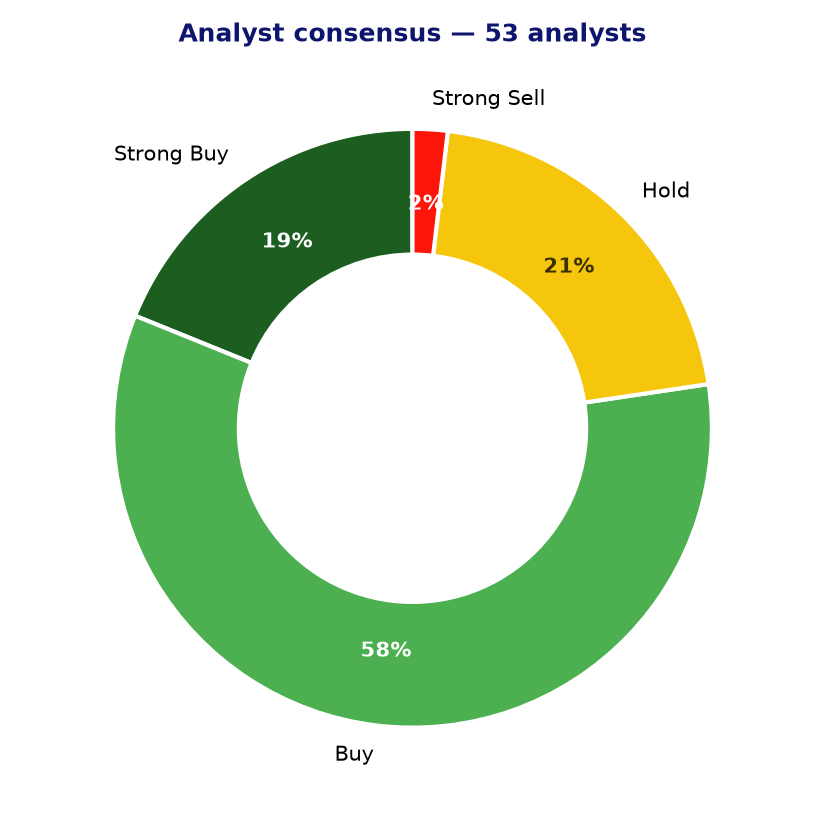
- Analyst sentiment remains broadly constructive, with 41 out of 53 covering analysts rating the stock either buy or strong buy, reflecting wide confidence in the company’s long-term positioning.
- Revenue growth of 26% and annual recurring revenue of $5.51 billion in the most recent quarter demonstrate that demand for CrowdStrike’s platform continues to expand at a meaningful pace.
- The 24-month Z-score momentum reading of 2.42 indicates that the stock has exhibited strong positive price momentum relative to historical norms, which can be a supportive technical signal.
- Growing enterprise interest in AI security and vendor consolidation trends play directly to CrowdStrike’s strengths as a broad, integrated platform provider rather than a point-solution vendor.
- Adjusted operating margins are expanding, suggesting the company is beginning to convert its revenue growth into improved profitability over time.
Points of attention and risks
- At a forward P/E of approximately 130x and a PEG ratio of 6.21, the valuation leaves very little room for execution shortfalls and implies sustained high growth for many years into the future.
- The average analyst price target of $193.13 currently sits roughly 4.6% below the prevailing share price, meaning the stock has, on consensus, already moved beyond where analysts collectively see fair value.
- The wide disparity between the lowest price target ($103.25) and the highest ($250.00) reflects genuine uncertainty about how to value the business, highlighting the inherent difficulty in forecasting high-growth software companies.
- The sharp post-earnings decline in June 2026, despite a strong quarterly result, illustrates how sensitive the stock price can be to any change in investor sentiment around growth expectations or macro conditions.
- The cybersecurity sector faces ongoing competitive intensity from both established technology giants and well-funded challengers, which could exert pressure on pricing and retention rates over time.
Analyst consensus and price targets
Conclusion
CrowdStrike presents a compelling operational picture, with strong revenue growth, rising margins, and a dominant position in a structurally growing market for AI-driven cybersecurity. However, the current valuation — with the stock trading above the average analyst price target and carrying a forward P/E above 130x — means investors are already pricing in a significant amount of future success, leaving limited margin of safety if growth were to moderate or sentiment were to shift. Investors considering a position may wish to weigh the quality of the business carefully against the premium required to own it at today’s price.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 03-08-2026. Not investment advice.