
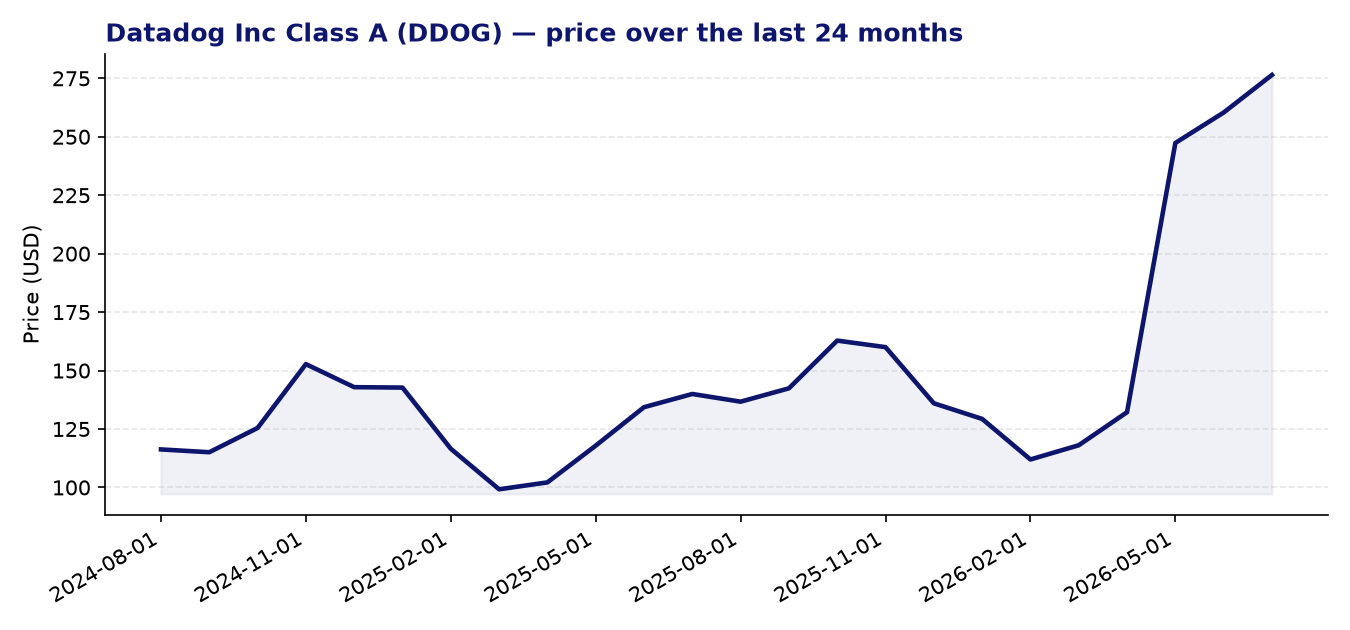
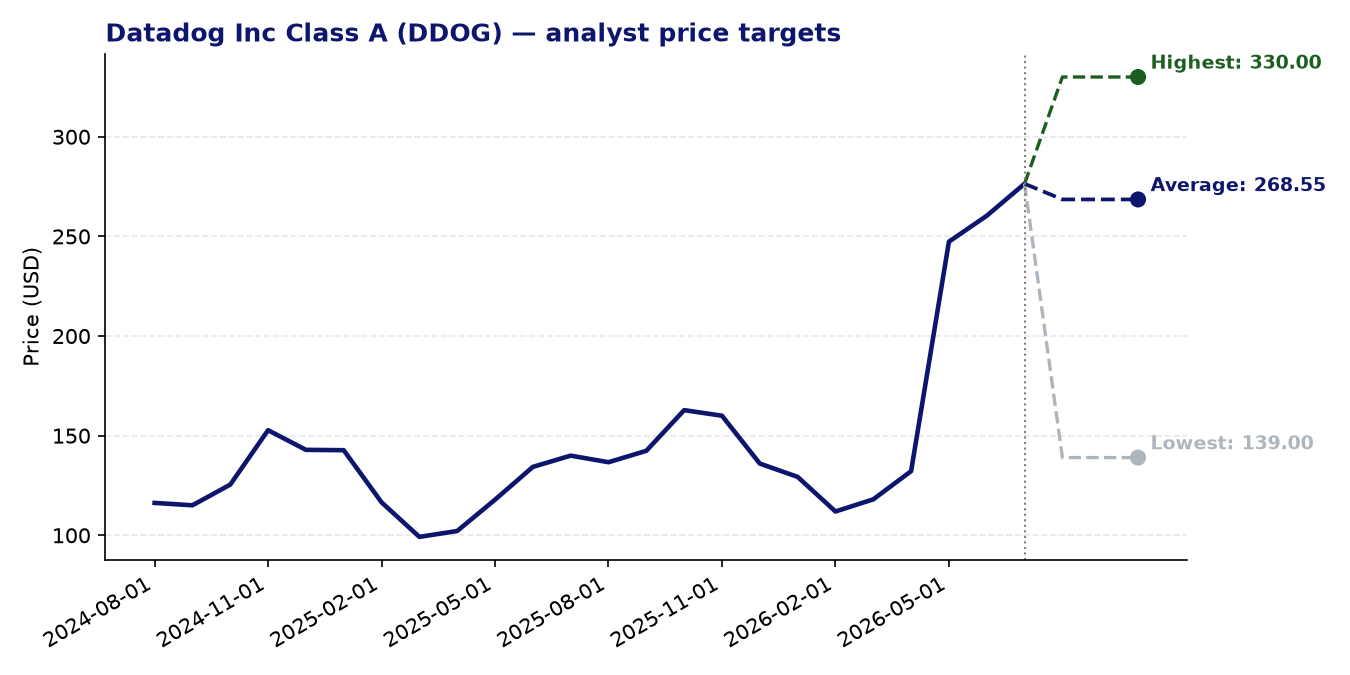
Datadog Inc Class A (DDOG) — current price: 276.44 USD | average price target: 268.55 USD | potential: -2.9%
About Datadog Inc Class A
- Datadog operates a cloud-based observability and security platform used by enterprises to monitor infrastructure, applications, logs, and networks across their technology stacks.
- The company offers a broad and expanding suite of products, including application performance monitoring, cloud security, LLM observability, and AI-driven site reliability engineering tools.
- Founded in 2010 and headquartered in New York, Datadog serves customers in the United States and internationally, with its platform increasingly positioned at the intersection of cloud operations and artificial intelligence.
- Its product portfolio spans dozens of modules — from database monitoring and CI visibility to sensitive data scanning — allowing customers to consolidate observability tooling under a single platform.
Recent news
- Datadog was upgraded to a Strong Buy rating by Zacks in early August 2026, driven by a meaningful upward revision trend in earnings estimates — a factor the firm views as a significant indicator of near-term price momentum.
- Bernstein SocGen raised its price target on Datadog substantially in early July 2026, lifting it to $226 from $180, reflecting greater confidence in the company’s growth prospects, even as the firm maintained a cautious overall stance.
- The stock has attracted elevated investor attention on financial research platforms in recent weeks, with analysts pointing to Datadog’s positioning as a key infrastructure play in the artificial intelligence era.
- Datadog reportedly delivered its strongest quarterly earnings performance in years during Q1 2026, providing a positive backdrop for the stock’s subsequent price appreciation.
Strengths
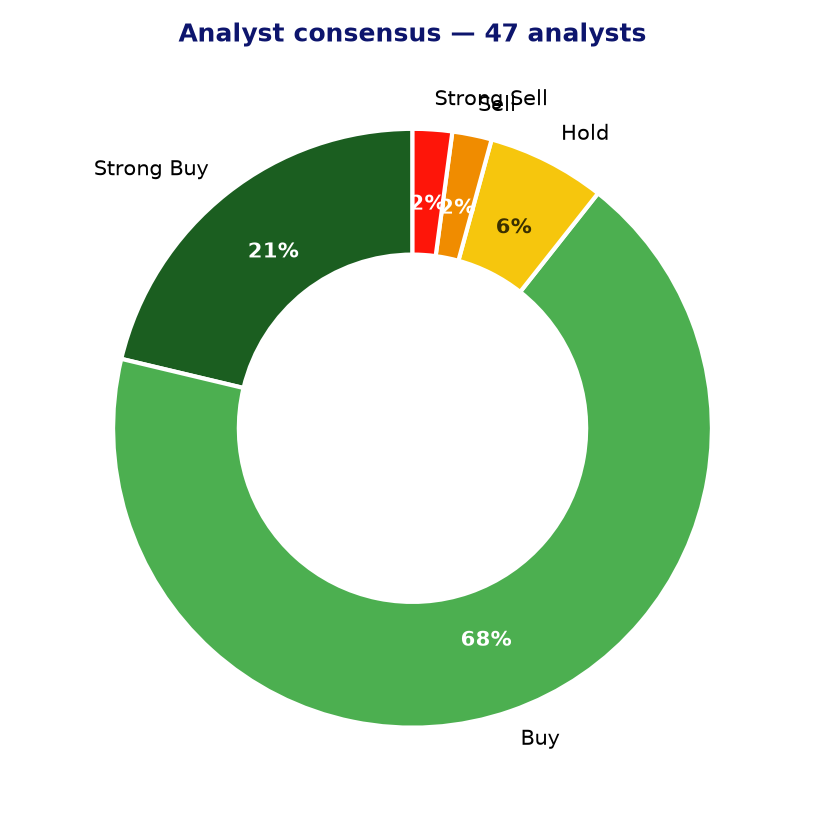
- Analyst sentiment is strongly supportive: of 47 analysts covering the stock, 42 carry either a buy or strong buy rating, suggesting broad conviction in the company’s growth trajectory.
- The 24-month Z-score momentum reading of 2.33 indicates that the stock has exhibited meaningful positive price momentum relative to its historical range, a signal that institutional interest has been sustained.
- Datadog’s PEG ratio of 1.65 offers some context to its elevated headline valuation — when growth expectations are factored in, the multiple appears less extreme than the trailing P/E alone would suggest.
- The company’s expanding product suite, particularly in LLM observability and AI-related monitoring, positions it well to benefit from enterprise adoption of generative AI infrastructure, where operational visibility is increasingly critical.
- The wide analyst price-target range (up to $330) reflects meaningful upside scenarios for investors with higher conviction in accelerating revenue growth or margin expansion.
Points of attention and risks
- The current share price of $276.44 sits approximately 2.9% above the average analyst price target of $268.55, meaning the stock has, on a consensus basis, already priced in near-term expectations — leaving limited near-term headroom on that measure.
- The trailing P/E of 691x is exceptionally high by any standard, and even the forward P/E of 96x demands a prolonged period of strong earnings delivery for the valuation to be considered reasonable.
- EPS growth of 1.13 (effectively flat to marginally positive on a trailing basis) underscores that the current valuation is built almost entirely on future growth expectations rather than current earnings power.
- The lowest analyst price target of $139 — roughly half the current price — serves as a reminder that a subset of informed observers sees material downside risk, particularly if growth rates disappoint or the macro environment tightens.
- As a high-multiple software stock, Datadog remains sensitive to changes in interest rate expectations, risk appetite, and shifts in enterprise IT spending — any softening in these areas could weigh disproportionately on the share price.
Analyst consensus and price targets
Conclusion
Datadog presents a compelling long-term growth case, underpinned by strong analyst support, sustained price momentum, and a product platform increasingly relevant to AI-era infrastructure needs. However, investors should weigh these positives carefully against a valuation that already exceeds the analyst consensus price target and rests on forward earnings multiples that leave little room for execution shortfalls. The stock suits investors with a high tolerance for valuation risk and a genuine long-term view on cloud and AI infrastructure spending; those focused on near-term value or downside protection may find the current entry point less attractive.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 31-07-2026. Not investment advice.