
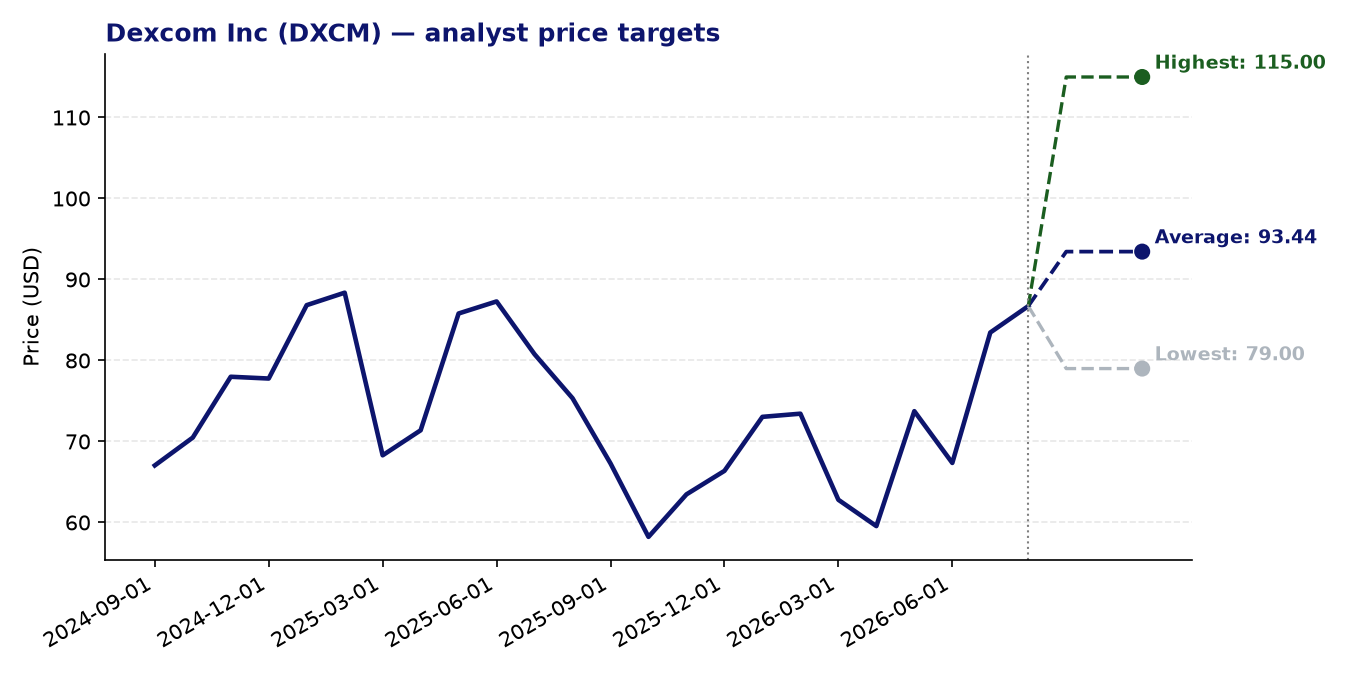
Dexcom Inc (DXCM) — current price: 86.71 USD | average price target: 93.44 USD | potential: +7.8%
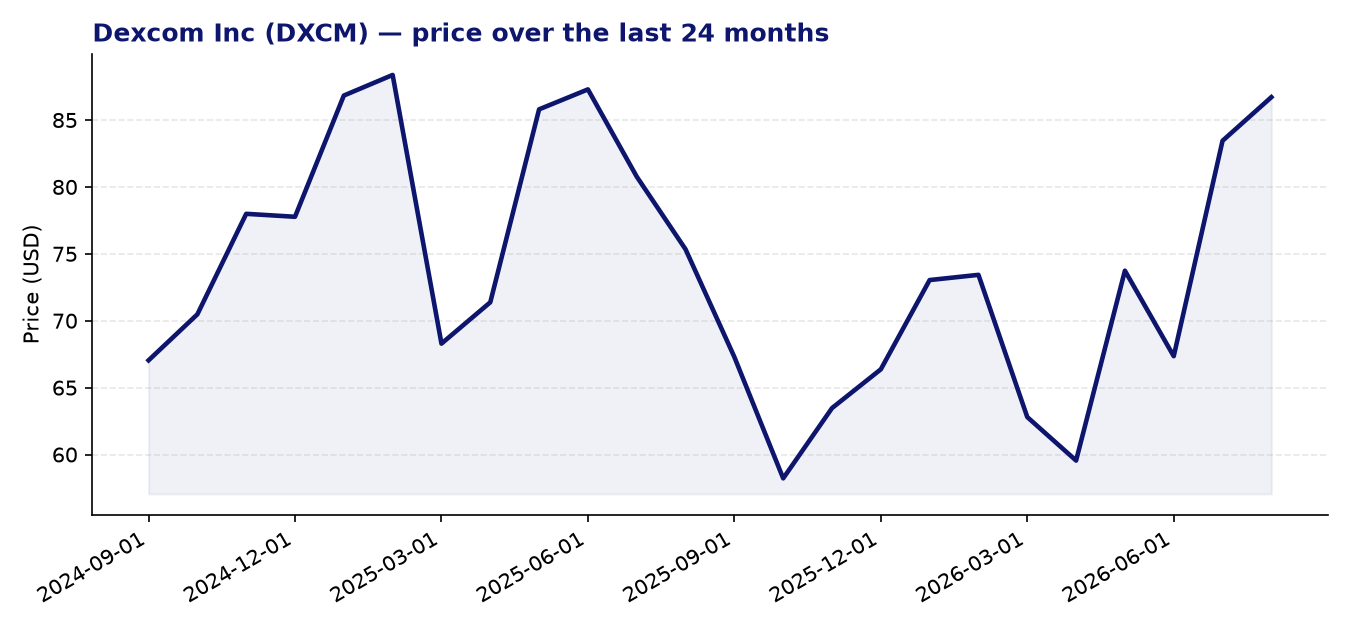
About Dexcom Inc
- DexCom is a San Diego-based medical device company founded in 1999, specialising in the design and commercialisation of continuous glucose monitoring (CGM) systems for diabetes management.
- Its core product lineup includes the Dexcom G7 and G7 15 Day, the Dexcom G6, and the Dexcom ONE+, which are aimed at insulin-dependent and non-insulin-dependent diabetes patients.
- The company recently launched Stelo, an over-the-counter biosensor targeting adults with prediabetes or Type 2 diabetes who do not use insulin, broadening its addressable market.
- DexCom sells its products through direct marketing to endocrinologists, physicians, and diabetes educators, and operates in both US and international markets.
Recent news
- DexCom reported second-quarter 2026 revenue of approximately $1.31 billion, representing year-on-year growth of 13.1% and coming in ahead of analyst estimates.
- Following a strong first quarter, commentary from analysts noted the company is well positioned to benefit from continued expansion of the CGM market across its product portfolio.
- DexCom has been cited as a notable performer within the medical devices sector in 2026, attracting attention from investors comparing it with sector peers.
- Analyst commentary from mid-2026 highlighted DexCom’s growth stock credentials, pointing to its consistent revenue trajectory and expanding product range.
Strengths
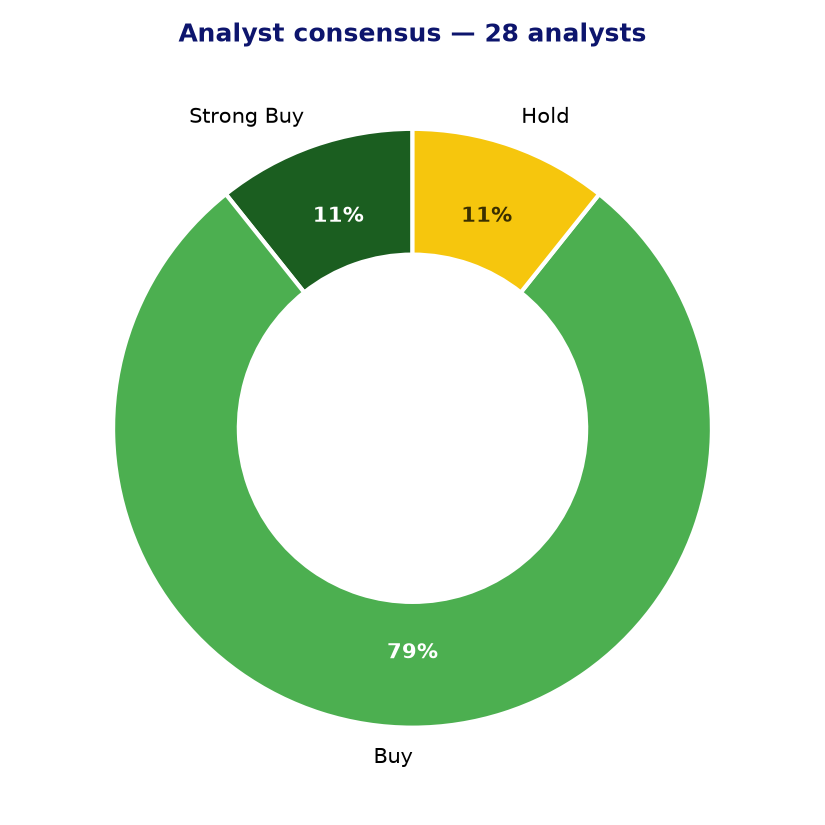
- The analyst community is broadly constructive, with 25 out of 28 covering analysts rating the stock buy or strong buy and an average price target of $93.44, implying approximately 7.8% upside from current levels.
- A 24-month Z-score momentum reading of 2.18 indicates that the stock has exhibited meaningful positive price momentum relative to its own history, which is supportive for trend-aware investors.
- Revenue growth of 13.1% year-on-year in Q2 2026 demonstrates that DexCom continues to expand at a meaningful pace in an increasingly competitive CGM market.
- The launch of Stelo addresses the large and underserved prediabetes and non-insulin Type 2 diabetes population, potentially extending DexCom’s market well beyond its traditional customer base.
- A forward P/E of 27.75 represents a meaningful discount to the trailing P/E of 34.27, suggesting analysts anticipate continued earnings growth that should gradually bring the valuation closer to market multiples.
Points of attention and risks
- At a trailing P/E of 34.27 and a PEG ratio of 1.6, the stock is not inexpensive; investors are paying a notable premium relative to earnings, which leaves limited margin for disappointment in results.
- EPS growth of 0.39 (as a ratio) indicates that while earnings are growing, the pace may not fully justify the current premium valuation if revenue growth were to moderate.
- The CGM market is becoming more competitive, with Abbott’s FreeStyle Libre platform and emerging players increasing pricing pressure, which could weigh on margins over time.
- The lowest analyst price target of $79.00 sits approximately 8.9% below the current price, a reminder that not all analysts are confident in near-term appreciation from current levels.
- DexCom operates in a sector sensitive to US healthcare policy and reimbursement decisions; any adverse changes to Medicare or private insurance coverage of CGM devices could materially affect demand.
Analyst consensus and price targets
Conclusion
DexCom presents a coherent growth story underpinned by strong analyst support, solid revenue momentum, and a product portfolio that is expanding into new patient segments such as prediabetes. However, the current valuation already prices in a degree of continued execution, and the competitive and reimbursement environment in CGM warrants close monitoring. Investors with a longer-term view on the structural growth of diabetes management technology may find the risk-reward balance reasonable, though the modest consensus price target upside suggests the near-term bar is relatively high.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 10-08-2026. Not investment advice.