
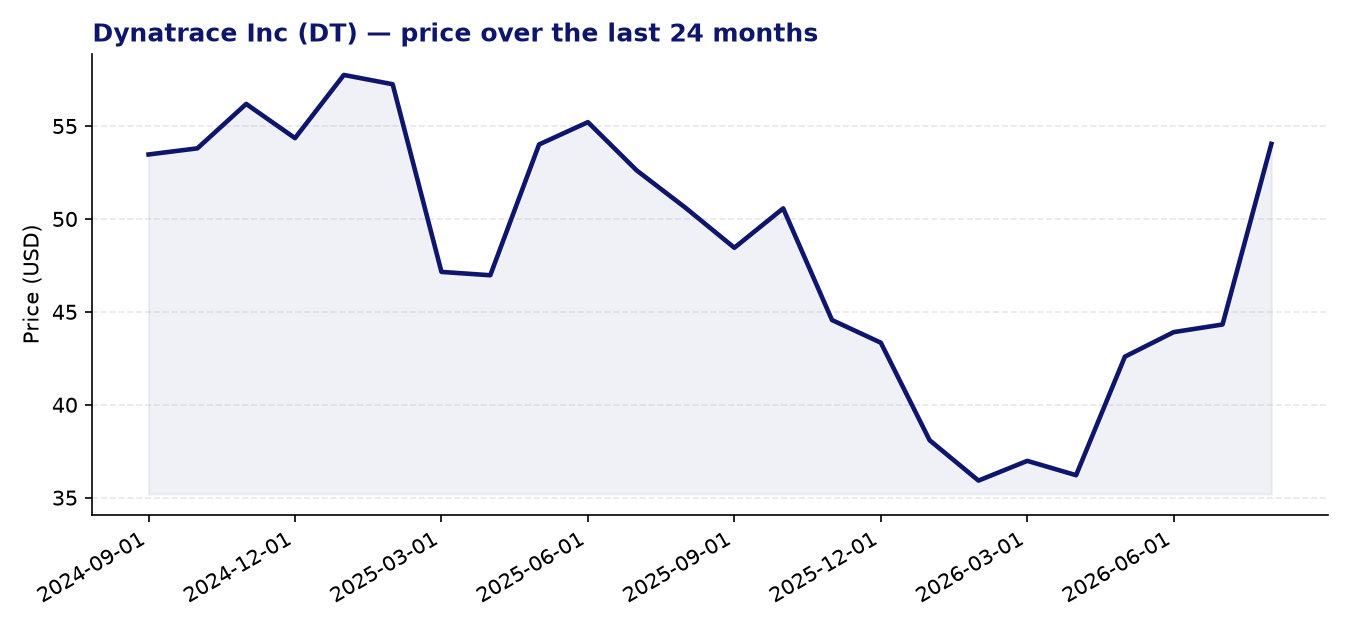
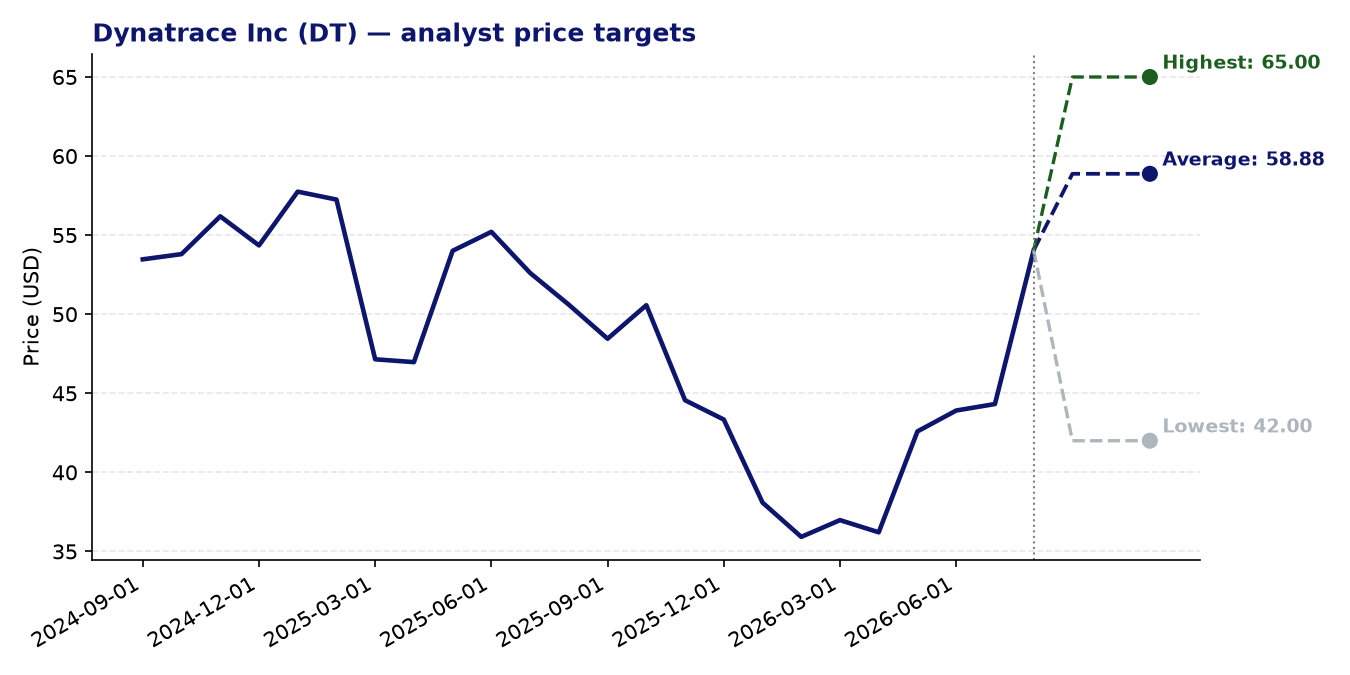
Dynatrace Inc (DT) — current price: 54.06 USD | average price target: 58.88 USD | potential: +8.9%
About Dynatrace Inc
- Dynatrace operates an AI-powered observability platform that helps enterprises monitor and manage the complexity of modern digital environments, covering infrastructure, applications, security, and business analytics.
- The company serves customers across banking, financial services, government, insurance, retail, transportation, and software industries in North America, Europe, the Middle East, Africa, Asia Pacific, and Latin America.
- Its go-to-market strategy combines a direct global sales force with a broad partner network that includes global system integrators, cloud providers, resellers, and technology alliance partners.
- Founded in 2005 and headquartered in Boston, Massachusetts, Dynatrace also provides implementation, consulting, and training services alongside its software platform.
Recent news
- Morgan Stanley upgraded Dynatrace to Overweight in late August, raising its price target to $65, citing expectations of sustained revenue growth of 20% or more alongside meaningful margin expansion over the next two years.
- In its fiscal Q1 2027 earnings call (August 5), Dynatrace issued Q2 2027 guidance for earnings per share of $0.48–$0.49, ahead of the then-prevailing consensus estimate of $0.44, while guiding revenue to $565–$570 million.
- Dynatrace published its ‘State of SRE and Platform Engineering 2026’ study, examining how large enterprises are incorporating AI into site reliability and platform engineering, reinforcing the company’s positioning at the intersection of AI adoption and enterprise observability.
- Zacks highlighted Dynatrace as a top momentum stock for long-term investors, reflecting positive sentiment around its growth trajectory and platform relevance.
Strengths
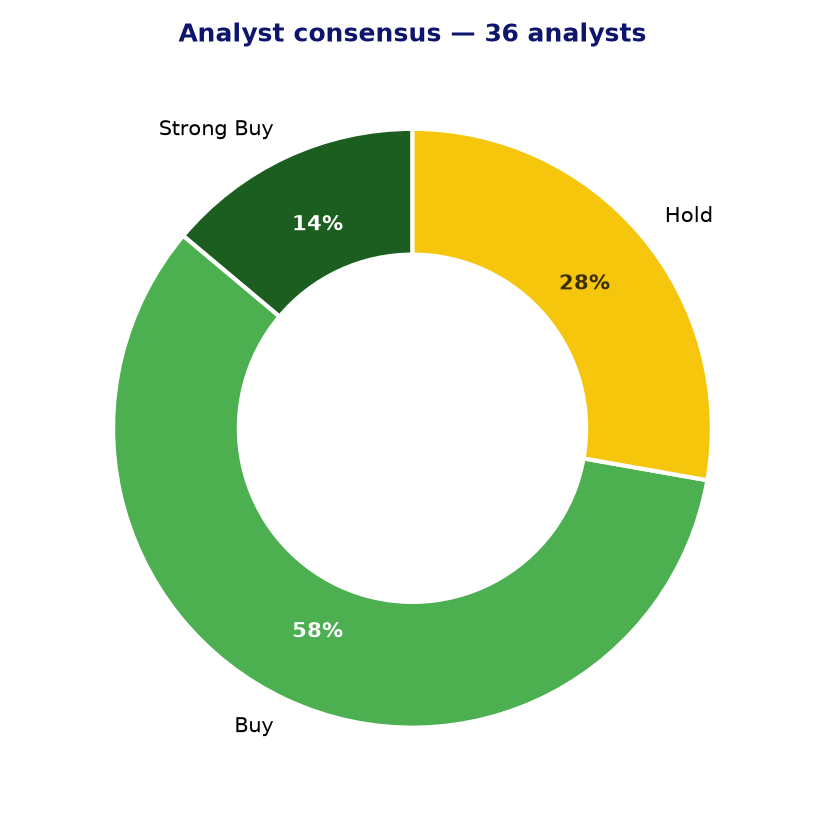
- Analyst sentiment is broadly constructive: 26 of 36 covering analysts rate the stock Buy or Strong Buy, with no Sell ratings, and an average price target of $58.88 implying roughly 9% upside from the current price.
- Morgan Stanley’s upgrade to Overweight, with a $65 price target, provides a meaningful near-term catalyst and reflects confidence in Dynatrace’s ability to capture demand as enterprises scale AI-driven workloads.
- The 24-month Z-score momentum reading of 2.33 indicates the stock has shown sustained relative price strength, a factor that has historically been associated with continued outperformance.
- The forward P/E of 23.5x is considerably more modest than the trailing figure, suggesting the market is already pricing in significant earnings growth ahead; a PEG ratio of 1.02 implies the valuation is broadly in line with that expected growth.
- Dynatrace’s platform spans observability, security, and AI analytics, positioning it well to benefit from enterprise spending on AI infrastructure management — a theme that is gaining momentum across large organisations.
Points of attention and risks
- The trailing P/E of 108x is elevated, even for a high-growth software company, and leaves limited room for disappointment in execution or guidance.
- EPS growth of -0.24 on a trailing basis is a point of concern, indicating that profitability has not yet kept pace with revenue expansion; investors will want to see this improve materially.
- The wide spread between the lowest and highest analyst price targets ($42 to $65) signals meaningful disagreement among analysts about the company’s fair value and near-term prospects.
- The observability and application performance management market is competitive, with well-resourced rivals such as Datadog, New Relic, and cloud-native offerings from major hyperscalers posing ongoing pricing and feature pressure.
- At 9% implied upside to the average price target, the risk-reward from current levels is not especially wide, meaning the stock may need to consistently beat guidance to drive further re-rating.
Analyst consensus and price targets
Conclusion
Dynatrace occupies a credible position in the growing enterprise observability market, and the combination of a Morgan Stanley upgrade, above-consensus guidance, and strong momentum indicators makes the investment case reasonably compelling. However, the elevated trailing valuation, negative trailing EPS growth, and a relatively modest implied upside to consensus price targets suggest the stock is pricing in a good deal of the expected progress already. Investors with a longer time horizon and conviction in AI-led enterprise IT spending may find the story attractive, but the near-term margin of safety is limited and execution will need to be consistent.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 27-08-2026. Not investment advice.