
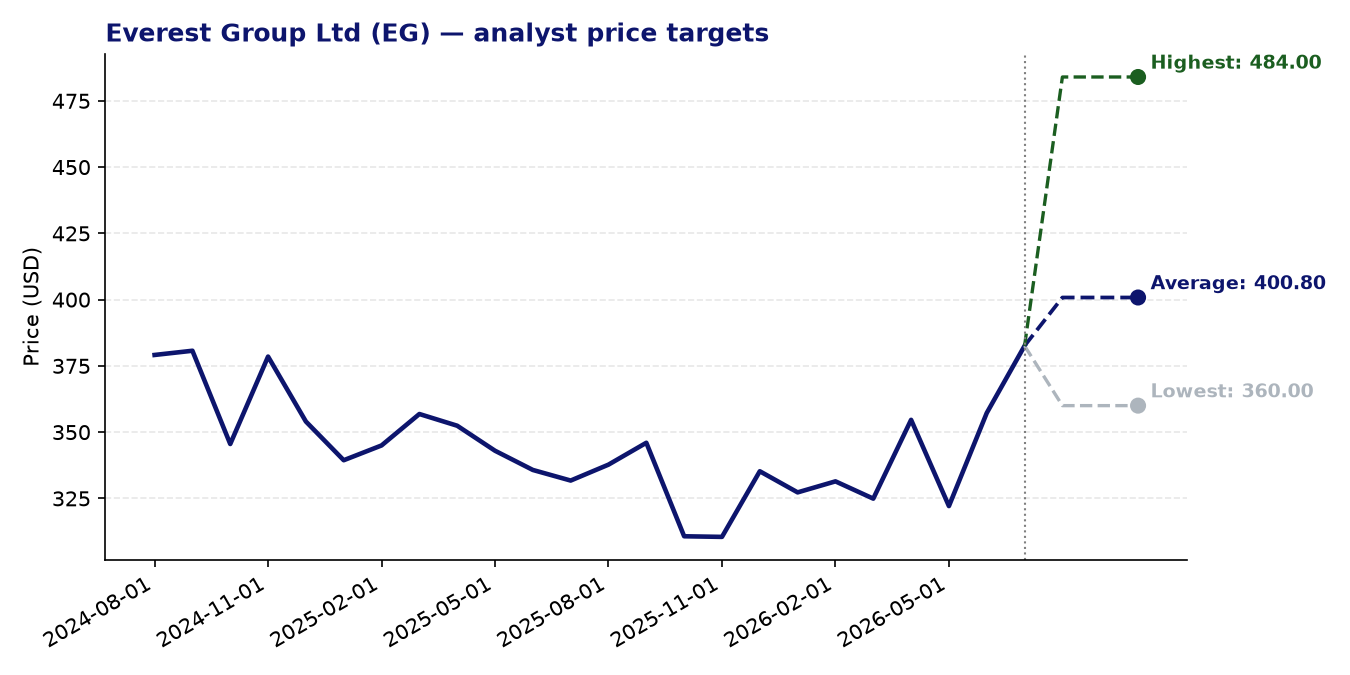
Everest Group Ltd (EG) — current price: 382.57 USD | average price target: 400.80 USD | potential: +4.8%
About Everest Group Ltd
- Everest Group, Ltd. is a Bermuda-headquartered specialty insurer and reinsurer with operations spanning the United States, Europe, and international markets.
- The company operates through two core segments — Insurance and Reinsurance — writing property and casualty products across both divisions.
- Its reinsurance portfolio covers a broad range of lines including catastrophe, marine, aviation, mortgage, agriculture, and political violence risks, distributed through brokers and directly with ceding companies.
- The Insurance segment offers commercial property and casualty products via wholesale and retail brokers, surplus lines brokers, and programme administrators.
- Founded in 1973 and formerly known as Everest Re Group, the company rebranded to Everest Group, Ltd. in July 2023, reflecting its broader insurance footprint.
Recent news
- Analysts are preparing for Everest Group’s next quarterly earnings release, with the market watching closely given the company’s $14.7 billion market capitalisation and its exposure to property and casualty lines.
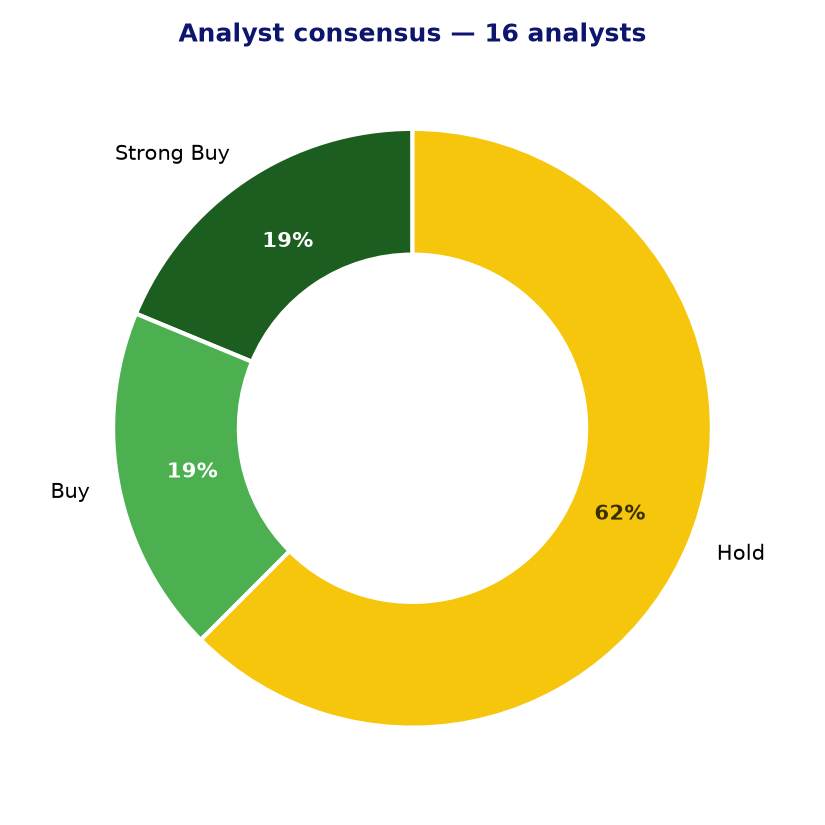
- A mid-2026 overview of Wall Street sentiment found that analyst opinion on the stock remains broadly constructive, with the majority of coverage sitting at hold or better across 16 analysts tracked.
Strengths
- The analyst consensus is notably free of sell-side negativity: of 16 analysts covering the stock, six hold outright buy or strong buy ratings, and none carry a sell recommendation.
- The average price target of $400.80 implies approximately 4.8% upside from current levels, with the highest target of $484.00 suggesting meaningful room for rerating in a more optimistic scenario.
- Valuation metrics look attractive for the sector: a trailing P/E of just 7.79 and a forward P/E of 6.33 suggest the market is pricing in limited earnings growth, while the PEG ratio of 0.97 indicates the stock is broadly in line with its growth rate.
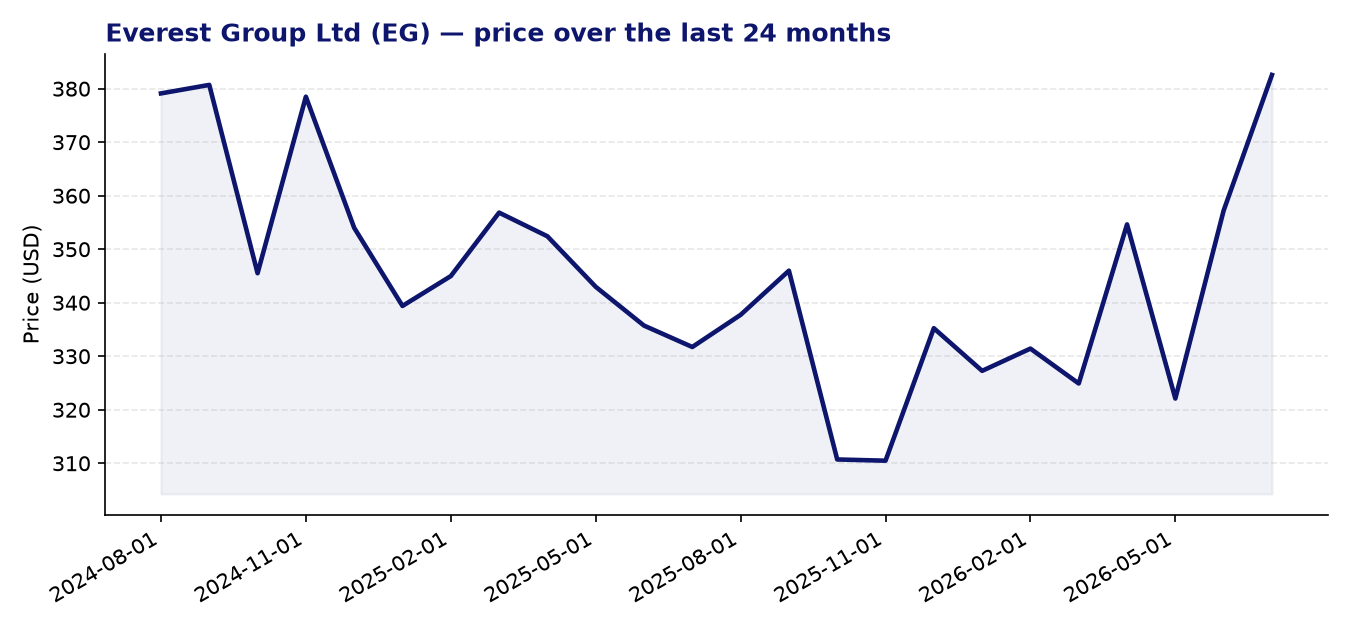
- A 24-month Z-score momentum reading of 2.81 points to sustained positive price momentum relative to its historical range, which may reflect improving underwriting conditions or investor re-engagement with the name.
- The reinsurance market continues to benefit from a hardening rate environment in several key lines, which should support premium growth and underwriting margins across Everest’s diversified book.
Points of attention and risks
- Despite favourable momentum, the consensus is dominated by hold ratings (10 of 16 analysts), suggesting that many professionals see limited near-term catalysts or consider the risk-reward fairly balanced at current prices.
- EPS growth of 2.11 is modest, and while the low PEG ratio flatters the valuation, it also reflects that earnings expansion is not expected to be particularly dynamic in the near term.
- As a significant writer of catastrophe reinsurance, Everest Group carries material exposure to large natural catastrophe events, which can cause sharp, unpredictable earnings volatility in any given quarter or year.
- The wide spread between the lowest ($360) and highest ($484) price targets reflects genuine uncertainty among analysts about the company’s forward earnings trajectory and loss reserve adequacy.
- Concentration in the reinsurance sector means the company is sensitive to shifts in the reinsurance cycle; any softening of rates or an above-average loss year could weigh on both earnings and sentiment.
Analyst consensus and price targets
Conclusion
Everest Group presents a coherent investment case built on an undemanding valuation, solid momentum, and a diversified book of reinsurance and insurance business in a broadly supportive pricing environment. However, the preponderance of hold ratings and modest near-term earnings growth expectations suggest analysts view the stock as fairly priced rather than deeply discounted. Investors with an interest in the specialty insurance and reinsurance space may find the low forward P/E and clean balance sheet worth monitoring, while remaining attentive to the inherent volatility that catastrophe exposure can introduce to quarterly results.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 17-07-2026. Not investment advice.