
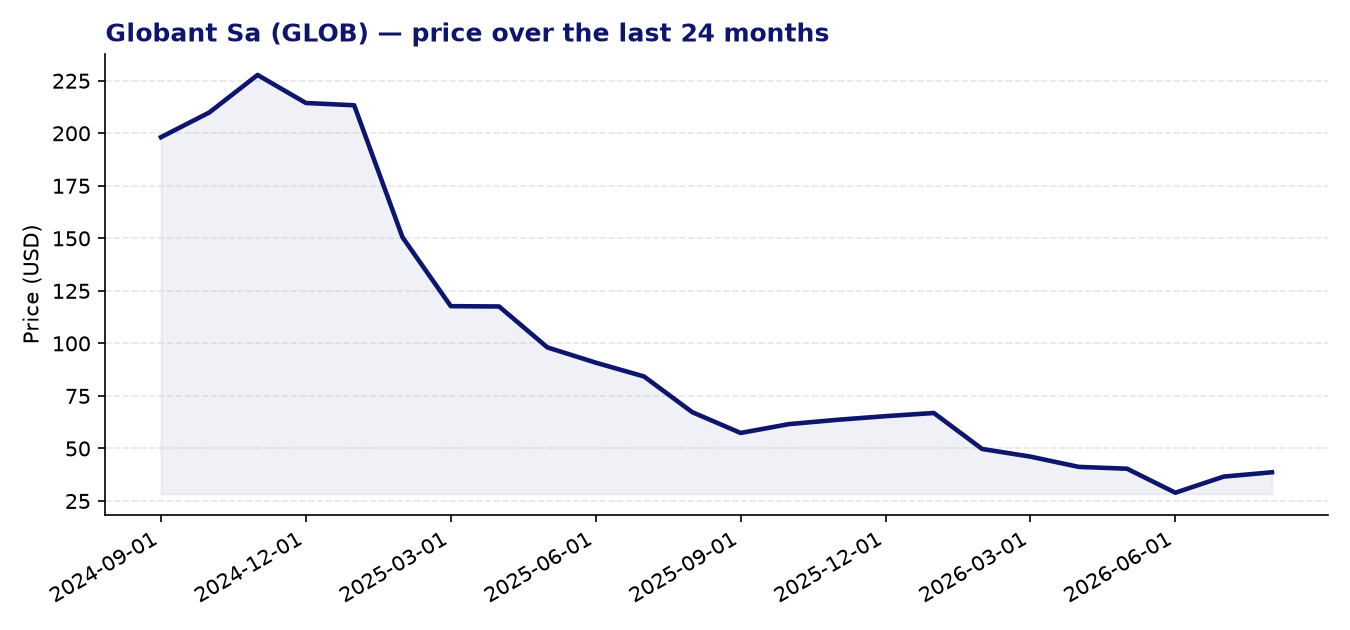
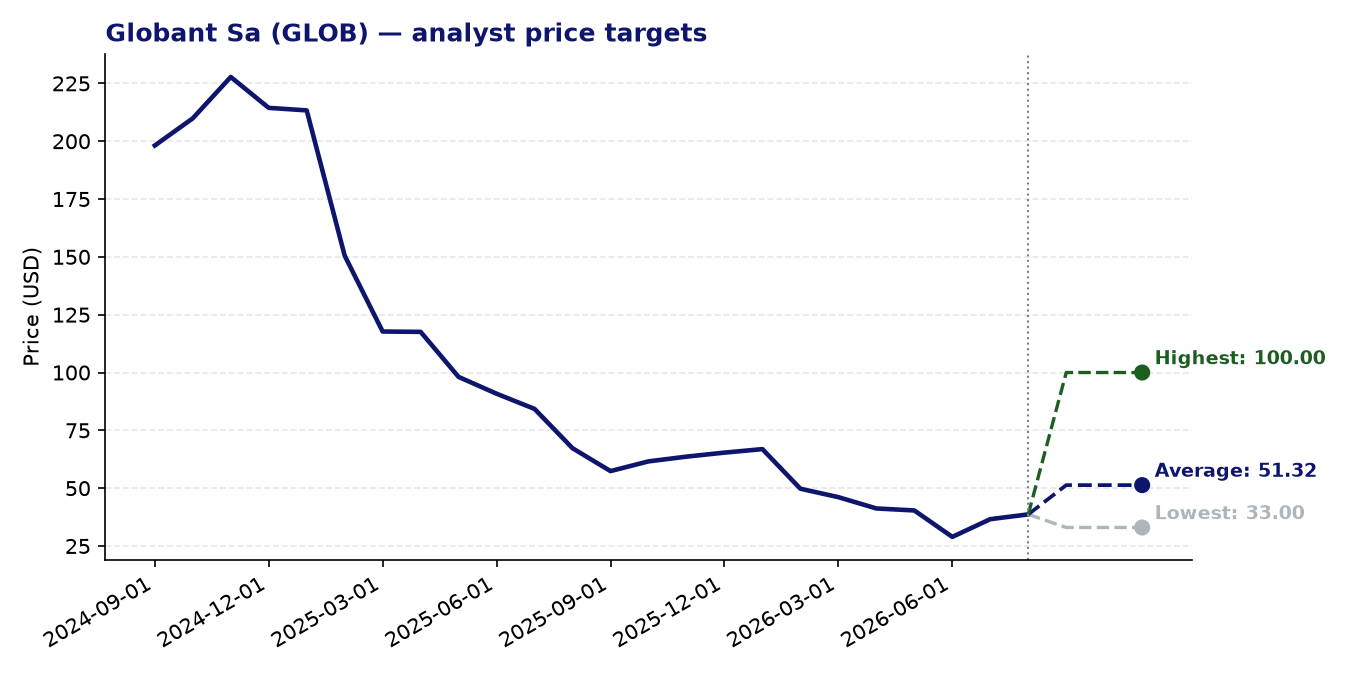
Globant Sa (GLOB) — current price: 38.66 USD | average price target: 51.32 USD | potential: +32.7%
About Globant Sa
- Globant is a Luxembourg-headquartered technology services company founded in 2003, operating across the United States, Latin America, Europe, and other international markets.
- The company delivers AI-integrated software development, digital transformation, and enterprise technology services through a range of specialised studios and platforms.
- Its proprietary AI ecosystem includes Globant Enterprise AI, AI Pods (a subscription-based delivery model), and dedicated hubs for model governance, agentic workflows, and corporate intelligence.
- Globant serves a broad array of sectors including financial services, healthcare, media and entertainment, gaming, airlines, and energy through tailored AI Industry Studios.
- The company also maintains strategic partnerships in areas such as AI-driven cancer drug discovery and assistive technology for students with disabilities.
Recent news
- Wells Fargo analyst Jason Kupferberg reiterated a Hold rating on Globant in mid-June 2026, setting a price target of $50, well above the share price at the time.
- Multiple analyst commentary pieces from mid-2026 onwards have placed Globant in the neutral camp, with several firms neither bullish nor bearish — reflecting broader uncertainty about the AI disruption thesis for IT services companies.
- A Seeking Alpha analysis argued that the market may be overstating existential risks from generative AI, pointing to modest but positive revenue growth of 1.6% and a valuation of roughly five times earnings as potentially attractive.
- A Yahoo Finance piece flagged that excessive negative extrapolation may have weighed on the share price, suggesting the market’s reaction could have outpaced the underlying fundamental deterioration.
Strengths
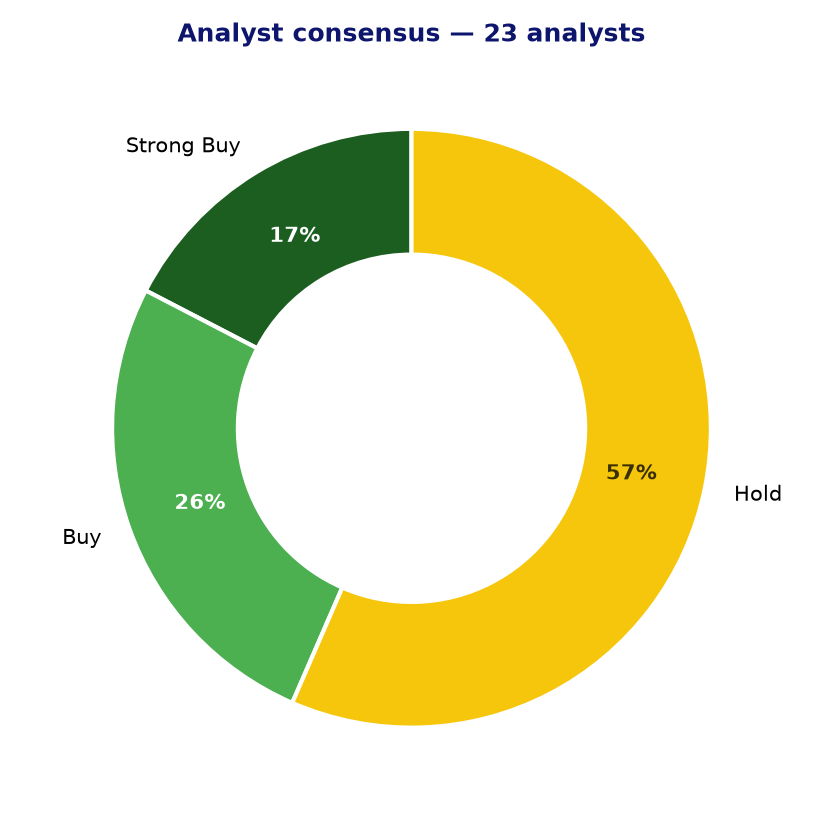
- The average analyst price target of $51.32 implies approximately 32.7% upside from the current price of $38.66, and the consensus of 23 analysts skews constructive with 10 buy or strong buy ratings and no sell recommendations.
- A 24-month Z-score momentum reading of 2.11 indicates that the stock has shown meaningful relative price strength, a positive technical signal for medium-term trend followers.
- The forward P/E of 6.17 is strikingly low for a technology services company, suggesting the market may be pricing in a more severe earnings deterioration than current fundamentals support.
- Globant’s expanding AI product suite — including agentic platforms, subscription-based AI Pods, and sector-specific studios — positions it to participate in enterprise AI adoption rather than simply being displaced by it.
- A PEG ratio of 1.05 is close to fair value on a growth-adjusted basis, indicating that if earnings expectations prove achievable, the shares do not appear significantly overvalued.
Points of attention and risks
- The trailing P/E of 15.1 versus a forward P/E of 6.17 implies a very sharp expected jump in earnings, which may reflect analyst optimism that is not yet supported by reported results — EPS growth figures are currently listed as unavailable.
- Revenue growth of only 1.6% last year is modest for a company in the technology services sector, raising questions about demand momentum and competitive positioning.
- Generative AI poses a structural risk to traditional IT outsourcing and software development services; Globant’s core business model could face pricing pressure or volume erosion if clients bring more development in-house using AI tools.
- Analyst sentiment is predominantly neutral — 13 of 23 analysts rate the stock Hold — suggesting limited near-term conviction among those who cover the company most closely.
- The wide spread between the lowest ($33) and highest ($100) price targets among analysts highlights significant disagreement about the company’s prospects, reflecting genuine uncertainty rather than a clear investment case.
Analyst consensus and price targets
Conclusion
Globant presents an interesting but genuinely uncertain picture: its valuation metrics, particularly the forward P/E and average price target upside, look superficially attractive, and the company is actively repositioning around AI rather than ignoring the shift. However, tepid revenue growth, a predominantly neutral analyst consensus, and real structural questions about the long-term demand for traditional IT services mean there are meaningful risks that the low valuation is reflecting, not merely mispricing. Investors with a higher tolerance for sector-level uncertainty may find the risk-reward worth monitoring closely, while those seeking near-term earnings clarity may prefer to wait for stronger evidence of a fundamental reacceleration.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 20-08-2026. Not investment advice.