
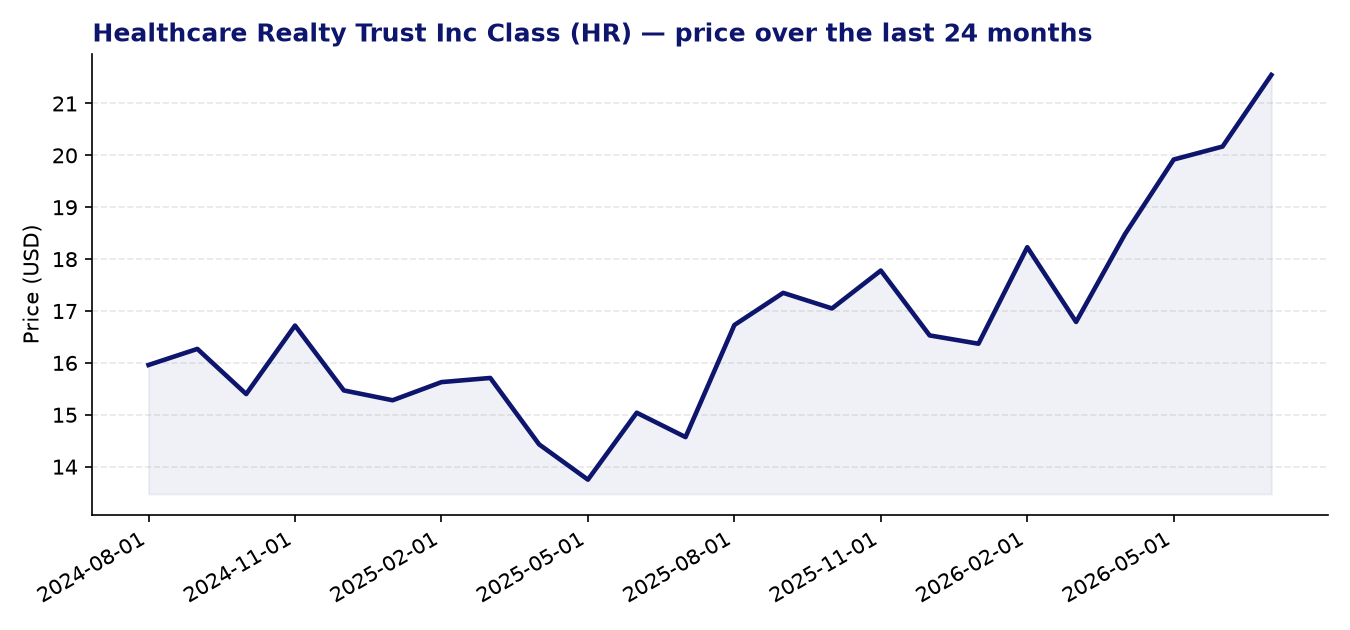
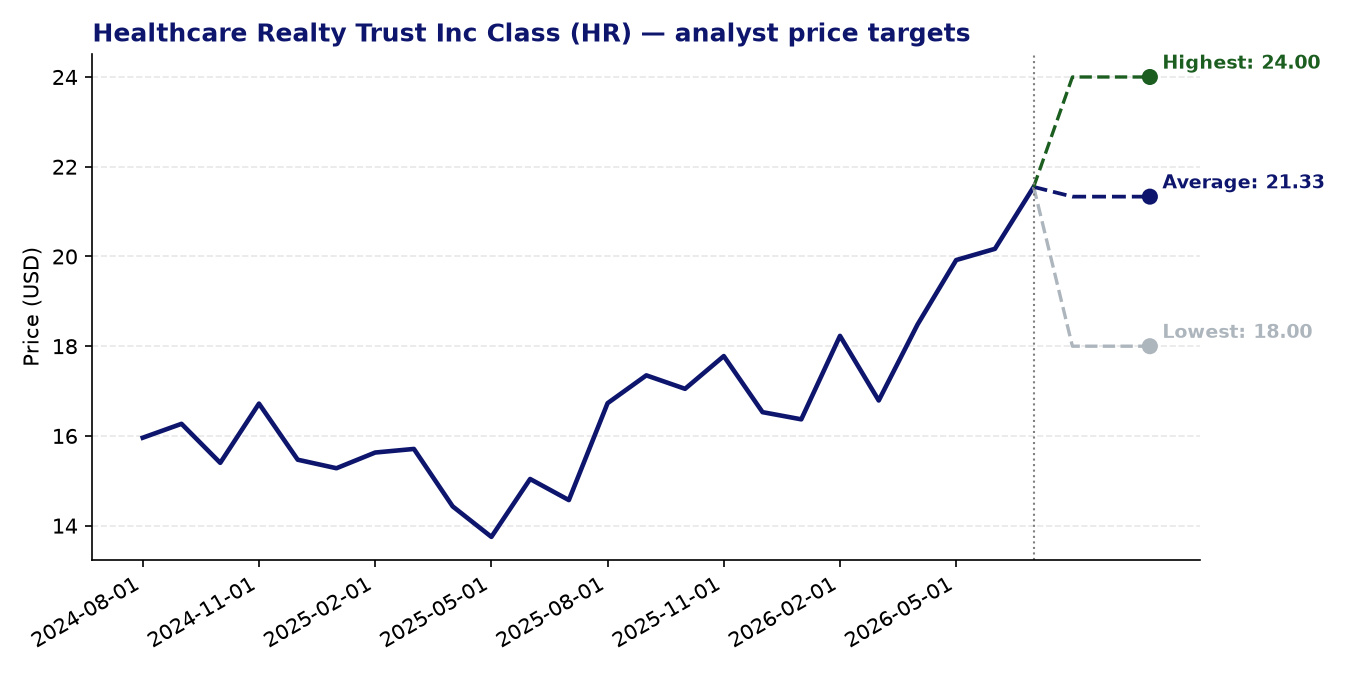
Healthcare Realty Trust Inc Class (HR) — current price: 21.55 USD | average price target: 21.33 USD | potential: -1.0%
About Healthcare Realty Trust Inc Class
- Healthcare Realty Trust (HR) is a Nashville-based REIT specialising in medical outpatient buildings, predominantly situated on or near major hospital campuses across the United States.
- As of late 2025, the company’s portfolio comprised 579 properties across 28 states, totalling approximately 33.6 million square feet of space.
- The trust pursues portfolio growth through selective property acquisitions and development activity.
- With an enterprise value of roughly $11.1 billion, HR positions itself as one of the largest dedicated owners and operators of medical outpatient real estate in the country.
- The company was incorporated in 1992 and has operated as a publicly listed REIT throughout its history.
Recent news
- Healthcare Realty published its full-year 2025 results in February 2026, presenting the company as the only pure-play medical outpatient building REIT, and outlined its strategic priorities for the year ahead.
- Fourth-quarter 2025 results showed same-store cash net operating income growth of 5.5%, with management emphasising continued operational transformation and solid tenant retention.
- First-quarter 2026 results, released at the end of April, came in at normalised funds from operations of $0.41 per diluted share, with management characterising performance as robust.
- In May 2026, the company announced plans for a $500 million private offering of exchangeable notes through its operating partnership, a move that will affect the balance sheet and warrants monitoring by investors.
Strengths
- Operational momentum appears solid: same-store cash NOI grew 5.5% in Q4 2025, reflecting healthy underlying demand for medical outpatient space and disciplined property management.
- The 24-month Z-score momentum reading of 2.35 indicates that the share price has shown meaningful positive momentum relative to its historical trend, which may reflect growing market recognition of the company’s repositioning.
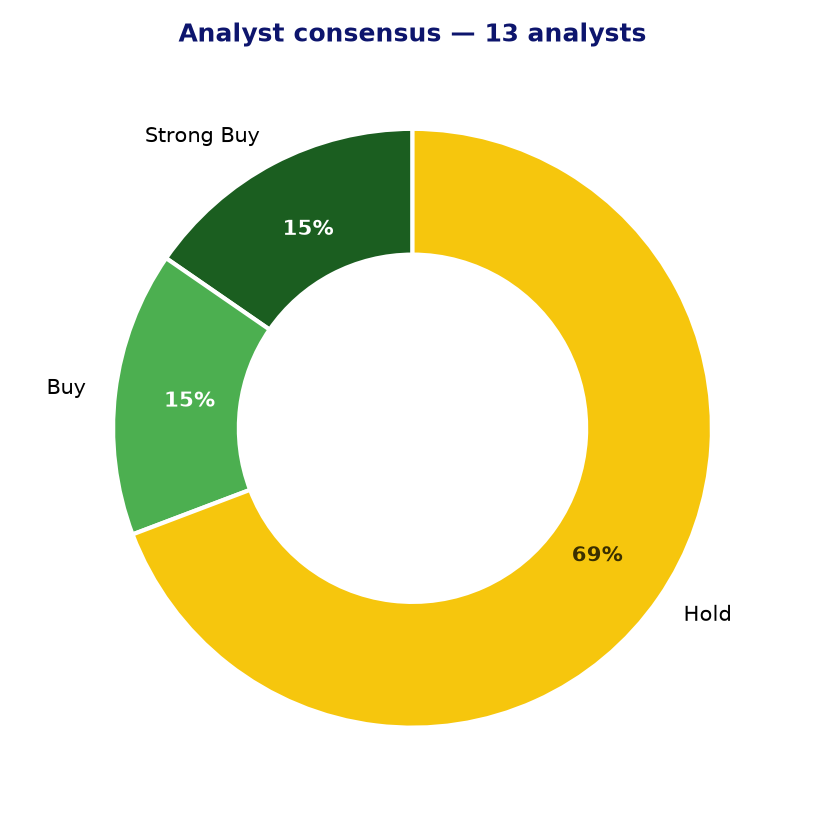
- Of 13 covering analysts, four rate the stock as a buy or strong buy, and none carry a sell recommendation, suggesting a broadly constructive, if cautious, professional view on the company’s prospects.
- HR’s focused positioning as the only large-scale pure-play medical outpatient REIT provides a differentiated niche, with structural tailwinds from an ageing US population and the continued shift of healthcare delivery away from acute-care hospital settings.
- A portfolio of 579 properties across 28 states provides meaningful geographic diversification and reduces concentration risk at the individual market level.
Points of attention and risks
- The average analyst price target of $21.33 sits marginally below the current share price of $21.55, implying virtually no consensus upside at present levels and a relatively tight margin of safety.
- Valuation metrics are difficult to interpret favourably: the forward P/E of over 1,000x and a PEG ratio of 8.82 reflect the challenges REITs face on earnings-based measures, but also signal that meaningful profitability on a conventional basis remains elusive.
- The planned $500 million exchangeable notes offering will add to the company’s debt load, and investors should assess the impact on leverage ratios and future financial flexibility, particularly in a still-elevated interest rate environment.
- Nine of the 13 covering analysts hold a neutral stance, suggesting the market broadly views the risk-reward as balanced rather than compellingly attractive at the current price.
- As a REIT, HR is inherently sensitive to interest rate movements; any sustained period of higher borrowing costs could increase refinancing expenses and pressure distributable income over time.
Analyst consensus and price targets
Conclusion
Healthcare Realty Trust presents a clear and focused proposition within the healthcare real estate sector, with encouraging operational metrics and a structural tailwind from shifting healthcare delivery patterns. However, the stock is trading broadly in line with the analyst consensus target, leaving limited headroom for valuation expansion, while the pending debt issuance and persistently complex earnings picture add layers of caution. Investors considering HR will likely weigh the quality and stability of its medical outpatient portfolio against the current absence of meaningful analyst-implied upside and the sensitivities that come with a leveraged, interest-rate-exposed balance sheet.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 27-07-2026. Not investment advice.