
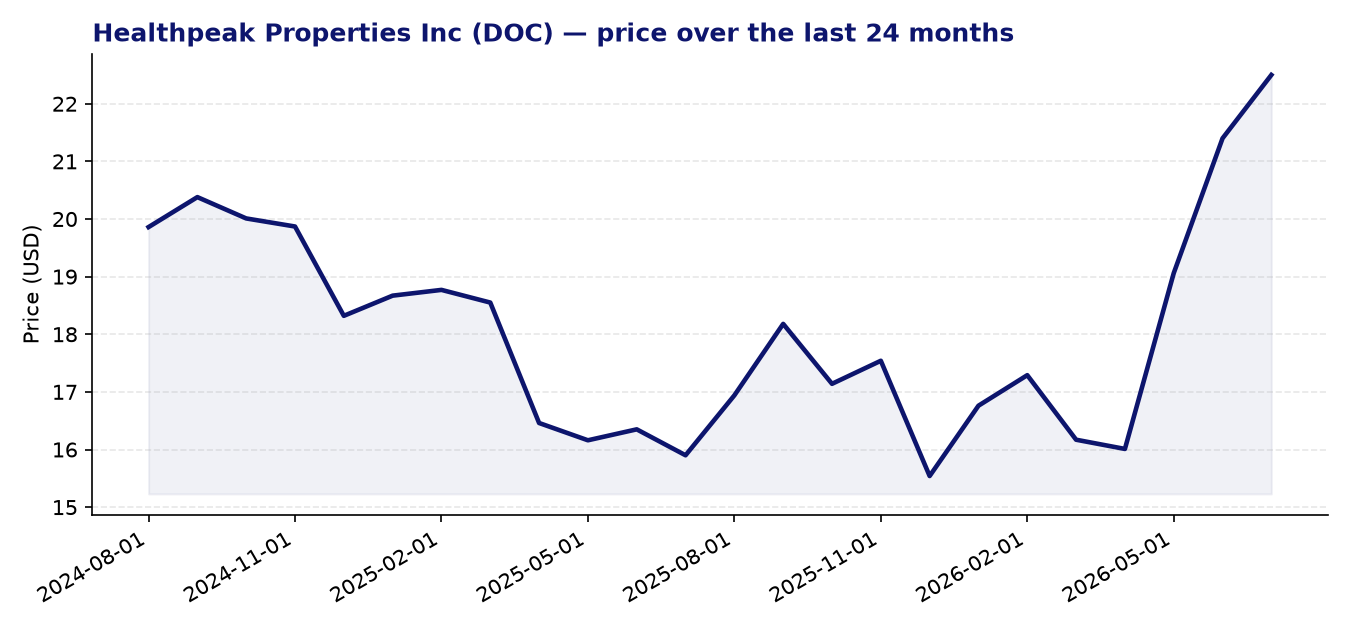
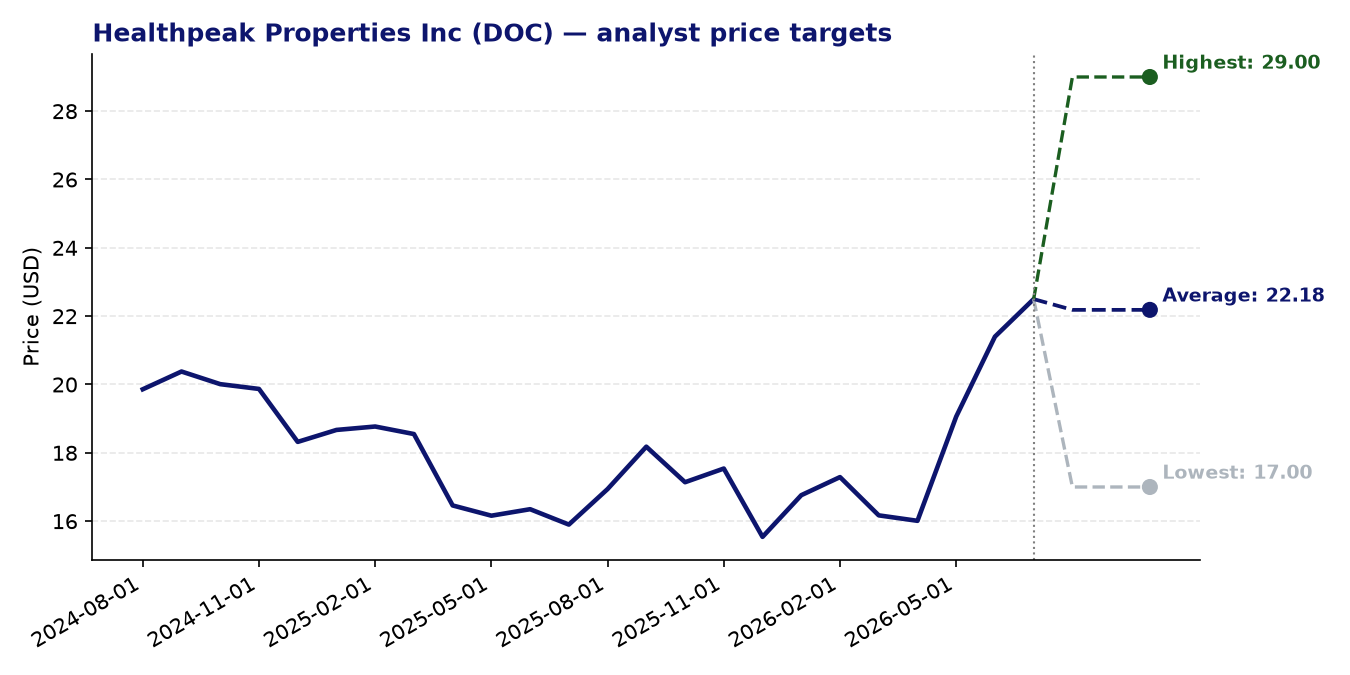
Healthpeak Properties Inc (DOC) — current price: 22.50 USD | average price target: 22.18 USD | potential: -1.4%
About Healthpeak Properties Inc
- Healthpeak Properties (NYSE: DOC) is an S&P 500 REIT focused on owning, operating, and developing healthcare real estate across the United States, with roots going back to its 1985 founding.
- The company’s portfolio is organised around three core asset classes: outpatient medical buildings, laboratory facilities, and continuing care retirement communities (CCRCs).
- As of September 30, 2025, Healthpeak held interests in 703 properties, with outpatient medical (530 properties) forming the dominant segment, followed by lab (139) and CCRC (15).
- The REIT is structured as an umbrella partnership REIT (UPREIT), self-administered, and headquartered in Denver, Colorado, with offices across several US states.
Recent news
- Healthpeak has announced the schedule for its second quarter 2026 earnings release and accompanying conference call, giving investors a near-term catalyst to watch.
- The stock posted a notable single-day gain of around 2% in late June 2026, outperforming peers on a broadly mixed market day.
- Over the three months to late June 2026, Healthpeak shares have appreciated approximately 28%, prompting questions about whether the recent momentum is sustainable.
- A commentary published on Seeking Alpha characterised DOC as a potentially undervalued REIT with a dividend yield of around 6%, framing it as a value opportunity within the healthcare real estate sector.
Strengths
- The 24-month Z-score momentum reading of 2.55 indicates that price momentum has been meaningfully positive, consistent with the reported ~28% gain over the past three months.
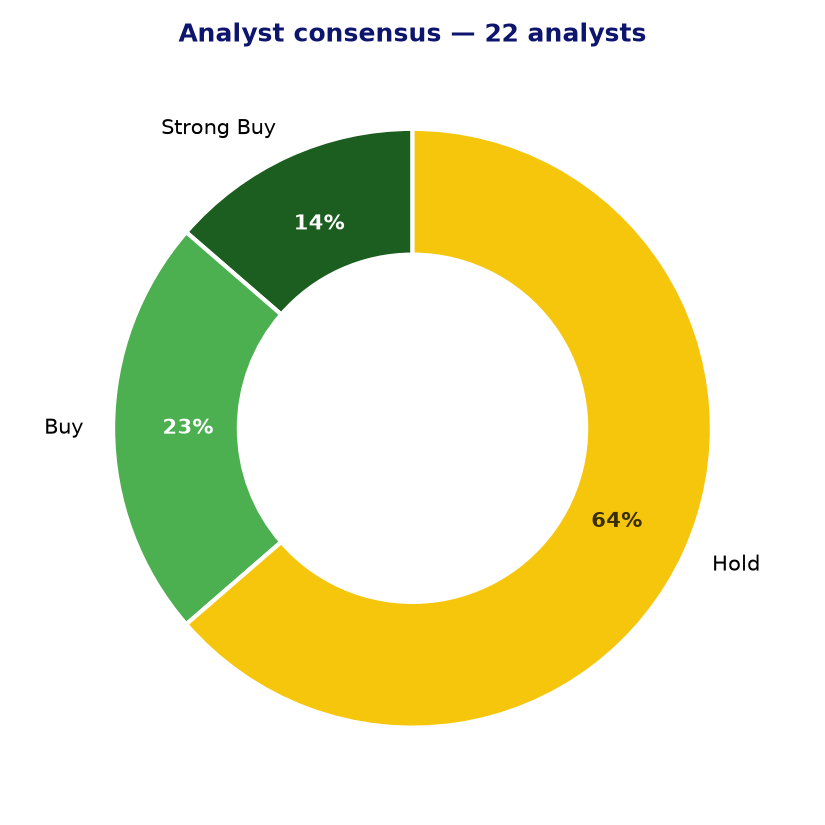
- Analyst sentiment skews constructive: of 22 covering analysts, 8 carry buy or strong buy ratings and 14 are at hold, with zero sell recommendations on record.
- A dividend yield of approximately 6% provides a meaningful income component for investors in the current rate environment, particularly relevant for REIT-focused portfolios.
- The diversified portfolio of 703 properties across outpatient medical, lab, and CCRC segments provides broad exposure to structural healthcare demand trends, reducing reliance on any single sub-sector.
- The wide analyst price-target range (USD 17–29) includes a high-end target of USD 29, suggesting some analysts see material upside from current levels if operational execution improves.
Points of attention and risks
- At the current price of USD 22.50, the stock is trading marginally above the analyst consensus price target of USD 22.18, implying an average downside of approximately 1.4% on a 12-month view — a narrow margin of safety.
- The trailing P/E of 70.3x is elevated for a REIT, and the PEG ratio of 4.32 suggests the market is pricing in significant growth that may be difficult to deliver, while the negative forward P/E adds further uncertainty around near-term earnings visibility.
- EPS growth of 3.52% is modest, and the disconnect between headline earnings metrics and cash-flow-based REIT measures (such as FFO) warrants careful scrutiny before drawing valuation conclusions.
- The lab real estate segment faces ongoing pressure as biotech and life-sciences tenants have rationalised space needs in recent years, which could weigh on occupancy and rental rates within that sub-portfolio.
- A sharp 28% price rise in three months, while positive for existing holders, increases the risk that short-term momentum reverses, particularly if the upcoming Q2 2026 earnings release disappoints relative to elevated expectations.
Analyst consensus and price targets
Conclusion
Healthpeak Properties offers a diversified, income-oriented exposure to US healthcare real estate, supported by constructive analyst sentiment, solid momentum, and a 6% yield. However, the stock is currently trading in line with the average analyst consensus target, the valuation multiples are stretched relative to earnings, and the recent sharp price run raises the bar for the forthcoming Q2 results. Investors may wish to weigh the income and long-term structural appeal of the healthcare real estate theme against the limited near-term upside implied by current consensus and the earnings uncertainty visible in the forward P/E.
This article was compiled by the Wall Street Stock Investors Club team based on analyst data on 20-07-2026. Not investment advice.